


Sage Group (LSE:SGE) is back in focus after extending its partnership with Findity, rolling out the Sage Expenses tool to Sage 50 customers in Spain and signalling further European launches in preparation.
Investors have already been rewarding Sage Group for its push into subscription software, with a 30-day share price return of 18.64% and a 90-day share price gain of 18.42%. The 5-year total shareholder return of 72.89% points to solid long-run compounding, even though the 1-year total shareholder return of 2.40% has been more muted. Recent momentum has picked up again around expansion moves such as the Findity rollout in Spain.
Scan Sage Group’s momentum in context by comparing it with a curated 5 high quality undiscovered gems that are quietly building recurring software revenue across niche markets.
Sage Group now trades with fresh momentum after the Findity rollout in Spain, which sharpens the question: Does that recent strength still leave enough upside to justify the current valuation risk?
Most Popular Narrative: 1% Overvalued
The most followed valuation view on Sage Group pegs fair value at £11.40, which sits just below the last close of £11.53. As a result, the narrative is effectively treating the stock as roughly in line with its calculated worth using a 9.7% discount rate.
Continued expansion of Sage Business Cloud and cloud native offerings, with cloud native revenue of £794 million and double digit growth, can increase the mix of subscription and recurring revenue and support more predictable cash flow and earnings.
Further roll out of Sage Intacct and X3 in North America and international markets, supported by over 20% ARR growth in the U.S. and about 50% ARR growth outside the U.S. for Intacct and strong double digit growth in X3, can add mid market customers and support top line growth and operating leverage.
See why 31 investors see Sage Group as 1% overvalued.
Result: Fair Value of £11.40 (ABOUT RIGHT)
Still, the Sage Group story can wobble if AI products remain hard to monetise, or if heavy buybacks plus leverage near 2x start to strain cash generation.
Find out about the key risks to this Sage Group narrative.
Another View: Sage Group Through A Cash Flow Lens
The first narrative treats Sage Group as roughly fairly priced around £11.40. A second lens tells a different story. Our DCF model estimates future cash flows are worth about £13.88 per share, compared with a recent price near £11.53, which frames the stock as undervalued on this method.
That gap reflects a simple question for you as an investor: Are the long term cash flow assumptions behind the DCF more convincing than the near term expectations that keep Sage Group close to analyst targets? Or do you see the risk sitting in those projections instead, especially around AI monetisation and leverage?
Look into how the SWS DCF model arrives at its fair value.
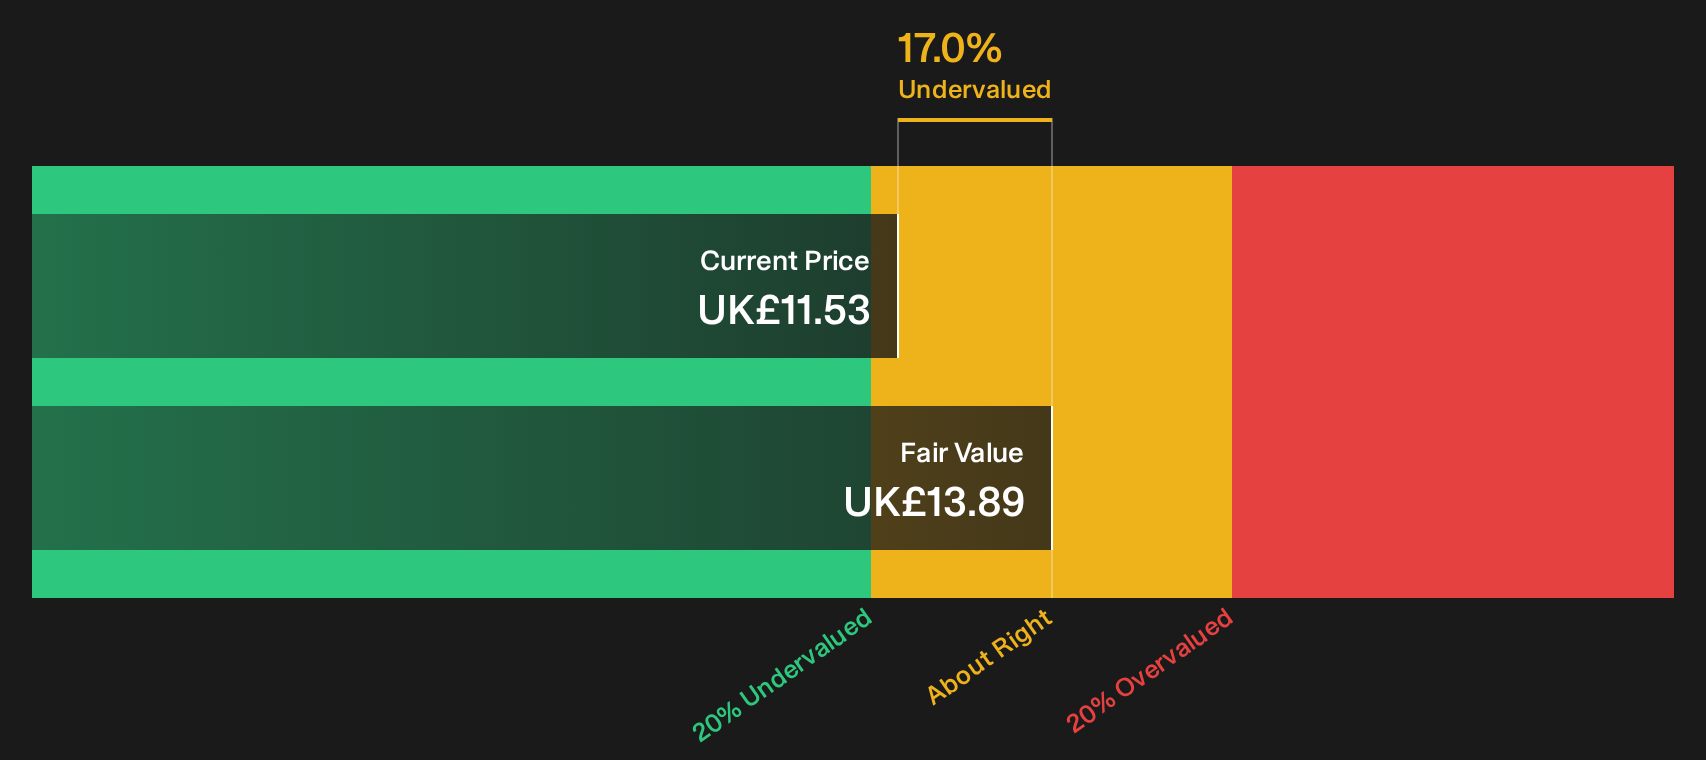
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sage Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 10 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sage Group so far, which makes this a moment to look at the numbers yourself and decide where you stand. To weigh both sides of the story, start with the balance between potential upside and the 3 key rewards and 1 important warning sign.
Looking for more Sage Group style ideas?
If Sage Group has sharpened your focus, do not stop here. Broader opportunity sits in front of you if you keep turning over fresh ideas.
- Target resilient income by reviewing 5 dividend fortresses that aim to balance yield with staying power through different market conditions.
- Hunt for mispriced quality with a focused 10 high quality undervalued stocks that filters for strong fundamentals at prices that may not fully reflect them.
- Prioritise sleep at night investing through a 5 resilient stocks with low risk scores that highlights businesses with lower risk scores and sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com