


- Fortis is set to report quarterly results for the period ended September 2026, with consensus pointing to earnings of $0.63 per share and higher revenue than the same quarter a year ago.
- The combination of expected earnings growth with a negative Earnings ESP of 5.26% highlights a tension between operational momentum and uncertainty around beating forecasts.
- Next, the focus will be on how Fortis' expected earnings and revenue profile could influence the longer term investment narrative.
Scan how Fortis stacks up against a hand picked 8 resilient stocks with low risk scores that focuses on resilience when earnings surprises are harder to call.
Fortis Investment Narrative Recap
To own Fortis, you need to be comfortable with a slow build story driven by regulated utilities, a long dated capital plan and relatively steady demand from power and gas customers. The key short term catalyst sits in how the September quarter sheds light on execution at UNS Energy and ITC as load trends, weather and wholesale pricing feed through earnings.
The biggest risk right now is not the headline EPS print but the mix of regulatory lag and rising interest costs against a heavy capital program. The latest earnings expectations, on their own, do not look like they fundamentally change that risk balance unless they flag a clear shift in cost recovery or financing pressure.
Recent commentary around Fortis has highlighted the CAD 28.8b capital plan through 2030 and record spend of CAD 5.6b in 2025 with a further CAD 1.4b in early 2026. That pipeline sits directly behind the current earnings release because it dictates where new rate base comes from and how reliably the utilities can convert that into regulated returns.
For you as a shareholder, the link is simple. Progress on data center and industrial load at ITC and Tucson Electric Power, LNG build out at FortisBC and coal to gas transition projects informs how realistic the planned rate base growth looks. Any signs that interest costs, regulatory lag or asset sales are biting harder than expected would sharpen the near term risk around that long haul plan.
Fortis Earnings Framework In Numbers
Fortis' narrative projects CA$14.8b revenue and CA$2.3b earnings by 2029. This assumes 6.2% yearly revenue growth and an earnings increase of about CA$0.6b from CA$1.7b today.
Uncover why Fortis' fair value indicates that Fortis is roughly in line with its current price.
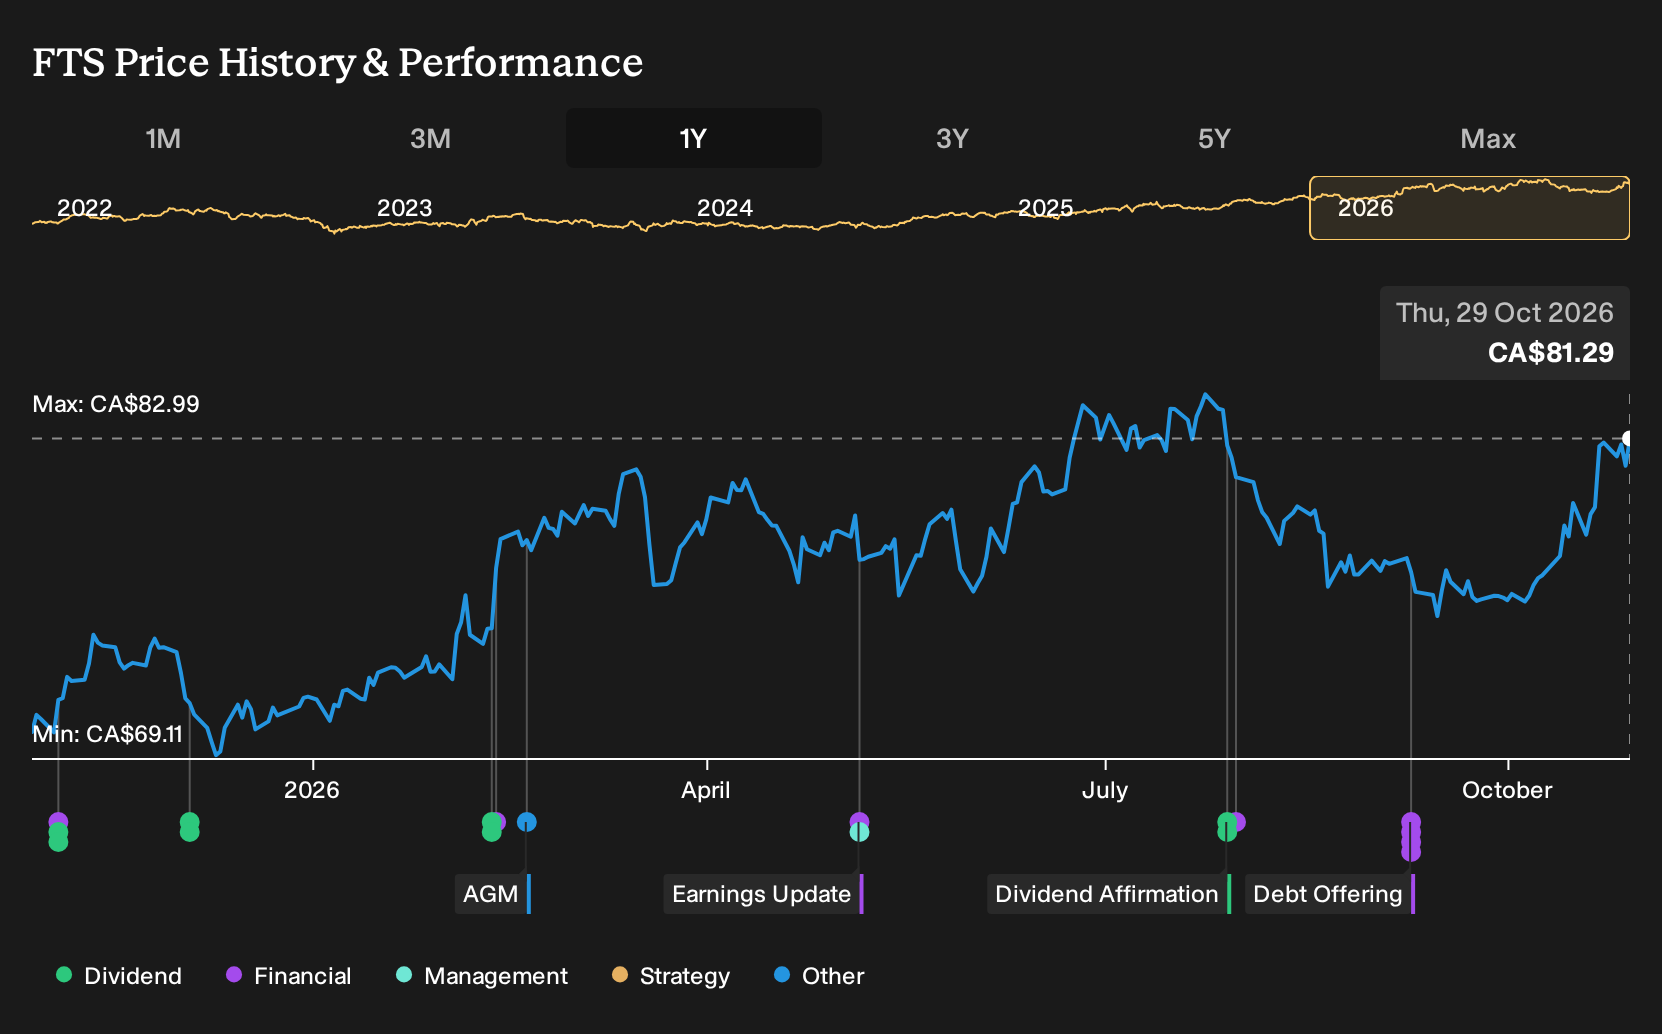
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community put Fortis anywhere between about 81% and 270% of the current price, so opinions are clearly all over the map. Set that against regulatory lag, portfolio sales and heavier interest costs. Those pressures could matter more to you than any single fair value line.
Explore 2 other Fortis fair value estimates, including one that suggests as much as 232% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fortis research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fortis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortis' overall financial health at a glance.
Looking for more Fortis-sized investment ideas?
Once you have a view on Fortis, it helps to benchmark that thinking against other opportunities that share similar qualities or offer a different mix of income, resilience and upside potential. The Simply Wall St Screener gives you a fast way to line those choices up side by side so you can see which ones really deserve more of your attention.
- For investors who want potential upside backed by solid fundamentals, compare Fortis against a curated set of 8 high quality undiscovered gems that already score well on quality metrics.
- If capital preservation sits high on your list, you can stress test your portfolio ideas against a 8 resilient stocks with low risk scores that filters for businesses with more resilient profiles.
- Income focused readers can cross check Fortis with a 3 dividend fortresses that targets higher yielding payers with an emphasis on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com