


Universal Music Group (ENXTAM:UMG) just signed a major licensing deal with TYGER, plugging its global catalog into a gaming-focused music service that adapts tracks in real time to gameplay.
For context, Universal Music Group shares trade at €15.84 after a 30 day share price return of 8.31% and a 90 day gain of 9.70%, yet the year to date share price return is down 27.86% and the 1 year total shareholder return has declined 29.15%. This points to some recent momentum rebuilding from a lower base as deals like the TYGER partnership reshape how investors think about its growth potential and risk profile.
Compare Universal Music Group's gaming push with other media opportunities by scanning our hand picked 607 high quality undiscovered gems that pair strong fundamentals with under-the-radar growth stories.
Universal Music Group is now rebuilding some lost ground after a sharp reset. The real question is whether this rebound barely scratches the surface or already captures most of the upside.
Most Popular Narrative: 31.9% Undervalued
On the most followed narrative, Universal Music Group screens as undervalued, with a fair value of €23.25 against the last close of €15.84. That gap is being framed around the resilience of its music catalogue rather than short term streaming noise.
The market is therefore not merely refusing to award UMG its historical quality premium. It is currently awarding almost none.
Meanwhile, the evidence I would expect to see if the franchise itself were deteriorating has not yet appeared.
See why 17 investors see Universal Music Group as 32% undervalued.
Result: Fair Value of €23.25 (UNDERVALUED)
Still, the UMG narrative can break if H2 cash conversion again disappoints or if Warner's stronger execution persists and erodes any argument for a quality premium.
Find out about the key risks to this Universal Music Group narrative.
Another View on Universal Music Group’s Valuation
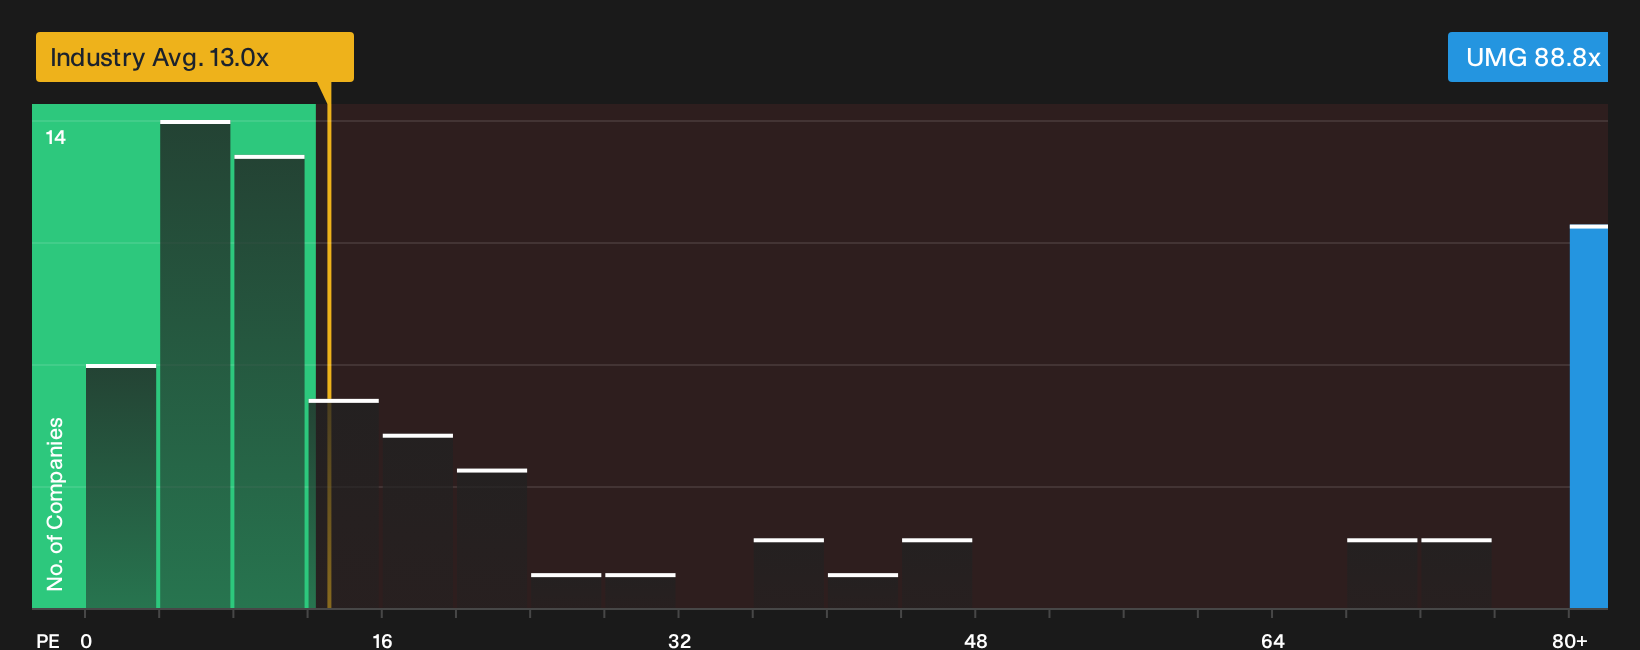
Multiples tell a different story. Universal Music Group trades on a P/E of 88.8x, while the European Entertainment industry sits around 13x and the peer average is 61.1x. The fair ratio of 32x suggests the market could compress that gap. This raises the question of whether this represents a valuation cushion or a risk if sentiment cools.
Investors weighing these conflicting signals may want to see what the numbers imply when stretched out over time, not just across peers. Further detail is available through our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Here is how Universal Music Group’s P/E compares visually with the broader sector and its fair ratio benchmark
Next Steps
If this mix of caution and optimism around Universal Music Group feels familiar, use it as a prompt to move fast and stress test your own thesis against both the upside and the downside. Start by weighing 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Universal Music Group?
Do not stop with Universal Music Group. Broaden your watchlist now, compare different opportunities side by side, and let the data challenge your instincts before the next move.
- Target quality at a discount and see which companies screen as potential value opportunities through the 194 high quality undervalued stocks.
- Strengthen your income stream by reviewing a hand picked set of yield focused opportunities in the 229 dividend fortresses.
- Dial down portfolio stress by checking companies that score well on resilience and stability inside the 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com