


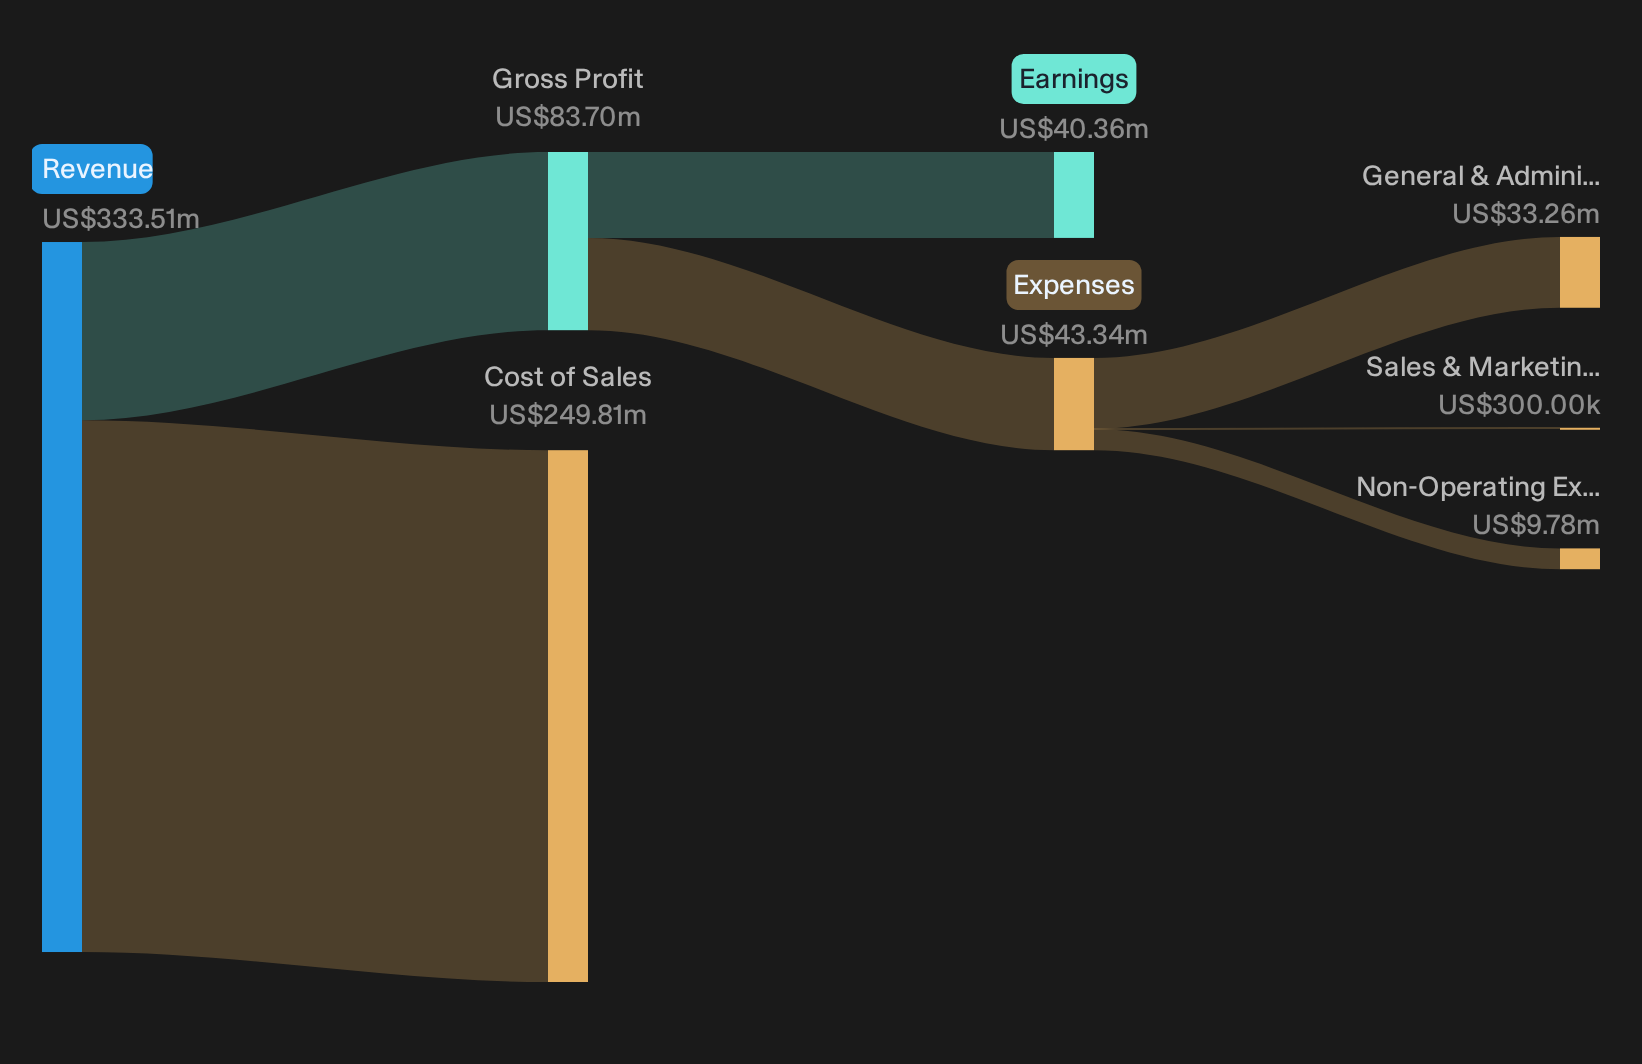
AMERISAFE just reported Q3 2026 results and the stock reacted first, thinking later. The shares dropped 8.7% today to US$23.09, extending a weak three month stretch, even though the latest quarter showed US$79.8m of revenue and US$7.2m of net income in a fiercely competitive workers compensation market.
The real stress point was profitability. Earnings per share fell to US$0.39 and the earlier reported expense pressure is now clearly biting into margins. Traders treated that as a verdict on the whole franchise. The fundamentals tell a more nuanced story. The rest of this report will unpack that.
Like AMERISAFE's underwriting discipline but worried about margin pressure affecting every earnings line? Filter for insurers with sturdier profitability profiles and solid balance sheets in our list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$79.8m vs. US$82.0m (slipped about 3%).
- Net Income (Q3 2026 vs. Q3 2025): US$7.2m vs. US$13.8m (roughly 48% lower).
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.39 vs. US$0.73 (fell about 47%).
- Combined Ratio (Q3 2026 vs. Q3 2025, key underwriting profitability metric for insurers): Not disclosed for Q3 2026 vs. 90.6% (indicating a less favourable overall margin picture with higher expenses and audit pressure).
Tired of scrolling through dense earnings reports and raw figures on AMERISAFE? Get a clear visual read on its valuation picture in an interactive dashboard via our company report for AMERISAFE.
AMERISAFE Bull Case Tested Against Softer Profit Print
The optimistic view hinges on AMERISAFE turning its distribution model and underwriting rules into enduring profit, not just occasional good quarters.
"The main condition for success is that AMERISAFE continues to translate its targeted agency strategy, strong policy retention, and conservative underwriting into attractive underwriting profitability, despite medical severity and pricing pressure."
Q3 shows mixed progress. Policy count rose about 4% and renewal retention held at 92.3%, which fits the agency story. Net premiums earned grew 3% and reserves produced US$6.9m of favorable development. However, basic EPS fell to US$0.39 and the expense ratio climbed to 32.5%, so profitability looks less resilient than the bullish script implied.
Margin Squeeze Narrative Finds Support In Q3 AMERISAFE Data
The cautious narrative argues that higher large losses and softer pricing could bleed into structurally weaker margins over time.
"Although AMERISAFE continues to post strong underwriting results with combined ratios near 90% and solid returns on equity, the rise in claims above US$1m and the increase in the current accident year loss ratio assumption to 72% suggest that any future shortfall in favorable prior year reserve releases could expose a structurally higher loss cost base and pressure net margins and earnings."
Recent numbers lean toward that concern. There are 18 claims above US$1m year to date versus 17 at this point last year, the current accident year loss pick is 72%, and EPS nearly halved year on year. Favorable development still supports earnings, but the heavier expense ratio and competitive pricing show how dependent net income remains on reserves and tight cost control.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Stories
AMERISAFE shows that headline profits and short-term share reactions can diverge significantly. The real opportunity is spotting stocks that could be undervalued before sentiment resets.
- Company 1 - 44% below our estimate - co-designs complex hardware with customers so design wins secure long production runs and pricing power.
- Company 2 - 43% below our estimate - routes cross border pay-ins and pay-outs as digital merchants shift increasing transaction volume onto its rails.
- Company 3 - 26% below our estimate - supplies critical chips and software that large customers embed deeper into data infrastructure and enterprise systems.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com