


Amerigo Resources closed at CA$7.77 on Thursday, after a 10.4% gain over the past week but still down 12.1% across the last month. Q3 2026 earnings put fresh fuel into an already active tape. The copper producer booked US$84.6m of revenue and US$22.7m of net income for the quarter, reinforcing a profitability story that has been building over the last year.
Short term traders see a hot chart. Long term holders see a miner generating cash in a business where the balance between price sensitive royalties and cost control will matter far more than today’s pop.
Love Amerigo Resources’ fresh profitability but want more copper exposure from producers with similar cash generation and disciplined balance sheets? Check out our curated list of list of solid balance sheet and fundamentals stocks (6 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$84.6m vs. US$52.5m (strong year-on-year increase)
- Net Income (Q3 2026 vs. Q3 2025): US$22.7m vs. US$6.7m (very large year-on-year increase)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.14 vs. US$0.04 (very large year-on-year increase)
- Copper Production (Q3 2026 vs. Q3 2025): 17.0m lbs vs. 14.6m lbs (higher quarterly output, with fresh tailings contributing about 71% of Q3 copper)
Tired of scrolling through dense earnings releases and raw figures for Amerigo Resources? Get a clear visual read on its valuation in an all-in-one financial dashboard via the company report for Amerigo Resources.
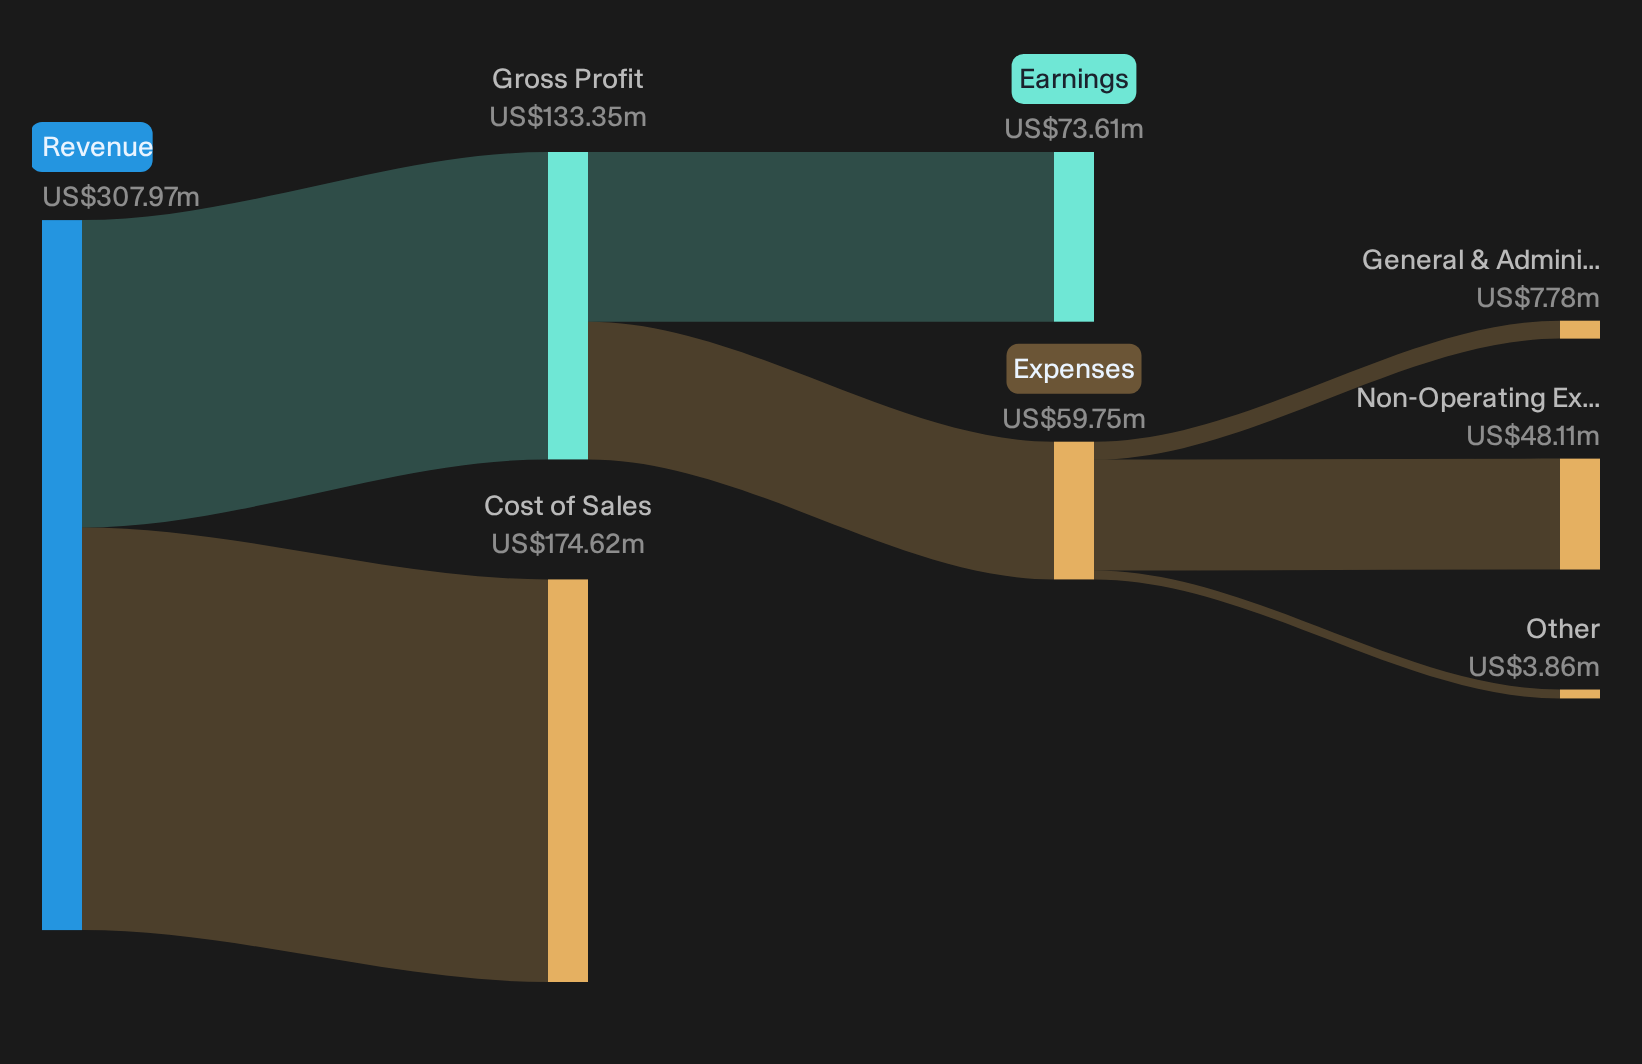
Amerigo bullish story backed by cash and costs
Amerigo Resources pitches itself as a copper leveraged, cash generative tailings processor. The latest quarter broadly fits that script. Revenue of US$84.6m, net income of US$22.7m, EBITDA around US$48m and free cash flow of US$28.1m show a business throwing off cash while debt free with US$50.1m on hand. Cash costs of US$1.55/lb and year to date normalized cash costs below guidance support the idea of an efficient plant that benefits when realized copper and molybdenum prices are firm.
Concentration, royalties and payout intensity temper the upside
The bear story on Amerigo Resources is about concentration and sensitivity to copper economics. Recent results keep that alive. All in sustaining cost rose to US$4.53/lb, mainly because DET royalties step up with higher prices. A weaker copper tape could therefore hit margins quickly. Heavy rainfall already limited historic tailings processing, underlining operational exposure in Chile. In addition, large performance dividends and buybacks mean the capital return program leans heavily on continued strong commodity pricing and stable terms with El Teniente.
Expose whether Amerigo Resources’ rainfall issues and royalty sensitivity are isolated or part of deeper structural problems. Review our risk analysis for Amerigo Resources which shows 2 important warning signsHunt Beyond Amerigo’s Headlines
Amerigo Resources just reported a quarter that alters how investors may view its profitability profile. The real opportunity could sit in stocks that look mispriced before the crowd reassesses their prospects.
- Company 1 - 45% below our estimate - target higher income shoppers as new prime mall locations and a maturing e commerce platform deepen omnichannel spending.
- Company 2 - 50% below our estimate - ramp access to higher grade ore at several sites while advancing new underground projects to extend reserve life.
- Company 3 - 35% below our estimate - add design and engineering acquisitions to a growing backlog of long term infrastructure and water projects, aiming to deepen recurring consulting revenue.
Those are three of them. See the full list of 4 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com