


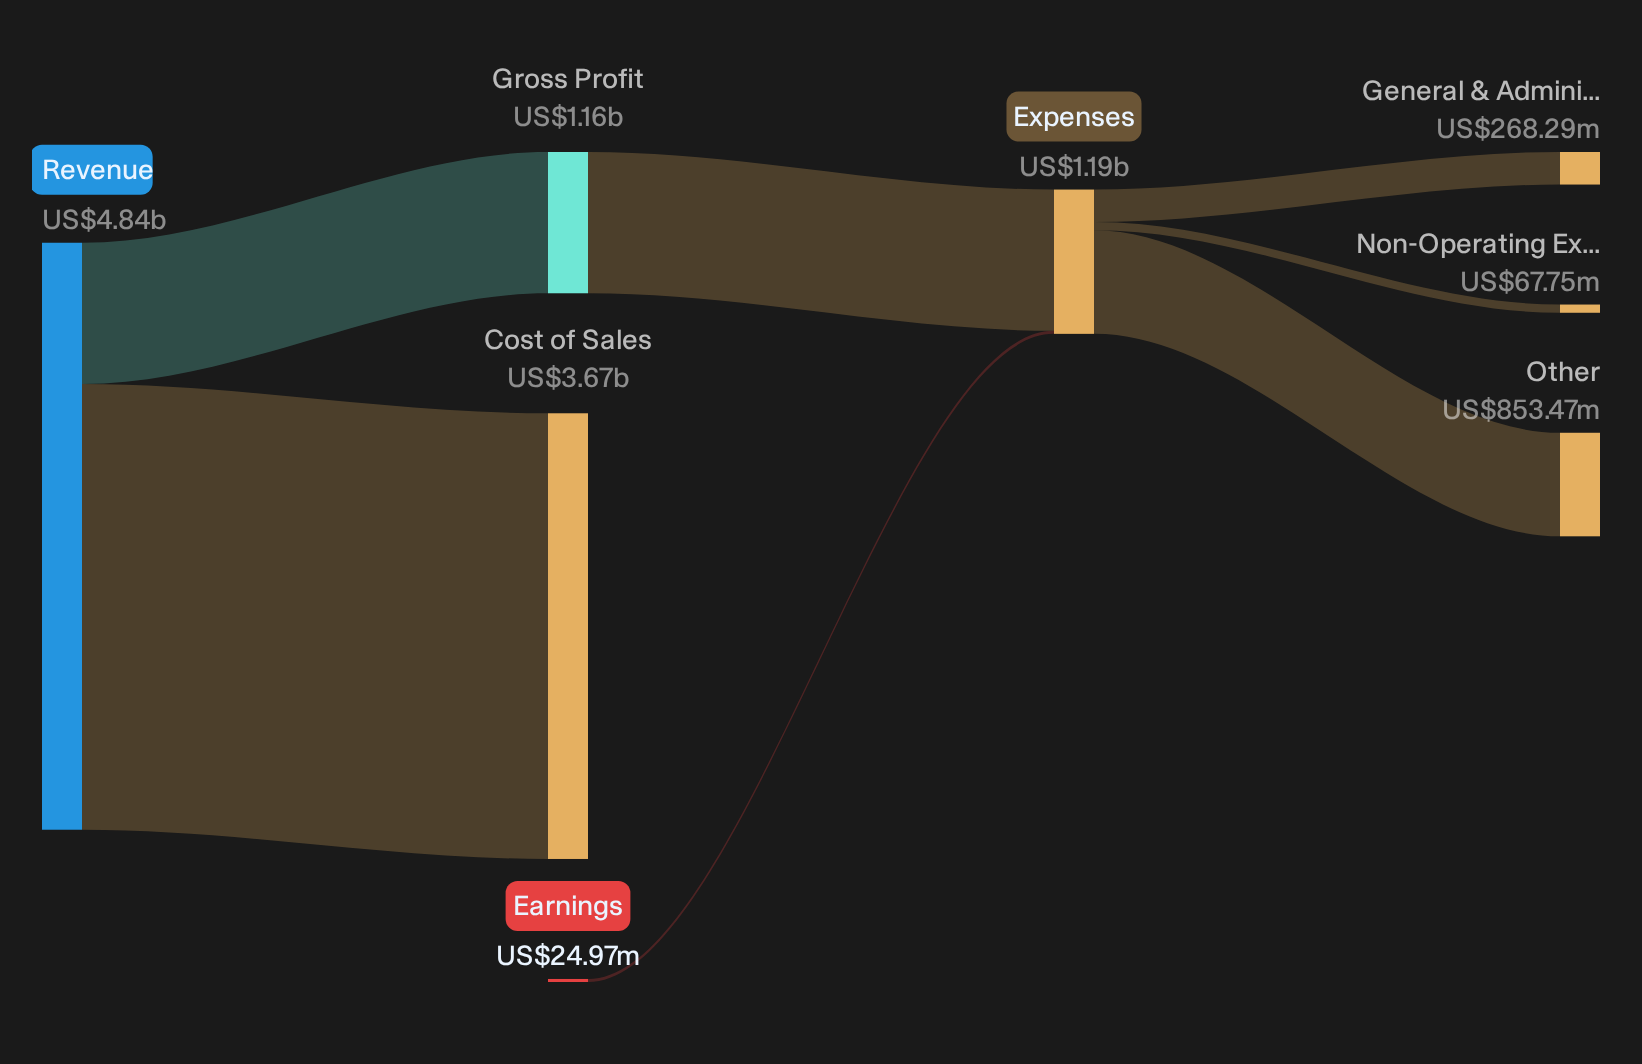
Patterson-UTI Energy barely moved on the screen today, with the stock edging up less than 1% around US$12.70, even after dropping fresh Q3 2026 numbers. The headline is simple: the driller swung back into the black with basic earnings per share of US$0.07 and roughly US$1.34b in revenue.
Short-term traders see a quiet reaction. Long-term holders see something different. A business that was loss making over the last twelve months just printed a profitable quarter, which now feeds directly into those multi-year profit forecasts and valuation debates around this stock.
Like the look of Patterson-UTI Energy swinging back into profit but worried about riding out another choppy earnings cycle? Benchmark it against a list of solid balance sheet and fundamentals stocks (22 results) to see how other cash generative operators stack up on resilience and financial strength.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,342.2m vs. US$1,176.0m (higher quarter on quarter against the prior comparable period)
- Net Income / Loss (Q3 2026 vs Q3 2025): Net income of US$28.4m vs. a net loss of US$36.4m (turned from loss making into profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.07 per share vs. a loss of US$0.10 per share (returned to positive earnings per share)
- Trailing Twelve Month Net Income (Q3 2026 TTM vs Q3 2025 TTM): Net loss of US$25.0m vs. a net loss of US$136.1m (losses narrowed on a trailing basis)
Tired of skimming through dense earnings releases and raw figures for Patterson-UTI Energy? Get a clear visual view of the full financial picture with a focus on valuation and how the market is pricing those fresh profits in the interactive company report for Patterson-UTI Energy.
Patterson-UTI Energy: Cash Story Meets Early Proof Points
"The main thing that has to go right is that Patterson-UTI Energy continues to execute on capital discipline and fleet high-grading, while scaling international and Drilling Products revenue so that free cash flow stays ahead of elevated capex and dividend commitments."
Patterson-UTI Energy just put some early ticks next to that checklist. Two consecutive quarters of revenue beats and a swing to a Q3 profit show fleet upgrades and rising activity starting to pay off. Higher rig utilization through Q3 and stronger U.S. onshore demand suggest high grading is gaining traction. What the release does not yet confirm is whether free cash flow is comfortably outpacing the higher 2026 capex and ongoing dividend outlays.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Bearish Cash Flow Concerns Meet Mixed Evidence
The cautious view says Patterson-UTI Energy could overcommit to spending and then struggle to keep cash generation and dividends covered if activity cools.
"Although Patterson-UTI Energy emphasizes a through cycle free cash flow model and has guided that 2026 adjusted free cash flow should more than fund the dividend, the combination of higher capital expenditure, working capital swings and episodic hits like storm related downtime creates a risk that future free cash generation falls short of current expectations."
Q3 tells a partial story. Earnings returned to a profit and revenue exceeded expectations; however, trailing twelve month results still show a loss and prior weak free cash flow margins linger in the background. The dividend was maintained rather than raised. With roughly US$600m of 2026 capex still ahead, the feared cash squeeze is not visible, but it is not clearly disproved either.
Hunt Quiet Disconnects In Plain View
Patterson-UTI Energy just showed profit returning while the share price barely reacted. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 23% below our estimate - embeds artificial intelligence into productivity and developer tools used across existing enterprise software budgets.
- Company 2 - 43% below our estimate - upgrades traditional signage into connected LED platforms that enable recurring revenue from software control and digital content services.
- Company 3 - 25% below our estimate - sells artificial intelligence focused networking hardware integrated with long term service contracts and subscription style infrastructure management.
Three companies from the same screener. Open all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com