


High inflation and interest rates have reminded investors how valuable cold hard cash flows can feel. The Federal Reserve kept rates steady while inflation readings stayed sticky, so dependable income from shares has fresh appeal. Well covered dividends above 3% can offer a tangible return while markets debate the next move on rates. This article highlights three income focused stocks with yields backed by ongoing dividend strength.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with well covered, steady payouts. However, if you want the absolute best, these 7 dividend aristocrats stocks are the cream of the crop.
Chevron (CVX)
Overview: Chevron is an integrated energy company that explores for, produces, refines, transports, and markets oil, natural gas, fuels, and chemicals worldwide.
Operations: Chevron generates revenue mainly from its Upstream businesses in the United States and internationally of about US$52.6b and US$55.1b, and Downstream activities in the United States and internationally of about US$82.5b and US$78.8b.
Market Cap: US$449.6b
Chevron earns a place in the Dividend Powerhouses screen because its large scale Upstream and Downstream operations generate the cash that supports a well covered yield above 3%. Those same projects are being reshaped to keep that income stream steady even as energy markets change.
"Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow."
What happens to that dividend strength if one unseen pressure on future cash conversion quietly shifts against Chevron’s current plans?
If that pressure is building, the full narrative for Chevron in the full narrative for Chevron shows how cash conversion could still accelerate or quietly stall.

LCI Industries (LCII)
Overview: LCI Industries supplies engineered components and replacement parts for recreational vehicles and related transportation and recreation equipment, serving manufacturers, dealers, service centers, insurers, and consumers.
Operations: LCI Industries generates about US$3.1b from OEM components and US$974 million from Aftermarket products, with roughly US$3.6b from the United States and US$391 million internationally.
Market Cap: US$2.37b
Income focused investors look to LCI Industries because RV components and replacement parts can create repeat business that helps support a higher yielding dividend, especially when those products reach far beyond the initial vehicle sale into long running aftermarket demand.
"Growth in the higher margin aftermarket segment, backed by an installed base with more than US$15b of replaceable content and around 1.5m units projected to enter repair cycles over the next several years, gives LCI Industries a path to increase revenue mix toward businesses that already carry around 14% operating margins."
The real test for LCI Industries is what happens if a single assumption about RV demand and adjacent markets quietly shifts against that margin story.
If that demand shift matters to your income plan, the full narrative for LCI Industries shows where RV cycles, margins and cash returns could be quietly decoupling or accelerating.

Hershey (HSY)
Overview: Hershey manufactures and sells branded chocolate, confectionery, salty snacks, and pantry items worldwide. It uses its North American confectionery and snacking engine to generate cash that supports its dividend.
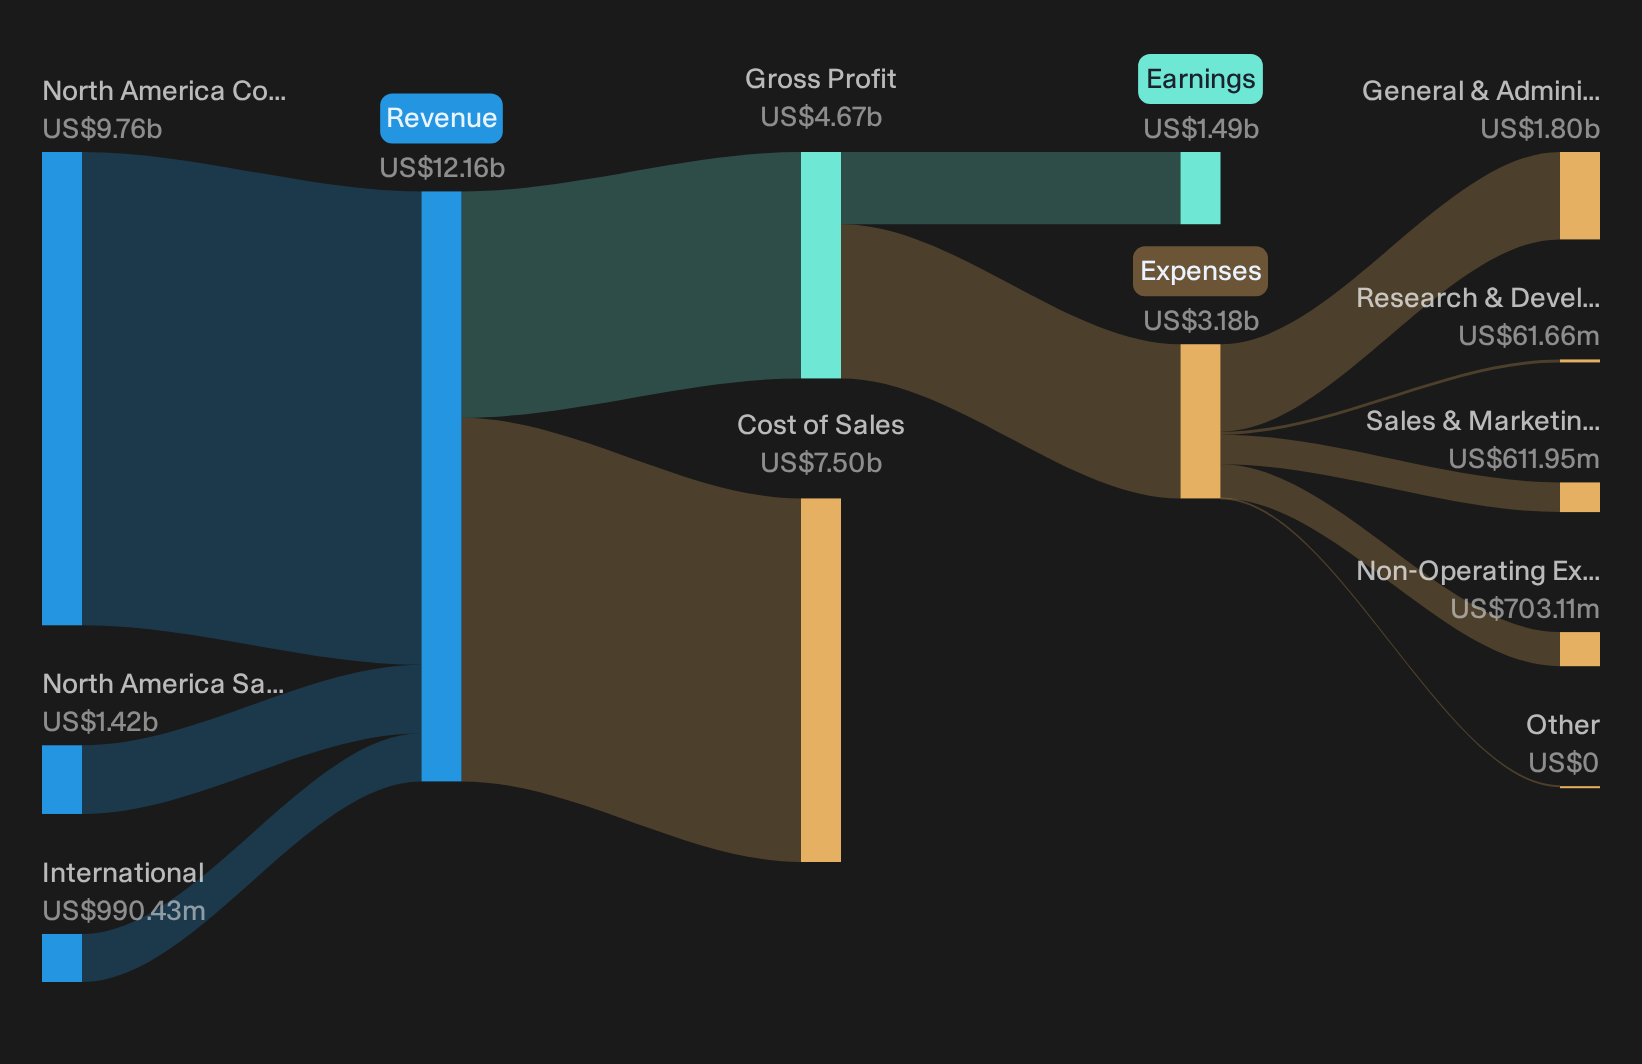
Operations: Hershey generates about US$9.8b from North America Confectionery, US$1.4b from North America Salty Snacks, and US$1.0b from International markets, with roughly US$10.6b from the United States.
Market Cap: US$32.9b
Hershey matters for a dividend focused investor because its everyday treats and salty snacks convert into steady cash flows that underpin a 3%+ yield.
"The forward thesis rests on three assumptions: that cocoa is structurally elevated but normalizing, allowing operating margin to recover toward a ~24% ceiling over the decade; that the One Hershey strategy extends the moat into salty, functional, and international adjacencies to sustain mid-single-digit (~3.5%) revenue growth."
The real leverage in that dividend story comes from what happens if one quiet shift in consumer behavior gradually reshapes pricing power.
As that pricing power evolves, the full narrative for Hershey maps where Hershey’s cash engine could be quietly accelerating, masking risk, or setting up a stronger dividend runway.
Seeking Alternatives Before The Crowd?
Fresh income ideas move fast. Some gain quiet momentum, others are identified before a breakout and a few are already flying under the radar for now. Act now.
- Spot potential high yield opportunities early by scanning a curated set of 7 dividend fortresses that aim to keep income flowing while prices are still dropping or overlooked.
- Track where AI demand meets real earnings power by reviewing 38 profitable AI stocks that aren't just burning cash before that story is fully priced in and momentum runs away from you.
- Position ahead of possible shifts in energy and infrastructure by reviewing 16 nuclear energy infrastructure stocks while these names are still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com