


CONMED just posted Q3 2026 results and the stock barely flinched. Shares slipped about 0.1% on the day, which is basically a shrug from the market.
That muted move sits against a far more emotional story beneath the surface. The headline this quarter is margin and earnings resilience, with adjusted earnings per share of $1.04 and adjusted gross margin at 56.4%. Traders treated the print like business as usual. The fundamentals, including 6.7% organic constant currency revenue growth once the exited GI business is stripped out, suggest sentiment may be underpricing what actually changed in the model.
Like CONMED's steady top line but wish you had a wider set of resilient compounders to compare it with? Check your watchlist against our list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$335.6 million vs. US$337.9 million (top line essentially flat year on year; organic constant-currency revenue up 6.7% when excluding the exited GI business)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$19.8 million vs. US$2.9 million (sharp improvement in underlying profitability)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.66 vs. US$0.09 (step change in per share earnings on an adjusted basis)
- Adjusted Gross Margin (Q3 2026 vs. Q3 2025): 56.4% vs. prior year level not specified (management highlighted a 40 bps uplift, pointing to better mix and pricing discipline)
Tired of scrolling through dense tables and line items trying to piece together CONMED's story from raw filings and earnings slides?
Get a clear visual snapshot of the business, including how earnings power compares with valuation, in the interactive company report for CONMED.
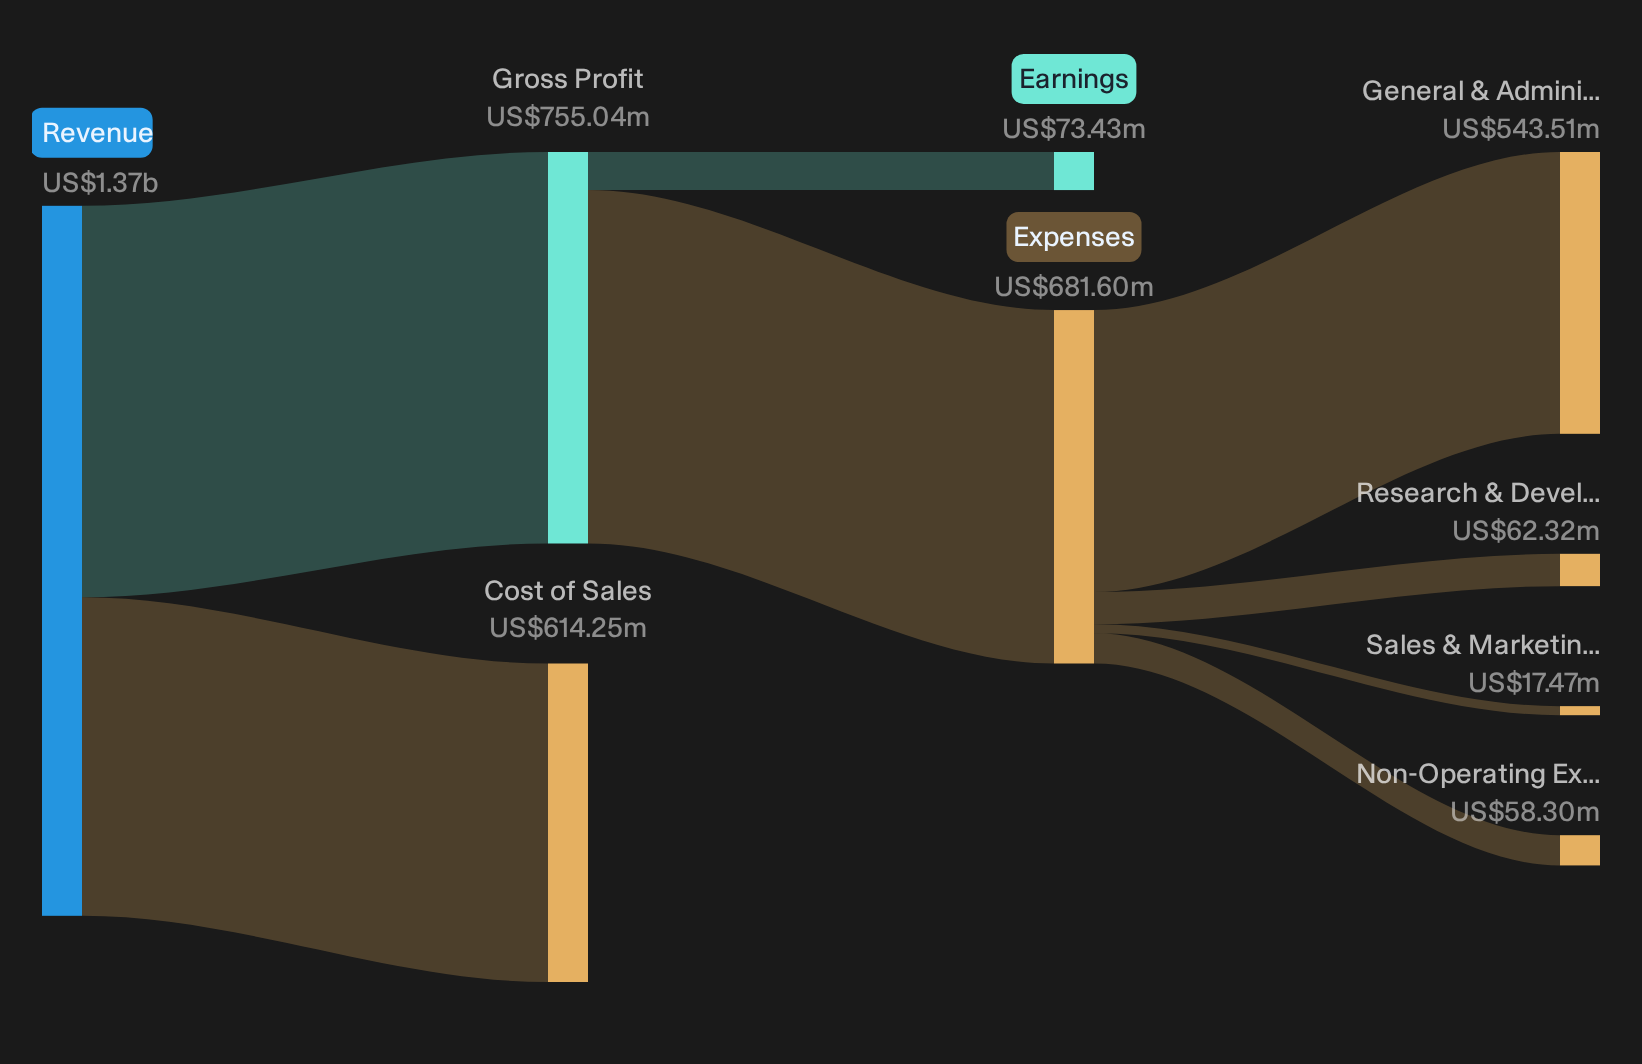
CONMED’s Mix Shift Claim Meets Real Margin Progress
Bullish investors argue that CONMED’s product focus can turn into sustained earnings firepower. The clearest version of that idea is management’s own ambition.
"The completed exit of lower growth gastroenterology products and sharper focus on minimally invasive surgery, smoke evacuation and orthopedic soft tissue repair gives CONMED more room to shift resources toward higher margin product lines, which can support gross margin expansion as the portfolio mix continues to change."
Q3 delivered early proof. Organic constant currency growth of 6.7% came entirely from the refocused portfolio, and adjusted gross margin reached 56.4%, with management attributing a 40 bps uplift to mix and pricing. AirSeal, Buffalo Filter direct sales and BioBrace all featured as primary growth contributors, while free cash flow of US$46.4m showed the model still converts earnings into cash even as GI revenue winds down.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
CONMED Bear Case: Growth Platforms Still On Trial
The cautious view argues CONMED’s flagship platforms may not pull enough volume to overcome scale constraints and higher interest costs.
"Although CONMED reports that AirSeal is used in only 6% to 7% of more than 3 million laparoscopic procedures in the U.S., concerns from external analysts about slowing organic growth suggest that this underpenetrated installed base may not convert into the volume and capital equipment pull through that prior expectations implied, which would constrain future revenue expansion."
Q3 organic constant currency sales grew 6.7%, so the feared growth stall is not visible yet. Still, as reported revenue was flat and free cash flow guidance holds at roughly US$115m while interest expense runs near US$33.7m, the milestone of clear scale leverage appears further out in time. AirSeal and Buffalo Filter are contributing, but not yet changing the overall growth profile.
Hunt For Quiet Fundamental Shifts
CONMED just showed how an earnings story and a muted share price can drift apart. The real opportunity sits in finding companies that could be mispriced before sentiment catches up.
- Company 1 - 32% below our estimate - builds specialized AI superclusters that large model developers use alongside existing cloud infrastructure.
- Company 2 - 16% below our estimate - turns expanded photonics manufacturing capacity into higher margin AI data center optical modules.
- Company 3 - 24% below our estimate - supplies advanced grid testing systems utilities deploy as they update infrastructure for electrification.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com