


ATI just dropped its Q3 2026 scorecard and the stock ripped 5.9% higher to US$175, even though much of the story was already telegraphed by a strong five year earnings record. Traders chased the move on one thing above all else: profitability.
Adjusted EBITDA hit US$328 million with a 23% margin, and adjusted EPS printed US$1.46. For an aerospace and defense materials supplier where a few basis points of profitability usually move the needle, that kind of margin performance is what is really driving today’s sentiment swing.
Love ATI’s punchy 23% EBITDA margin but want a wider set of high quality profit engines to compare it against? Scan the 38 profitable AI stocks that aren't just burning cash.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,423.7 million vs. US$1,125.5 million (+26%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$189.8 million vs. US$110.0 million (+72%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.39 vs. US$0.80 (+72%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 23% vs. 20% (expansion of 300 bps)
ATI’s margins hit their best level since 2007. Ask Charlie what drove ATI’s record margin jump this quarter.
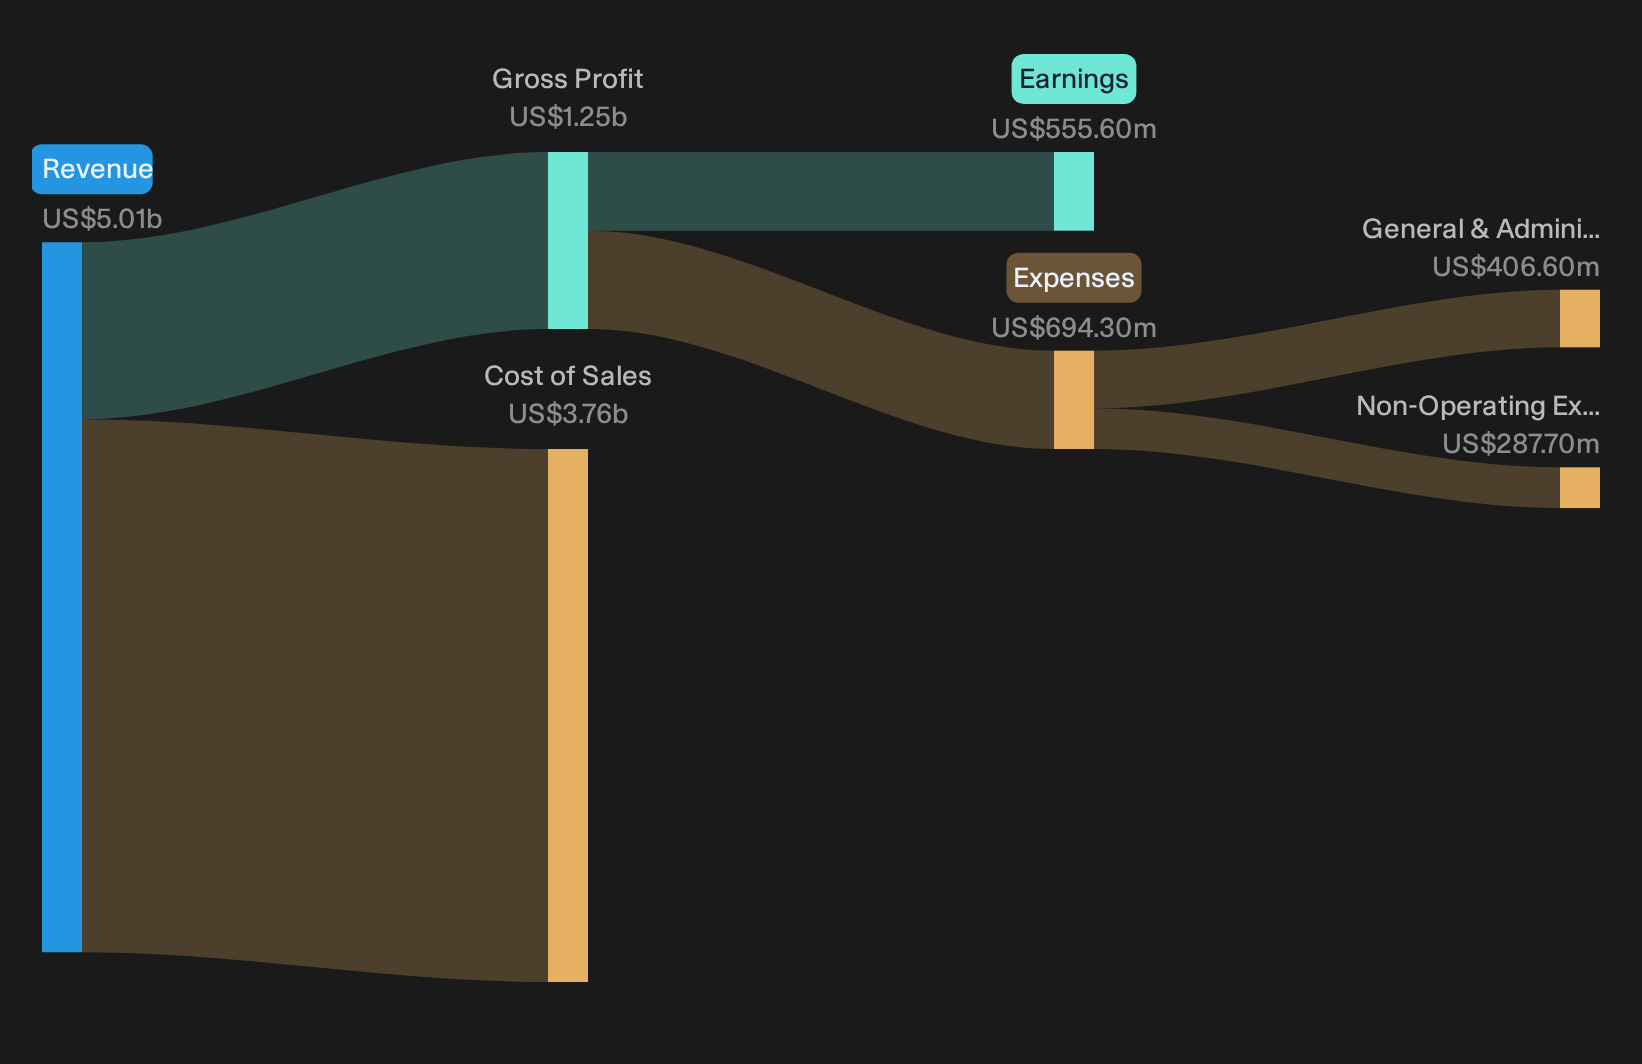
ATI’s Execution Claims Meet Hard Profit Evidence
The bullish script says ATI wins if it turns big contracts and new plants into higher quality earnings. That hinges on a very specific promise.
"The main thing that has to go right is that ATI continues to execute on customer aligned capacity expansions and the Elevation operating system so that contracted aerospace, defense and specialty energy demand flows through at the structural margin levels management is targeting."
Q3 gives that claim real backing. Revenue climbed 26% while adjusted EBITDA advanced 46%, which implies roughly 50% incremental margins. AA&S posted a 25.8% EBITDA margin and HPMC absorbed ramp costs yet still managed 23.2%. That pattern indicates that Elevation and capacity additions are translating into the richer profitability the thesis demands, not just volume growth.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
ATI Bear Case: Backlog Fear Meets Execution Data
For ATI, the skeptical view hinges on backlog risk and program concentration, not on demand drying up.
"While ATI Inc. is lifting throughput using its Elevation operating system and investing in new nickel and titanium capacity, extended lead times of up to 24 months on differentiated products increase the risk that customers seek alternative materials or suppliers before ATI can deliver. This could restrain shipment growth and limit future revenue conversion from the current backlog."
The latest quarter points the other way. Revenue grew 26% while backlog still sat around US$4.3b, up 20% year on year. That combination suggests orders are turning into shipments rather than stalling. No explicit evidence yet that long lead times are capping conversion or forcing material substitution, although the concentration risk in aerospace heavy programs remains unresolved by this print.
Hunt For Earnings Disconnects Now
ATI showed how sentiment can change quickly when profitability aligns with the narrative. The real opportunity is searching for stocks that may be undervalued before execution leads investors to reassess.
- Company 1 - 15% below our estimate - expand power and communications projects tied to hyperscale data center construction demand.
- Company 2 - 43% below our estimate - win larger visual systems as cities and venues replace static billboards with software-linked LED networks.
- Company 3 - 26% below our estimate - anchor digital infrastructure by supplying chips and software that manage data movement, connectivity and security.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com