


- Mattel hosted the first Fisher-Price Mini Marathon in New York City and is expanding the 26.2-foot baby racecourse event nationwide, using its 2-in-1 Musical Penguin Activity Walker and Moves with You Turtle Walker to spotlight mobility development for babies aged 6 to 18 months.
- The partnership with Mom Walk Collective turns product marketing into a recurring community event, which could deepen caregiver engagement with Fisher-Price and support demand for its developmental walkers across major retailers.
- The next area of attention is how this Fisher-Price Mini Marathon initiative, centered on developmental walkers, could influence Mattel’s broader investment narrative.
Mattel Investment Narrative Recap
To own Mattel, you need to believe its shift toward an IP driven play and family entertainment model can offset a slower toy market and relatively modest forecast revenue growth of 4.2% a year. The Fisher Price Mini Marathon fits that story as it deepens brand engagement, but the direct near term financial impact looks limited.
The near term swing factor remains execution on profitable growth targets as earnings are projected to decline 6.1% a year despite cost programs and a roughly 50% adjusted gross margin goal. A key risk is the heavy reliance on theatrical and licensed IP, where uneven performance could pressure margins and keep earnings under strain.
The most relevant recent development for this Fisher Price push is Mattel hiring Peter Griffith as CFO and appointing him to the board on October 20, 2026. He arrives with long experience in capital allocation, transaction execution and large scale efficiency work at Amgen and EY. This matters for a company balancing IP bets and cost controls.
For you as a shareholder, the question is whether a seasoned finance leader helps tighten discipline around marketing spend, digital games investment and theatrical tie ins while supporting community focused efforts like the Mini Marathon. Any improvement in working capital, debt management or margin quality would feed directly into the key catalysts investors already watch, especially given Mattel’s P/E of 10.3x and debt load.
Mattel's current analyst story points to revenues of US$6.2b and earnings of US$463.7m by 2029, based on an assumed 4.0% yearly increase in sales and an uplift in earnings of about US$36.3m from US$427.4m today.
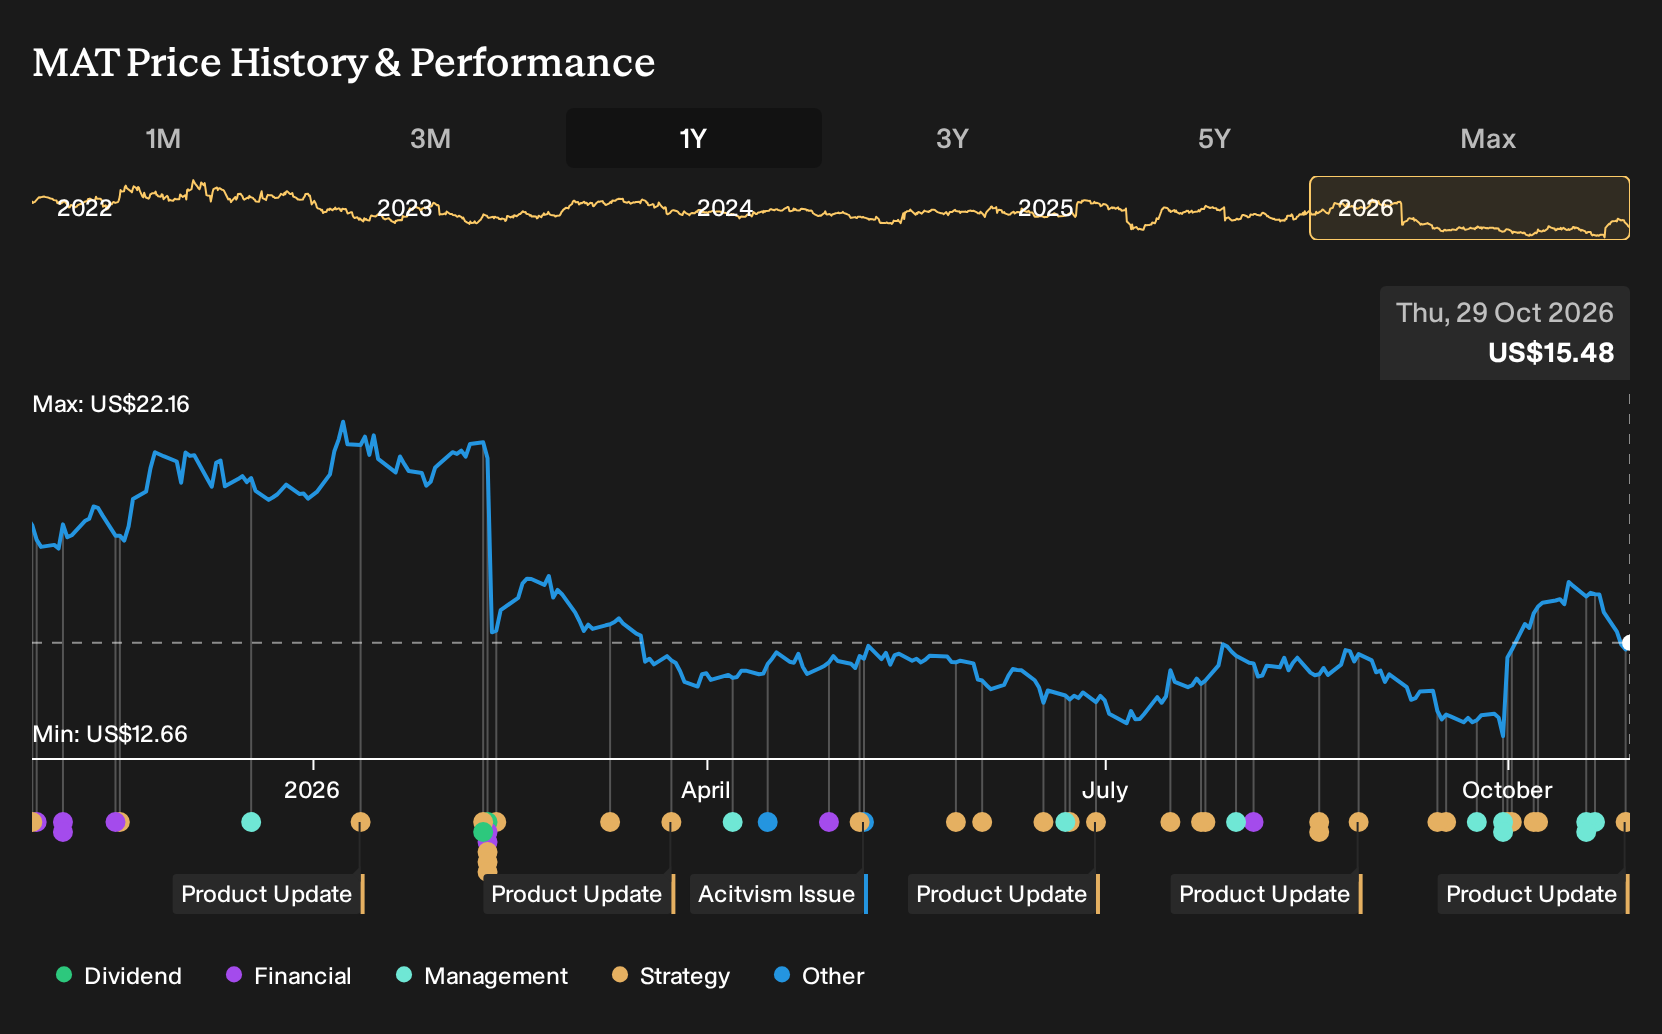
Uncover why Mattel's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is the bearish concern around Infant, Toddler and Preschool softness. The lowest analysts were pencilling in revenue of about US$6.0b and earnings near US$355.7m by 2029, well below consensus. Those views came before the Mini Marathon news, so you may see opinions shift as fresh information lands.
Explore 3 other Mattel fair value estimates, including one that suggests it could be worth just $15.95.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mattel research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Mattel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mattel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mattel?
If the Mattel story has you thinking about where else real-world demand, balance sheet strength, or income potential might show up next, the Simply Wall St Screener can help you line up a wider watchlist in a structured way.
- If you want income to do more of the heavy lifting in your portfolio, check out 7 dividend fortresses that could help anchor your cash flow with higher yields.
- For a focus on financial resilience, focus on companies in the list of solid balance sheet and fundamentals (22 results) that pair sturdier balance sheets with solid fundamentals.
- To search for earlier stage opportunities, track the 9 elite penny stocks with strong financials that show stronger financial profiles than many investors might expect.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com