


- Enbridge is facing renewed attention after recent commentary highlighted how rising natural gas demand from data centers and gas fired power generation could support the company’s expanding storage projects in North America.
- The interesting angle is how Enbridge’s growth in gas storage capacity links directly to real world power needs from data heavy infrastructure rather than purely financial engineering.
- We will now see how this data center driven gas demand theme could reshape Enbridge’s broader investment narrative.
Scan how other energy and infrastructure plays are positioned for the same data center and gas power theme by running the hand picked 43 power grid technology and infrastructure stocks alongside Enbridge in your research.
Enbridge Investment Narrative Recap
To own Enbridge, you need to believe its large pipeline and gas storage footprint can continue to earn solid, mostly fee based cash flows while it works through a heavy project and acquisition slate. The key short term swing factor is execution on gas storage and transmission projects tied to data centers and power demand, with a close eye on controlling costs and timelines.
The biggest near term concern is the balance sheet. Debt sits above the top of Enbridge’s preferred range and interest is not comfortably covered by earnings, while the dividend is not fully supported by profits or free cash flow. The recent data center focused gas narrative does not yet materially change that funding pressure.
The most relevant recent development is the emphasis on nearly 90 Bcf of gas storage expansion, including Tres Palacios, Egan, Moss Bluff and Aitken Creek. These assets are positioned in the path of rising gas needs from LNG, power plants and data facilities, which is where much of the current news attention is centered.
If Enbridge can bring these storage projects into service roughly on budget and on schedule, the business would gain more contracted, fee based earnings to help support interest costs and ongoing capital spending. Any delay or weaker than expected utilization would reduce the benefit of this demand theme and keep leverage elevated for a longer period.
Enbridge's narrative projects CA$79.3 billion in revenue and CA$8.1 billion in earnings by 2029. This aligns with analysts assuming revenue will decline by roughly 1.7% per year while earnings rise by about CA$2.4 billion from CA$5.7 billion today, helped by an improvement in profit margins.
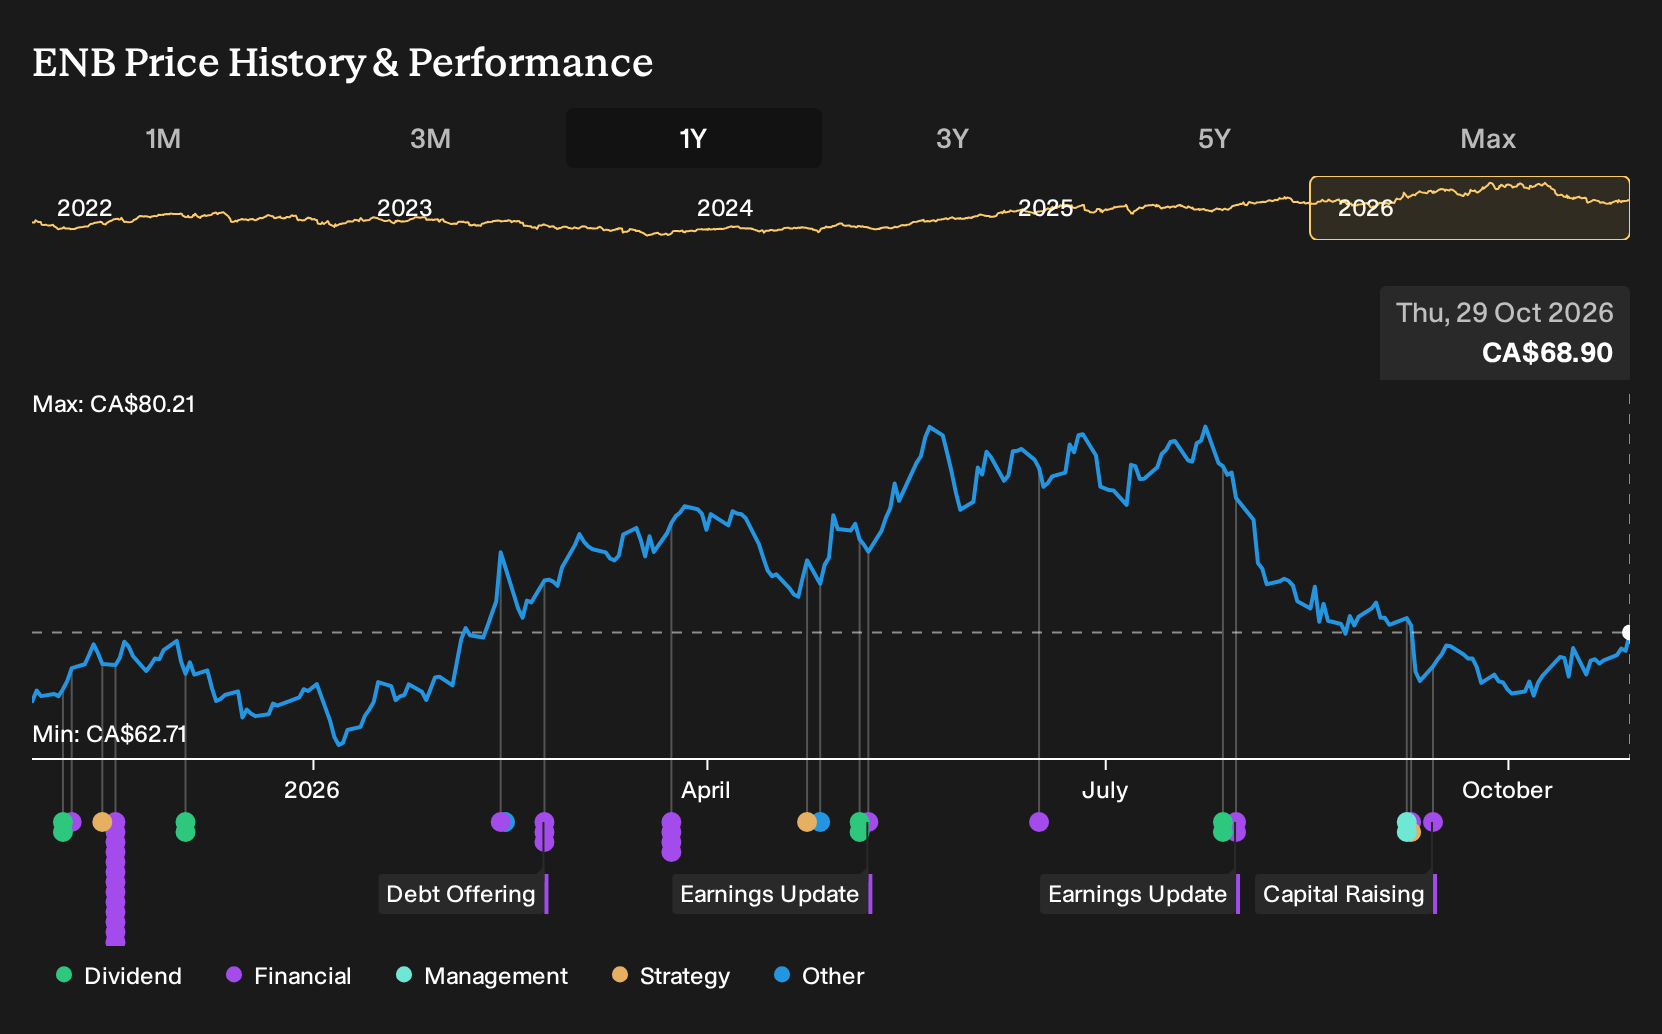
Uncover why Enbridge's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span from CA$47 to about CA$271. Some private investors clearly see Enbridge as deeply discounted, while others embed far richer expectations. When this is set against broker caution on leverage and project risk, it results in a wide debate that you should explore directly.
Explore 4 other Enbridge fair value estimates, including one that suggests as much as 32% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Enbridge research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enbridge. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enbridge's overall financial health at a glance.
Looking for more investment ideas beyond Enbridge?
Once the Enbridge story feels clear, widen the lens and compare it with other opportunities that fit different risk and income profiles.
- If you want potential value with quality at the core, start by scanning a curated set of 4 high quality undervalued stocks that pair stronger balance sheets with appealing valuations.
- For investors who care most about steady income, focus on reliable cash payers by running the 3 dividend fortresses and seeing which yields actually look sustainable.
- When capital protection is the priority, narrow your search to companies with more resilient profiles using the 8 resilient stocks with low risk scores and see how they compare to Enbridge on risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com