


- GenusPlus Group disclosed that on 21 October 2026 it received a shareholder proposal nominating external candidate Stephen Mayne for election to the Board, while the Board has urged investors to vote against his appointment at the 20 November 2026 annual meeting.
- This contested director nomination puts Board composition, governance priorities, and oversight of GenusPlus Group’s project pipeline and acquisition program under closer investor scrutiny.
- We will now consider how GenusPlus Group’s investment narrative could be influenced by this non Board endorsed director nomination push.
Compare the governance story at GenusPlus Group with other infrastructure and utilities peers by scanning our hand picked 43 power grid technology and infrastructure stocks now catching investor attention around board quality and capital allocation.
GenusPlus Group Investment Narrative Recap
To own GenusPlus Group, you need to believe that Australia’s long-term spend on power, communications, and grid upgrades keeps translating into a solid project pipeline and healthy utilisation of its Infrastructure, Services, and Energy and Engineering segments. The immediate swing factor is execution on large contracts without material cost overruns or delays. This latest board proposal is interesting, but on its own it does not materially change those near term operational drivers.
The bigger risk today remains operational rather than governance. Acquisitions, national expansion, and cost heavy project delivery can pressure margins if contract timing or pricing disappoints. Any slowdown in grid or renewable related work could also bite. Unless this director vote leads to actual shifts in capital allocation or risk appetite, it sits more as a sentiment and oversight watch point than a direct business shock.
The 21 October 2026 announcement about Stephen Mayne’s non Board endorsed nomination matters mainly because GenusPlus Group is already balancing growth ambitions, higher P/E multiples, and reliance on external borrowing. A shareholder push around board composition naturally focuses attention on how directors oversee leverage, capital deployment, and project risk in that context.
Investors will likely read this proposal alongside the existing picture of an independent, seasoned board and a management team tied closely to operational outcomes and CEO pay that tracks performance. The near term catalyst remains clean delivery of the current Australian project slate. Governance noise becomes more relevant if future board decisions start to visibly change acquisition intensity, funding choices, or tolerance for lumpier earnings from big grid jobs.
GenusPlus Group's narrative projects A$2.4b revenue and A$140.1 million earnings by 2029. This assumes 35.1% yearly revenue growth and an earnings increase of about three times from A$46.5 million today.
Uncover why GenusPlus Group's fair value indicates a 45% potential upside to its current price before that discount closes.
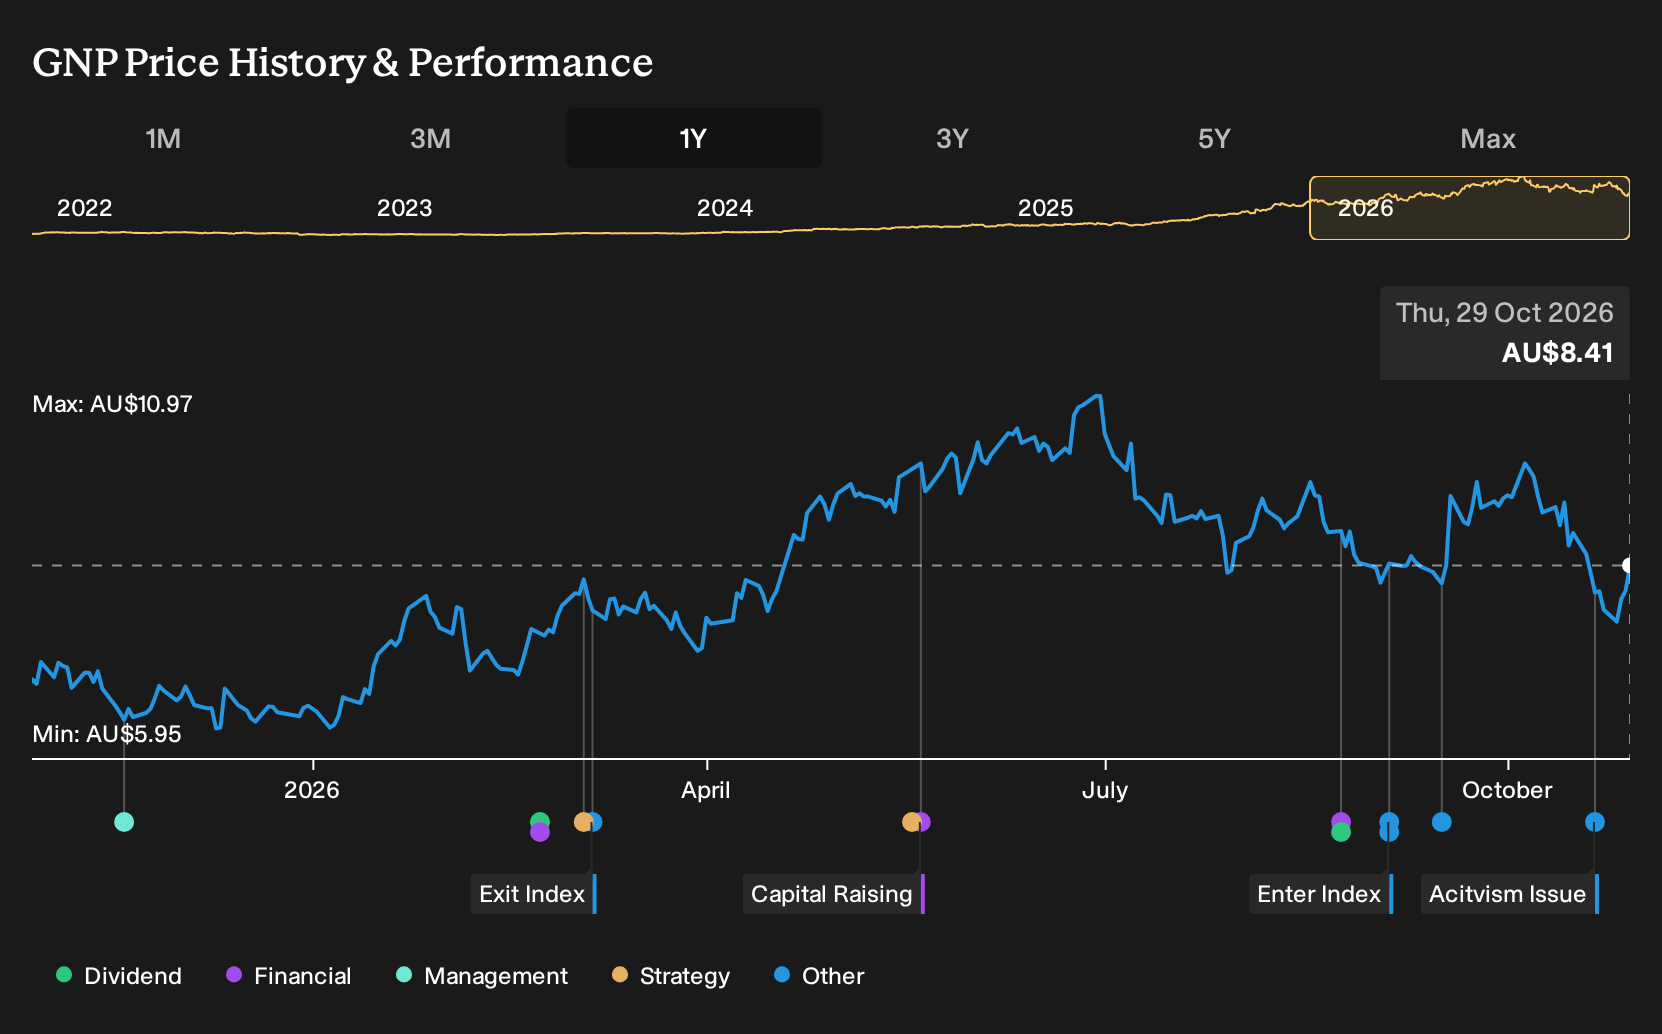
Exploring Other Perspectives
One alternate angle is that GenusPlus Group’s biggest swing factor is mega project execution rather than board composition. The most optimistic analysts were already pencilling in A$2.6b of revenue and A$142.2 million of earnings by 2029 before this nomination surfaced. You can treat this activism as a prompt to compare those upbeat assumptions with other viewpoints.
Explore another GenusPlus Group fair value estimate, including one that suggests potential upside of up to 45% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GenusPlus Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for GenusPlus Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GenusPlus Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond GenusPlus Group?
Once you have a view on GenusPlus Group, it can help to compare that thesis with other opportunities that line up with your risk tolerance and income goals. The Simply Wall St Screener gives you a quick way to scan for stocks that share similar traits or offer a different angle entirely.
- If capital preservation and smoother returns matter most to you, start with a shortlist of 6 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors who care about balance sheet strength and resilience through different cycles, review the list of solid balance sheet and fundamentals (12 results) and see which businesses clear a higher quality bar.
- If you want to hunt for opportunities the market may be underpricing, compare GenusPlus Group with 2 high quality undervalued stocks that currently screen as mispriced based on their fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com