


Why Trican Well Service’s Latest Earnings Matter For Investors
Trican Well Service (TSX:TCW) just released third quarter results that put fresh numbers behind the story. Sales and profit for the quarter differ from the picture over the first nine months.
The latest report shows third quarter sales of CA$338.3 million compared with CA$300.59 million a year earlier, alongside net income of CA$48.01 million versus CA$28.9 million. Earnings per share from continuing operations landed at CA$0.23 on both a basic and diluted basis, compared with CA$0.15 last year.
Looking at the nine-month period to September 30, sales came in at CA$883.17 million compared with CA$773.46 million a year ago. Net income for those nine months was CA$75.95 million compared with CA$80.25 million, with basic and diluted earnings per share from continuing operations at CA$0.36 versus CA$0.43 and CA$0.42 respectively.
Trican Well Service’s latest earnings update lands at a time when momentum in the share price has been building. The stock has recorded a 1-month share price return of 18.49% and a year-to-date share price return of 15.76% at CA$7.05.
Short term strength is not the whole story though. Over the past year, investors who reinvested dividends saw a 1-year total shareholder return of 39.94%. Meanwhile, 3-year and 5-year total shareholder returns of 62.81% and 127.16% highlight how the longer term outcome has compounded beyond the recent move.
Scout other energy service stocks showing similar momentum and earnings shifts with our curated list of list of solid balance sheet and fundamentals (6 results).Trican Well Service now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after this sharp run. Is that a cautious market correctly pricing risk, or a gap worth investigating in the valuation work next?
Most Popular Narrative: 11% Undervalued
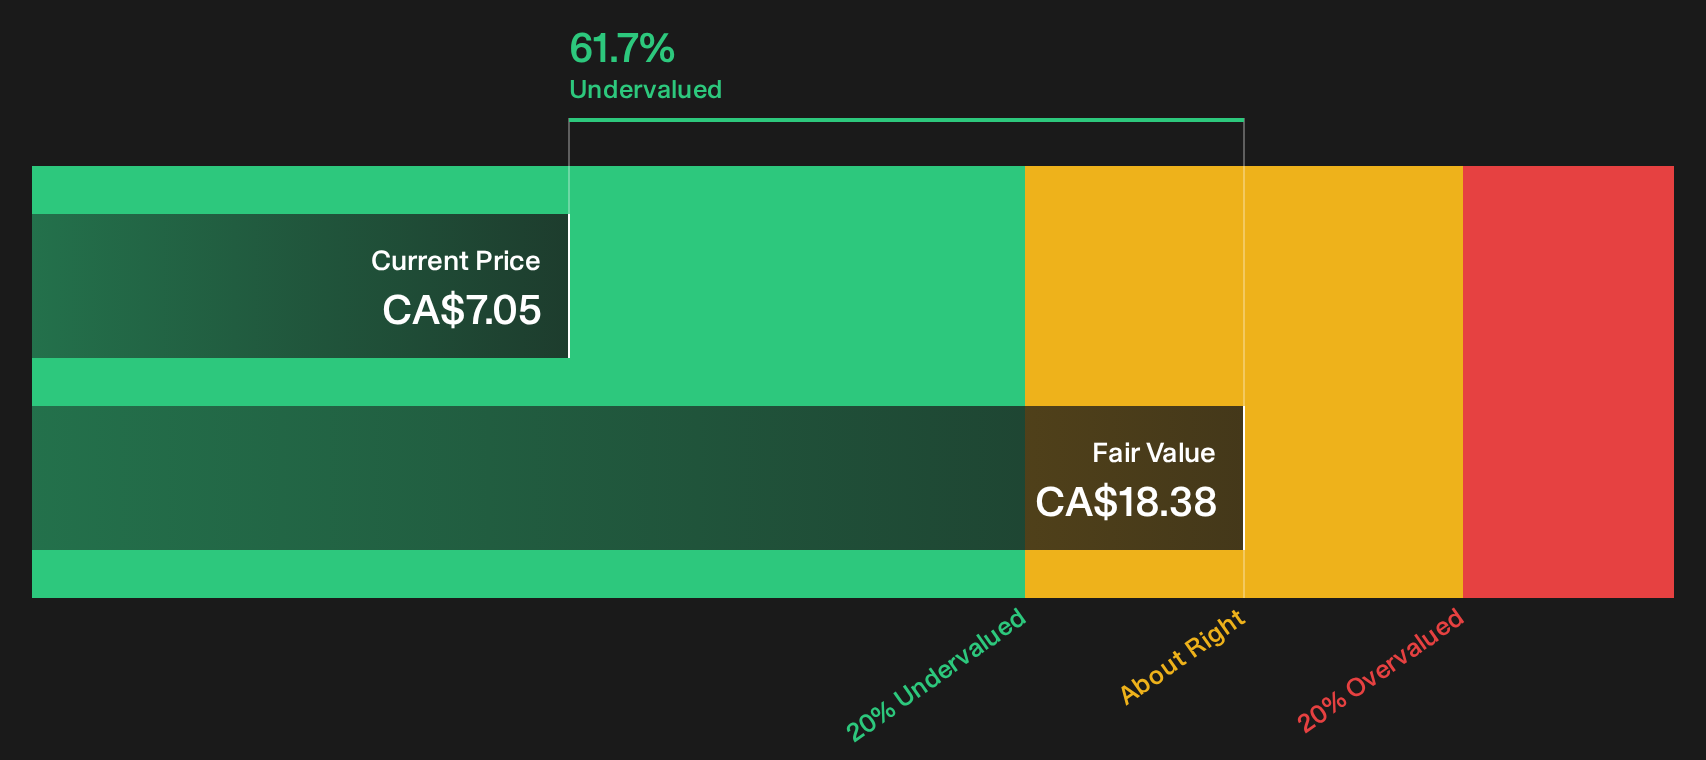
Compared with the CA$7.05 close, the most followed narrative on Trican Well Service anchors on a fair value of about CA$7.91 using a 6.74% discount rate. That view sits alongside a separate SWS DCF estimate of CA$18.38, so the current quote falls well below both reference points.
Rising well intensity and basin sand consumption, from about 4.5 million tonnes in 2021 to an expected 8.5 to 9 million tonnes in 2026 with forecasts up to 12 to 15 million tonnes, together with Trican Well Service running one of the largest sand trucking fleets hauling roughly 75% to 80% of the sand it pumps, provide a path for higher logistics revenue and better absorption of fixed costs.
See why 26 investors see Trican Well Service as 11% undervalued.
Result: Fair Value of CA$7.91 (UNDERVALUED)
Still, if Western Canadian gas activity softens or customers continue to self source more sand and consumables, the Trican Well Service thesis could look stretched.
Find out about the key risks to this Trican Well Service narrative.
Another Angle On Trican Well Service’s Valuation
On one side, the SWS DCF model points to a fair value of CA$18.38 for Trican Well Service, which is far above the current CA$7.05 share price and screens as undervalued. On the other, the stock trades at a P/E of 13.7x versus a fair ratio of 12.8x, which looks slightly expensive. Which lens deserves more weight when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Trican Well Service so far, or a clear tilt toward opportunity. Act while the data is fresh and weigh the 3 key rewards
Looking For More Investment Ideas Beyond Trican Well Service?
If Trican Well Service has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist now and give yourself more options.
- Target potential mispricing by scanning 4 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect their underlying metrics.
- Strengthen your income stream by reviewing 3 dividend fortresses that combine meaningful yields with business profiles built around regular cash returns.
- Dial down portfolio stress by filtering for 8 resilient stocks with low risk scores that score well on financial resilience and business risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com