


Quarterly earnings put American Electric Power Company (AEP) in focus
American Electric Power Company (AEP) is back on investors' radar after releasing third quarter 2026 results, reporting higher sales, revenue and net income compared with the same period a year earlier.
The American Electric Power Company share price has gained 8.42% over the past month and 11.68% year to date, while the 3 year total shareholder return of 81.88% and 5 year total shareholder return of 84.56% point to momentum that has been building rather than fading around the latest earnings beat, dividend increase and the advanced nuclear project announcement with Amazon and X energy.
Scan beyond American Electric Power Company and compare its recent earnings momentum and nuclear ambitions with a curated list of 43 power grid technology and infrastructure stocks poised to reshape future electricity infrastructure.
After a sharp move on strong quarterly results and fresh nuclear plans with Amazon and X energy, the real fork in the road is timing. Does buying American Electric Power Company after this run make more sense than waiting for a cooler entry based on the numbers?
Most Popular Narrative: 10% Undervalued
Against a last close of $129.34, the most followed narrative for American Electric Power Company points to a fair value of $143.23, putting today’s enthusiasm in the context of a longer capital and load growth story.
A growing pipeline of 69 GW of contracted load additions through 2030, heavily tied to data centers and hyperscalers in Texas and Ohio under long term agreements, can support sustained revenue growth for American Electric Power Company as these projects connect to the grid.
The expanded US$78b capital plan for 2026 to 2030, with a large share directed to transmission and new gas generation, can lift the regulated rate base and support higher earnings over time as projects enter service.
See why 54 investors see American Electric Power Company as 10% undervalued.
Result: Fair Value of $143.23 (UNDERVALUED)
Still, American Electric Power Company faces two obvious pressure points: execution risk on the 69 GW data center build out and any reduction in regulatory support for allowed returns.
Find out about the key risks to this American Electric Power Company narrative.
Another View: What AEP’s P/E Is Really Telling You
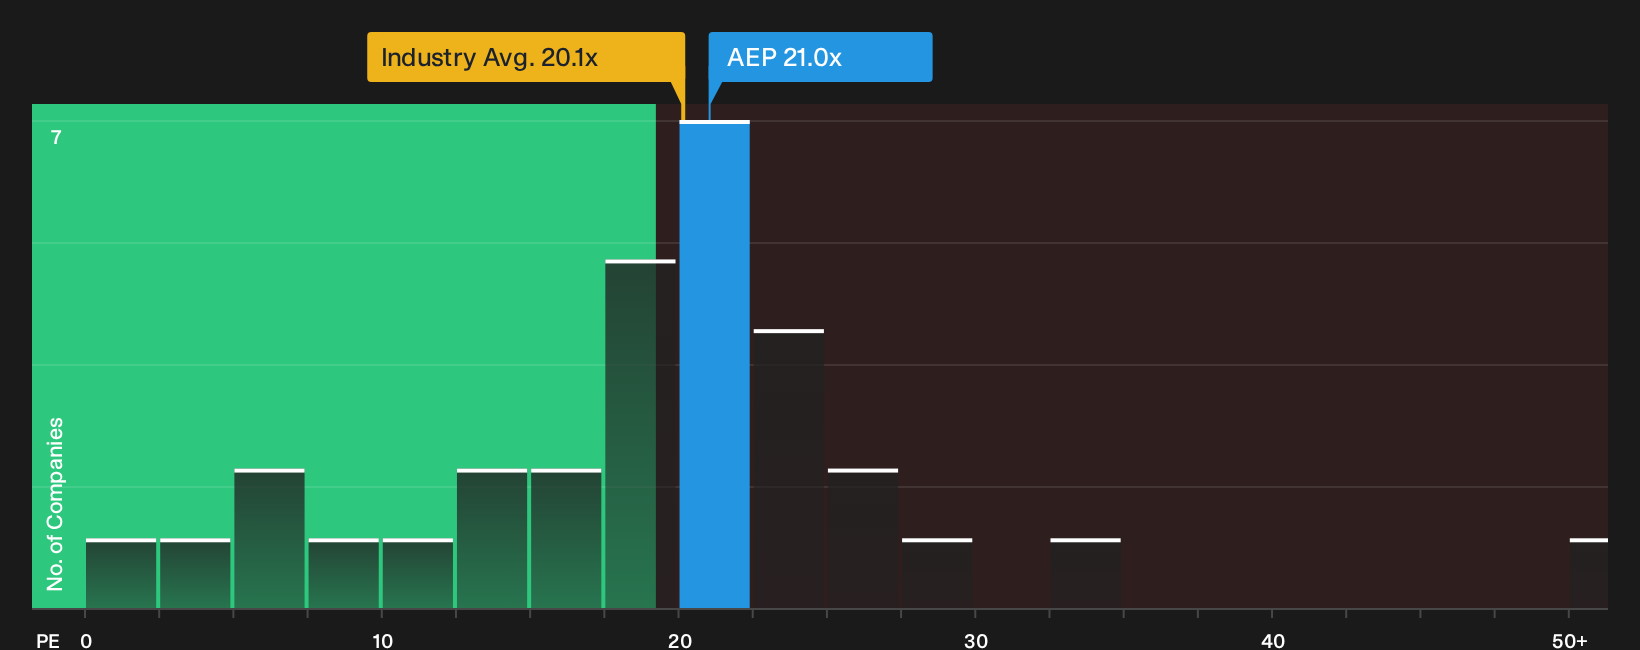
Fair value models point to upside for American Electric Power Company, yet the plain P/E story is less clear cut. The stock trades at about 21x earnings, which is slightly higher than the US Electric Utilities industry on 20.1x, but below peers at 24.6x and under a fair ratio of 22.3x that the market could move toward over time.
That mix suggests some valuation support if sentiment stays intact, while still leaving less room for error than the headline “10% undervalued” tag implies. With earnings growth forecasts sitting in the low double digits and a recent dip in profit margins, how much of the future data center and nuclear build out do you think is already in the price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far or leaning one way in your mind? You can act quickly by weighing both sides of the data and then grounding your own view in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond American Electric Power Company?
If American Electric Power Company has sharpened your focus, do not stop here. Broaden your watchlist now and keep your options open before the next move hits.
- Target reliable income by reviewing 7 dividend fortresses that aim to combine higher yields with resilient cash generation and balance sheet strength.
- Hunt for mispriced potential by scanning 18 high quality undiscovered gems where solid fundamentals are not yet reflected in wider market attention.
- Protect your downside first by filtering 30 resilient stocks with low risk scores that score well on financial health and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com