


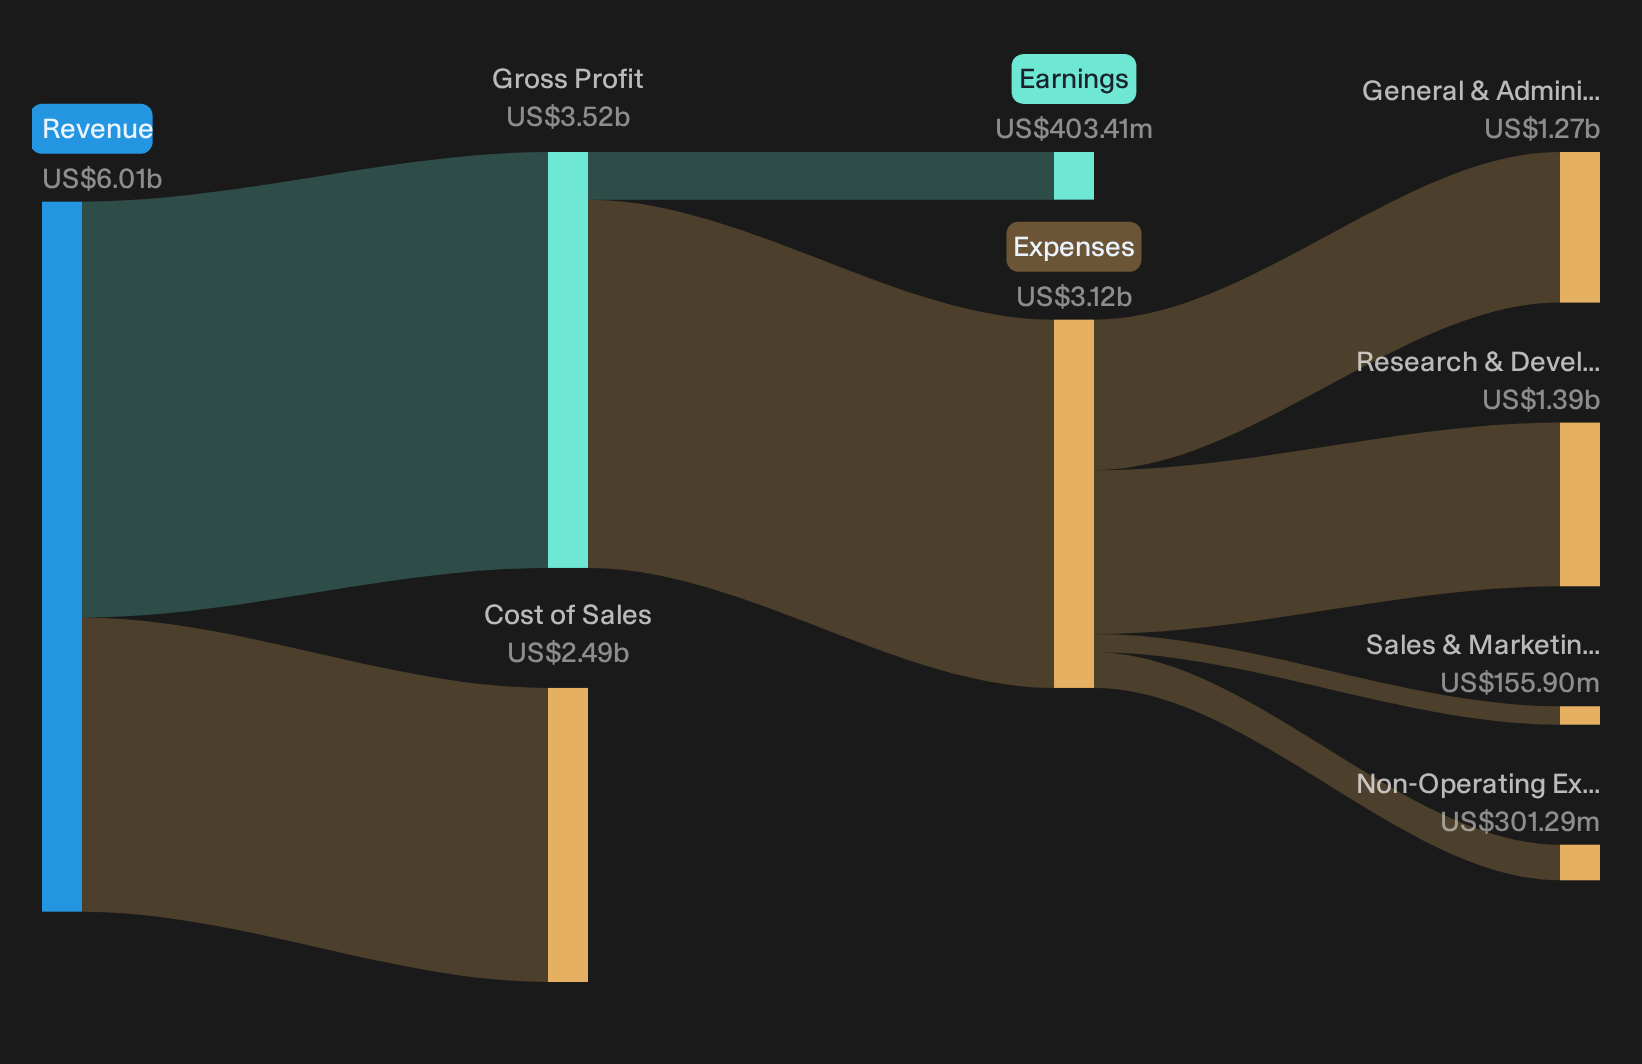
Incyte just posted its Q3 2026 scorecard and the market barely blinked. The stock slipped 0.1% to US$116.80 into Friday’s close, a flat reaction to a quarter where reported earnings swung to a loss and the income statement absorbed a heavy in process R&D hit from the Vega Therapeutics deal.
That tiny price move suggests sentiment is conflicted. Traders see an earnings wobble. The financials instead point to a classic biopharma margin squeeze story driven by one acquisition decision rather than a sudden collapse in the underlying franchises.
Love Incyte’s acquisition appetite but concerned about near term earnings noise from deals like Vega Therapeutics. Compare that playbook with a list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,557.2m vs. US$1,366.0m (up about 14%, matching management’s reported top line growth)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$784.8m vs. profit of US$424.2m (swung to a sizeable loss, driven largely by the Vega in-process R&D charge)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$3.86 per share vs. earnings of US$2.17 per share (moved from profit to loss on a per-share basis)
- Pipeline Breadth (Q2 2026 vs. Q2 2025, latest available detail): 10 products in Phase I, 6 in Phase II, 10 in Phase III vs. 6 in Phase I, 4 in Phase II, 5 in Phase III, 1 in pre-registration and 1 approved (R&D footprint has become meaningfully broader over the past year)
Evaluating Incyte’s Multi‑Franchise Expansion Claim
The bullish pitch hinges on Incyte turning today’s oncology and immunology mix into several durable franchises that blunt the future Jakafi cliff.
"Some analysts expect Incyte to extend the current shift from a single-product model to a multi-franchise company by building on recent revenue growth across Jakafi, Opzelura, hematology launches and the advancing late stage pipeline."
Q3 results give that idea more substance. Core ex Jakafi net sales reached US$490m with 30% growth, while Hematology & Oncology sales of US$235m rose 38%. Opzelura delivered US$255m, up 36%, and management raised 2026 guidance for Opzelura, Hem/Onc and total net sales. Multiple Phase III programs are now underway in CALR, G12D, TGF beta x PD 1 and latarcibart, which indicates that the pipeline piece is also moving from concept to execution.
One Narrative disagrees with today's price. → See where this Narrative says Incyte should trade.
Incyte Bear Case: Costs Are Rising, But So Is Diversification
Bears argue Incyte is locking in a higher cost base before replacement revenues are visible.
"the sharp step up in 2026 GAAP operating expenses to US$4.915b to US$4.995b risks resetting the long term cost base at a higher level than current non Jakafi sales can support."
The Q3 loss and US$1.23b Vega in process R&D charge clearly support the concern about heavier spending. Yet core ex Jakafi net sales of US$490m with 30% growth, plus raised 2026 net sales guidance to US$5.21b to US$5.30b, show diversification is tracking ahead of that bearish script, even if margin repair remains unproven.
Hunt For Mispriced Earnings Power
Incyte shows how headline net income can shift without much change in sentiment. The real opportunity is studying stocks that could be undervalued before the market corrects them.
- Company 1 - 15% below our estimate - taps hyperscale data center buildouts through fast growing electrical and infrastructure projects with a swelling contracted backlog.
- Company 2 - 44% below our estimate - converts a near record backlog of large civil projects into cash while working to contain legacy disputes and litigation exposure.
- Company 3 - 36% below our estimate - expands device recommerce by processing trade ins supported by policy incentives and rising consumer comfort with refurbished electronics.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com