


Exelon has delivered a 42.1% share price return over the past 5 years, and with the stock recently closing at US$45.91, many investors are asking whether that kind of performance still lines up with what its earnings can support today.
- A 42.1% gain over 5 years puts real weight on the question of whether Exelon’s current earnings profile can carry the price at recent levels.
- Regulators have cleared ComEd's GRIT grid upgrade project in Illinois, which may support expectations around future earning power but also shapes how quickly those cash flows arrive and what capital is needed along the way.
- Your read on Exelon is one view; the desks covering it have another. See what analysts think Exelon's shares could be worth.
The issue now is whether Exelon’s current share price is justified by the earnings investors are effectively paying for.
If you are weighing Exelon against other grid and utility plays, it can help to compare it with the 43 power grid technology and infrastructure stocks.
Does Exelon Look Undervalued on Earnings?
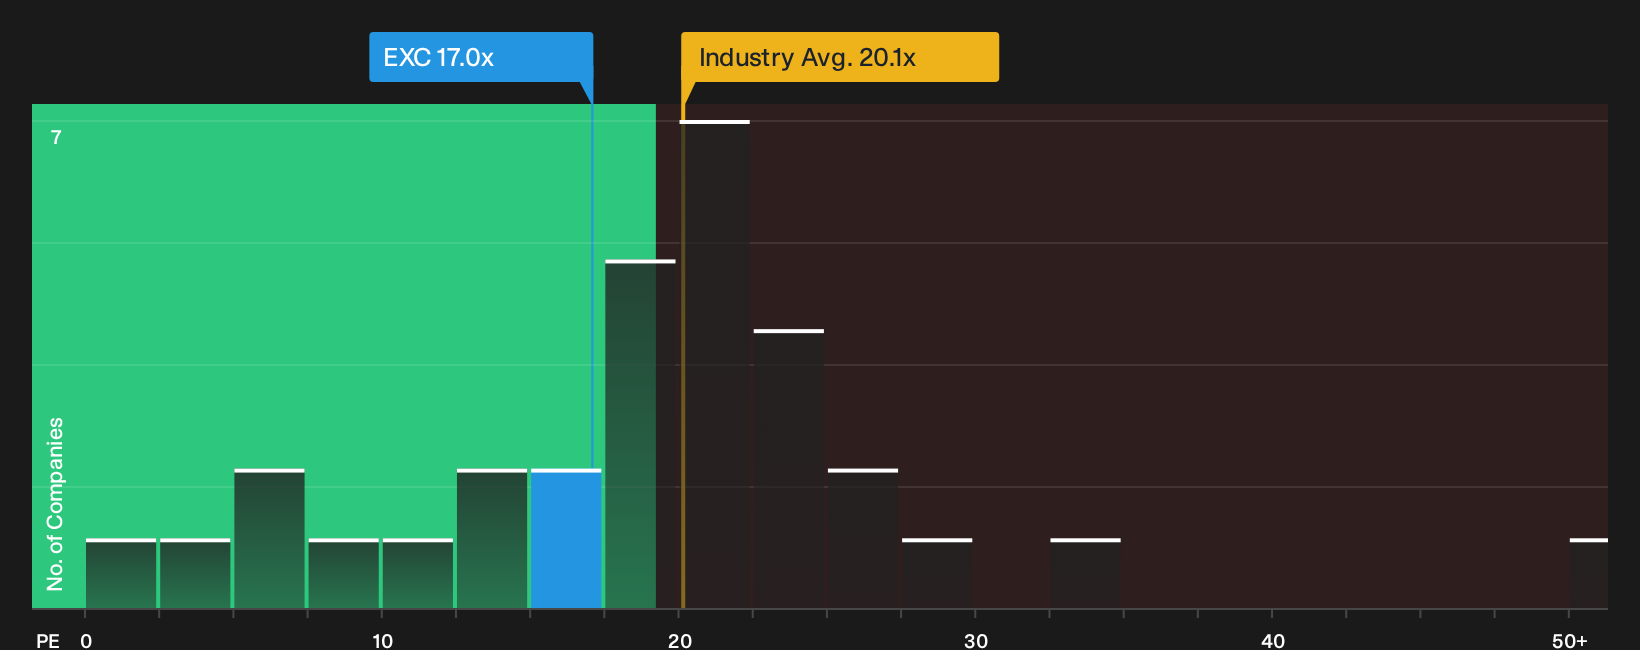
The P/E ratio fits Exelon because earnings remain the main lens investors use for regulated utilities. Exelon trades on a P/E of 17.0x, which is below both the Electric Utilities industry average of 20.1x and the peer group average of 23.7x. That slots the stock at a discount to what similar businesses currently command in the market.
The fair multiple implied by Exelon’s own profile, including its risk and profitability, sits higher than the current 17.0x level, so on this framework the shares screen undervalued. Because the GRIT transmission approval gives more visibility on a large regulated project, yet the P/E still trails sector and peer benchmarks, the price today reflects more caution than optimism. For readers comparing utility options, the size of that gap to the tailored fair value multiple is worth checking in detail. Explore the numbers behind Exelon's P/E valuation.
The Exelon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that valuation question on Exelon leaves off. They explain which combinations of future growth, margins and earnings power would need to occur for the stock to be worth materially more or materially less than today’s price. Each one links a fair value to a specific story about Exelon’s potential catalysts and key risks so you can track which version is unfolding over time.
One of the top community narratives on Exelon: roughly fairly valued
"Company wide efforts to cap adjusted O&M growth at no more than 2% annually through 2029 are aimed at supporting net margins…"
Discover why this Narrative puts Exelon at roughly fairly valued.
The price is only one piece of the Exelon puzzle
Share prices and P/E ratios tell you what the market is paying today, but analyst expectations for Exelon a few years out offer a separate lens on where earnings might be headed. Explore where analysts expect Exelon to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com