


Liberty Latin America has delivered a mixed share price story over the past few years, which naturally puts the focus on what investors are paying for its sales today. With the stock at US$8.36, the real issue is how that price lines up against the revenue the telecom operator is generating across its markets.
- Over 5 years the stock has fallen 37.6%, which makes the current valuation question much more about what the business can earn from its existing sales base than about past share price moves.
- For a capital intensive telecom operator like Liberty Latin America, the way network spending, operating costs and pricing feed through to revenue can shape how much investors are willing to pay for each dollar of sales.
- There is a second opinion on Liberty Latin America worth weighing. See what analysts think Liberty Latin America's shares could be worth.
The issue now is whether Liberty Latin America's current share price is adequately supported by the sales it generates today.
If you are weighing Liberty Latin America purely on what investors pay for each dollar of its sales, it helps to compare that lens with other businesses through 30 high quality undervalued stocks
Is Liberty Latin America a Bargain on Sales?
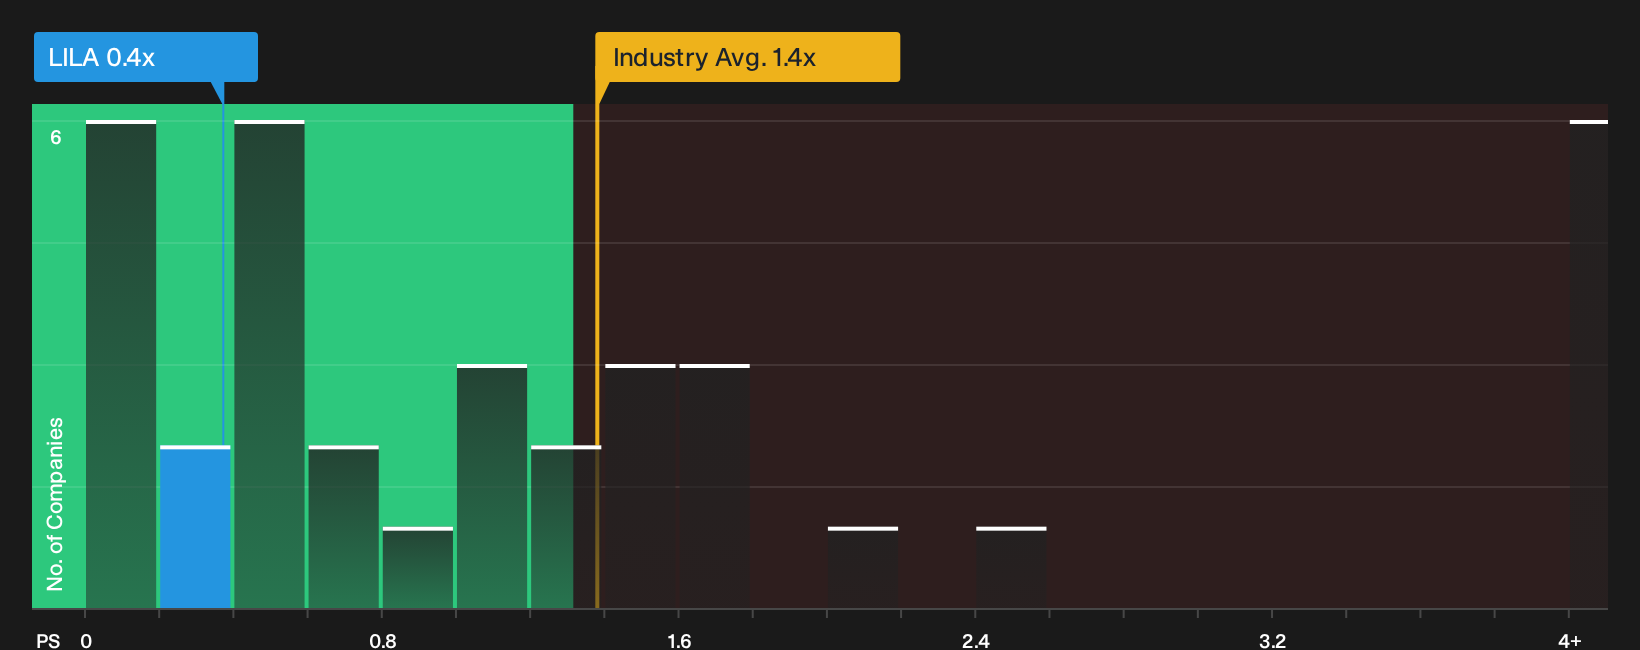
The price to sales lens fits Liberty Latin America because telecom revenue can be more stable than accounting earnings, which makes top line based ratios useful. On this measure, the stock trades on a P/S of 0.4x, which is far below the wider telecom industry average of 1.4x and also under the peer group on about 1.7x. That sort of gap tells you the market is paying far less for each dollar of Liberty Latin America’s revenue than it does for many comparable carriers.
The fair value model that adjusts for Liberty Latin America’s own mix of growth, profitability, scale and risk points to a higher P/S than where the shares change hands today. So the current 0.4x multiple sits on the low side of what that framework would suggest, which indicates the stock screens as undervalued on sales. The key question for you is whether the quality and durability of those revenues justify the market’s discount or challenge it. Explore the numbers behind Liberty Latin America's P/S valuation.
The Liberty Latin America Narrative: What Would Justify Today's Price?
Narratives pick up where Liberty Latin America's low P/S puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on Simply Wall St's Community page. Each one frames fair value as a thesis about the business that can be revisited over time, so you can see how the reasoning holds up as new information arrives.
Community views on Liberty Latin America are split between those who see discounted contracted cash flows and those who focus on balance sheet strain and execution risk.
Bull case: 40% undervalued
"Further build out of Liberty Networks subsea routes such as the El Salvador project, the Phoenix cable into Venezuela and the Manta build could shift the business mix toward long term wholesale leases and enterprise connectivity…"
Discover why this Narrative puts Liberty Latin America at 40% undervalued.
Bear case: 19% overvalued
"Portfolio moves such as the sale of the Peruvian fixed broadband business and issuance of 9.0% preference shares, combined with ring fenced financing at Liberty Puerto Rico, could leave the remaining footprint more concentrated in slower growth or higher risk markets…"
Explore why this Narrative puts Liberty Latin America at 19% overvalued.
One more Liberty Latin America check that belongs beside the price tag
Numbers only tell part of the story, because the people steering Liberty Latin America and the way their incentives are structured can heavily influence what happens next for shareholders. See who runs Liberty Latin America and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com