


Etsy Inc. has rebounded sharply in recent months, and that swing is forcing investors to ask whether the current price can be squared with what the business is earning today. After a long and volatile ride, the key issue is whether the recent enthusiasm lines up with the underlying profit power of the marketplace.
- Over the past 5 years the stock has fallen 66.2%, which puts a lot of weight on the question of whether the present valuation now rests on a sturdier earnings base than in the past.
- Recent revenue growth, stronger buyer activity and efforts to refine the shopping experience can support expectations for steadier earnings and cash generation, which all feed directly into how much investors may be willing to pay for each dollar of profit.
- There is a second opinion on Etsy worth weighing. See what analysts think Etsy's shares could be worth.
The issue now is whether Etsy's current share price is adequately supported by the level and quality of the earnings it is producing.
If you want a broader watchlist while you assess whether Etsy's earnings justify the current move, a focused screen of 30 high quality undervalued stocks can be a useful second starting point.
Has Etsy Run Too Far on Earnings?
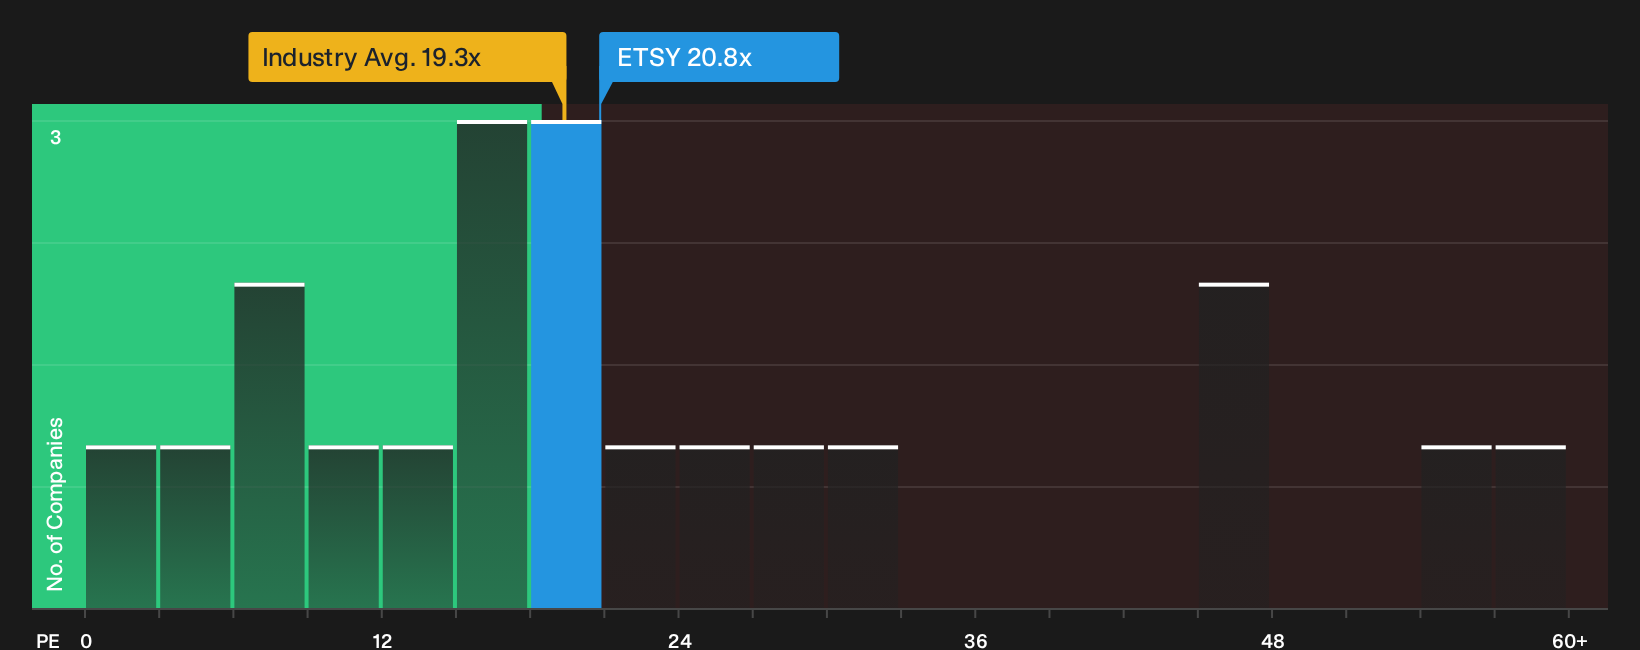
The P/E ratio suits Etsy because the marketplace is already earnings positive and investors can tie the share price directly to reported profit. On this measure, Etsy trades on about 20.8x earnings, which is above the 19.3x industry average for multiline retail and well ahead of the 12.1x peer group figure. That gap suggests the market is willing to ascribe a richer tag to each dollar of Etsy's profit than to many comparable platforms.
The fair multiple that blends Etsy's growth profile, margins, market size and risk sits below the current 20.8x, so the stock screens as overvalued on this framework. Despite the stronger Q3 earnings print and higher gross merchandise outlook, the price already reflects a generous earnings tag relative to what similar businesses command. If you hold or are considering Etsy, the key question is whether its earnings power and competitive position feel strong enough to justify paying that richer P/E today. Explore the numbers behind Etsy's P/E valuation.
The Etsy Narrative: What Would Justify Today's Price?
Etsy's valuation puzzle really comes down to the story investors are telling themselves about tomorrow's earnings profile, which is where Simply Wall St Narratives come in on the Community page. Each one connects its implied number to a specific path for Etsy's growth, profitability and risk, giving you a concrete set of assumptions you can track and revisit as new information shows up in the quarterly results and broader market data.
Community views on Etsy are split between those who think the marketplace improvements leave more headroom in the story and those who see the recent rebound as already generous.
Bull case: roughly fairly valued
"The current valuation implies that the market is not fully pricing in this narrative."
Discover why this Narrative puts Etsy at roughly fairly valued.
Bear case: 42% overvalued
"Etsy (NASDAQ: ETSY) occupies a rare position in e-commerce."
Explore why this Narrative puts Etsy at 42% overvalued.
The share price is only one side of the Etsy story
Price and current earnings tell you where Etsy stands today. However, professional forecasts a few years out offer a different lens on what the business could be earning relative to this valuation. Explore where analysts expect Etsy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com