


- SK hynix (NasdaqGS:SKHY) reported record Q3 revenue and profit, marking its strongest quarter on record.
- Management projected that memory chip shortages could persist through 2030, pointing to tight supply conditions over an extended period.
- The firm disclosed new long-term agreements to supply AI-focused memory chips to key hyperscale and data center customers.
- These record Q3 results and long-dated AI memory deals are only part of SK hynix's current story. Take a look at 2 warning signs (1 major) we have identified for SK hynix.
This kind of AI hardware exposure is not unique to SK hynix, so it is worth scanning a broader peer group through 54 AI infrastructure stocks.
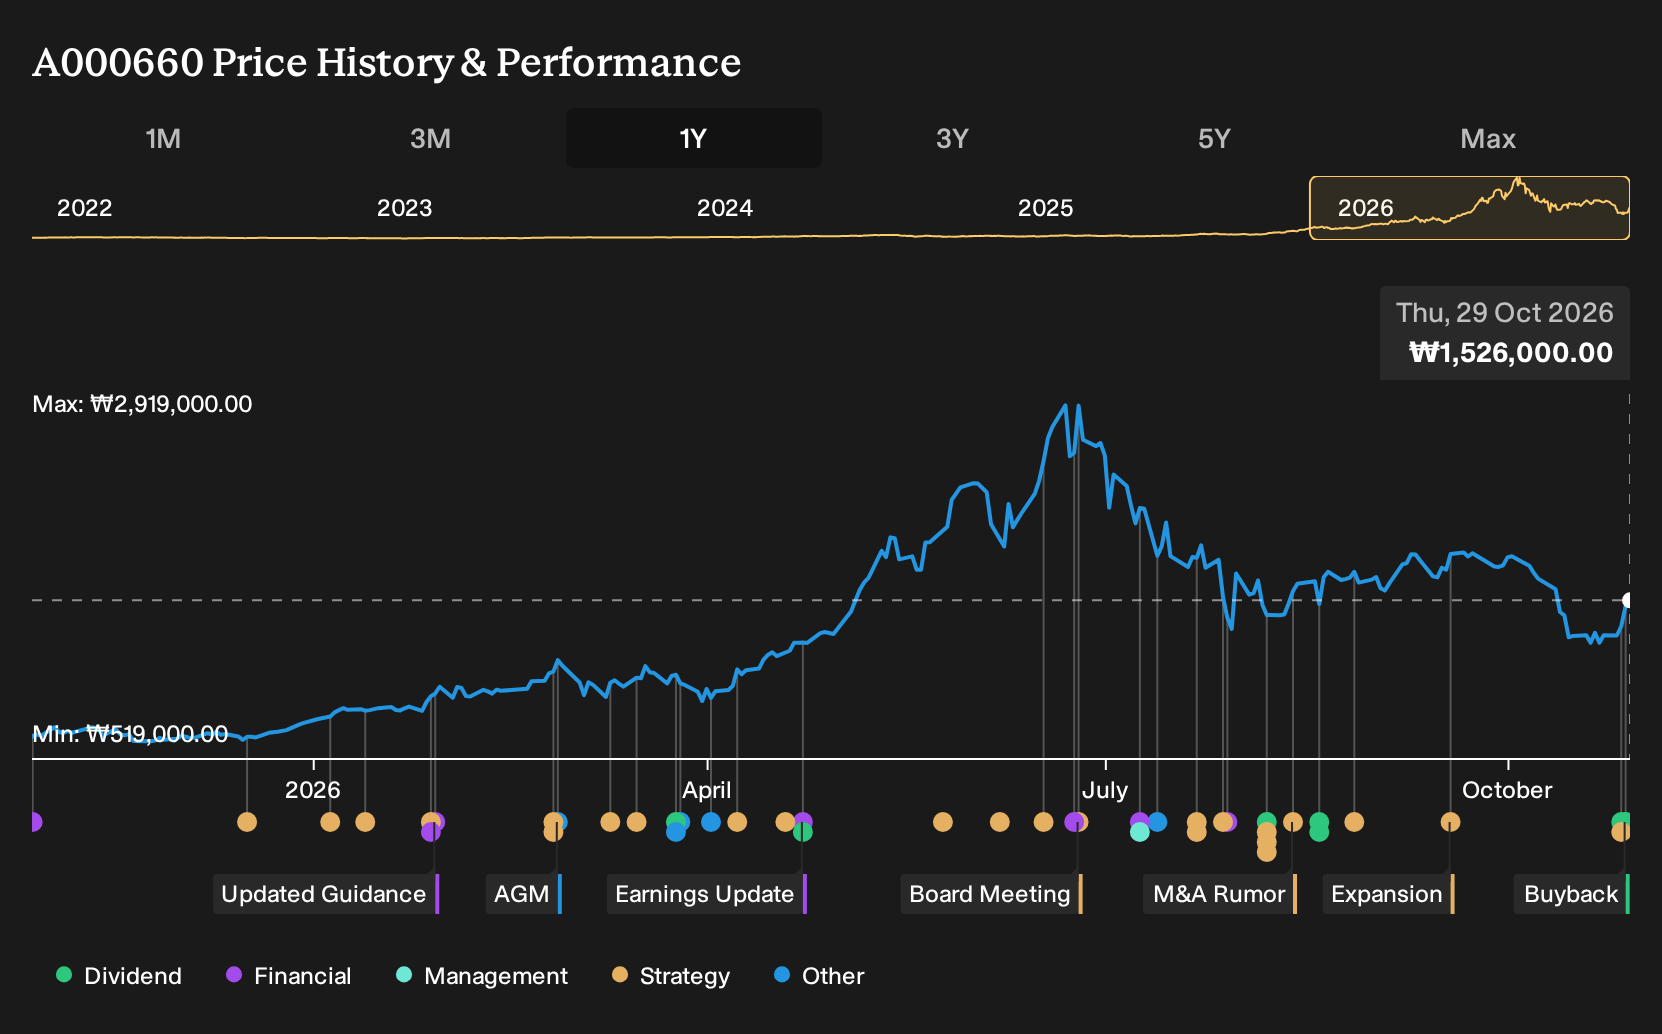
SK hynix develops and sells memory and other semiconductor devices globally, serving customers across Asia, the US, Europe, and other regions that are scaling AI and data center infrastructure. The scale of that footprint matters when you think about how long-term chip supply agreements might feed into its future order visibility.
See which insiders are buying and selling SK hynix following this latest news.
What do record Q3 numbers actually tell you about SK hynix right now?
The headline is size. SK hynix crossed 100 trillion won in quarterly revenue with operating profit up more than 6x year on year and an 80% operating margin, driven by AI data center memory demand. For investors, that puts current earnings strength and AI exposure at the center of the story rather than on the fringes.
How do long term AI memory deals and the 2030 shortage view feed into sentiment?
Multi year HBM supply agreements and management’s view of tight memory conditions through 2030 signal that key customers are locking in product early. That supports the idea of more visible demand for SK hynix while also reminding you that the stock has been volatile and that reported earnings quality includes a high level of non cash items.
What is the clearest thing to watch next to see if this AI momentum is real for SK hynix?
The critical checkpoint is whether HBM4 actually becomes a mainstream revenue driver from Q4 as management flagged. Watch upcoming quarterly filings for the share of sales tied to HBM products and any update to the 2027 capital expenditure plan that would confirm customers are following through on these commitments.
The unanswered SK hynix question that comes down to hard cash
Quarterly headlines only go so far. There is also a calculation that takes SK hynix's cash generation and turns it into an implied business value that can be compared directly with today's share price. Find out exactly what SK hynix is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com