


AI infrastructure is soaking up cash as quickly as companies can build data centers, and the latest updates from Amazon, Intel and hardware makers have reminded investors that even market leaders can feel the strain. That pressure also creates mispricings. When sentiment cools, solid businesses linked to cloud and AI themes can be marked down along with weaker peers. This article walks through three stocks from our high-quality, cash-generative AI beneficiaries screener that look especially exposed to the current news cycle and explains what informed investors might want to watch next.
The three stocks below are a starting sample from this theme, and the full screen surfaced 36 more large, cash-focused AI infrastructure companies with equally compelling narratives that are not covered here. If you want to move straight from ideas to your own short list, you can analyze and filter the full set of potential high conviction plays inside the High-Quality, Cash-Generative AI Beneficiaries screener.
GlobalWafers (TPEX:6488)
GlobalWafers plugs directly into the AI infrastructure story, supplying the silicon base that sits under advanced chips and data center hardware, and its scale and balance sheet make it a useful reference point when investors are sorting durable beneficiaries from more fragile hardware plays.
GlobalWafers manufactures semiconductor ingots and wafers for chipmakers worldwide, with the Semiconductor Business Group generating about NT$58.0b of its roughly NT$58.2b segment revenue and a small Renewable Energy Division contributing under NT$1b, and the stock carries a market value of about NT$389.2b.
"GlobalWafers is moving its global capacity buildout from construction into qualification and ramp at new 12 inch fabs in Texas, Italy and Japan. If energy, freight and key raw material costs such as gallium continue to rise while GlobalWafers can only gradually adjust contract and spot pricing, the company may have to absorb a larger share of inflationary inputs, which would pressure gross margin, operating margin and net profit even if wafer shipments remain healthy."
What happens when that quiet but growing influence on future cost discipline and pricing power finally shows up in reported profitability will matter a lot.
That inflection point is exactly what the full narrative for GlobalWafers unpacks, explaining how rising input costs, contract structures, and new fabs could influence GlobalWafers' long-run earnings power.

Tekscend Photomask (TSE:429A)
Tekscend Photomask supplies high precision photomasks for chipmakers worldwide, feeding into the AI and data center buildout from an upstream position in the semiconductor chain. It generates about ¥134,018 million from its photomask related business and the stock is valued at roughly ¥322.4b.
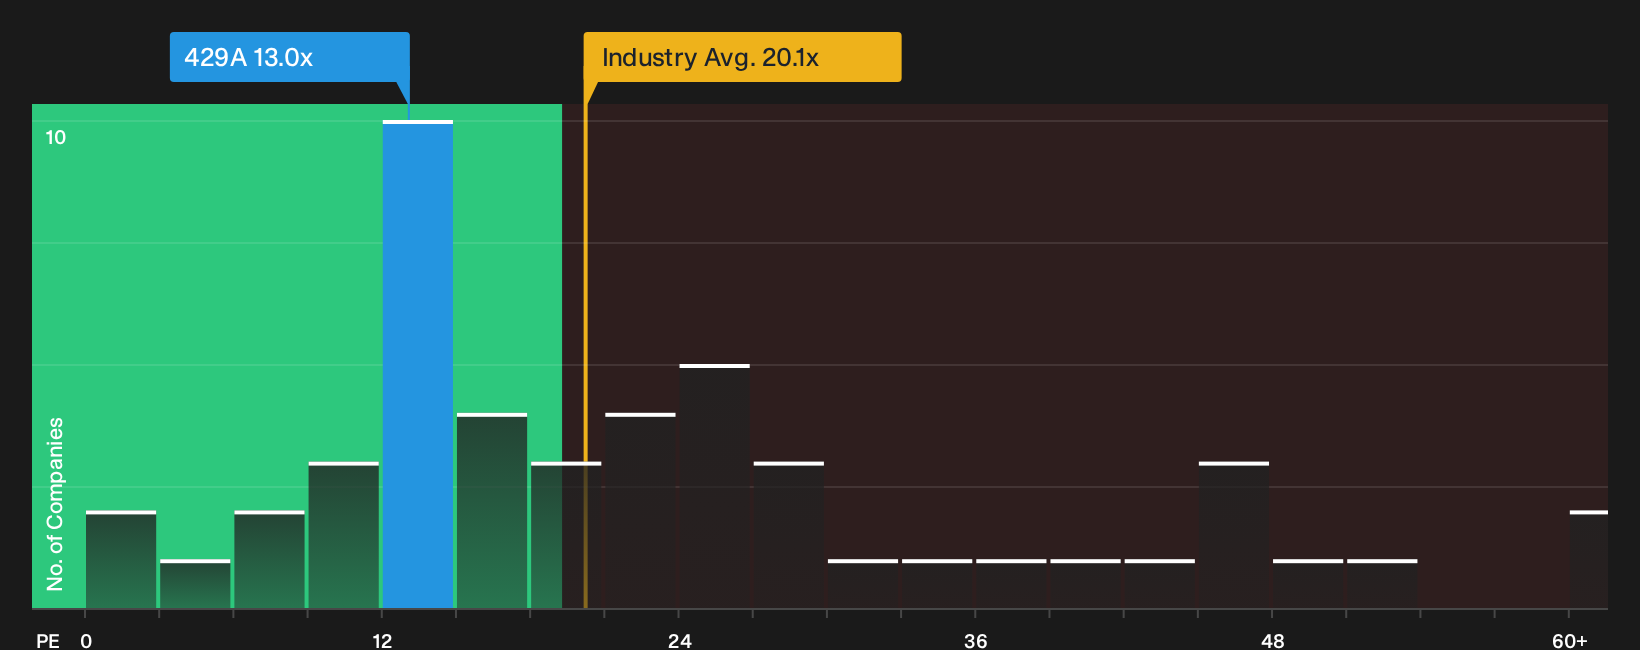
Tekscend Photomask gives you direct exposure to AI chip manufacturing without tying you to cloud operators that are spending heavily on data centers and taking on more debt. Its strong margins, solid Q1 2026 profitability and a P/E near 13x highlight its cash generation profile, assuming that at least one currently unseen pressure on future demand ultimately proves supportive for investors.
Those pressures can easily mask the full picture, so check the analysis report for Tekscend Photomask to see where Tekscend Photomask’s cash generation and valuation could be decoupling from sentiment.
Parade Technologies (TPEX:4966)
Parade Technologies gives you a cleaner way to tap into the AI infrastructure theme, supplying high speed interface and display chips that plug into data center connectivity, high end notebooks and advanced displays without the heavy factory spending that is pressuring many hardware giants.
Parade Technologies designs high speed interface and display processing chips for computers, consumer electronics and panels across Asia and global markets, operating on a fabless model that fits the AI infrastructure theme, and it carries a market value of about NT$37.7b.
"Rapid adoption of Parade Technologies TTED single chip solutions in notebooks, with TT including TTED rising from around 10% of revenue in Q1 2026 to close to 15% in Q2 2026 and shipments already running much higher than the original plan of above 5 million units for 2026, points to higher silicon content per device that can support revenue and margin mix over time."
What really matters from here is how one less visible shift in its AI oriented connectivity pipeline ultimately filters through to earnings quality.
That earnings filter is exactly where the full narrative for Parade Technologies cuts through, mapping how Parade Technologies’ AI connectivity pipeline could reshape its risk reward profile as demand patterns evolve.

Seeking Alternatives Before Momentum Flies
Fresh ideas tend to move first, and late money often ends up chasing someone else's breakout while prices are already moving sharply higher. Look for what is still under the radar and consider acting before it becomes crowded.
- Identify cash rich businesses that may be quietly building momentum before income-focused investors notice by running the 228 dividend fortresses and concentrating on payouts that the market may not have fully priced in yet.
- Monitor fast moving opportunities in smaller AI companies by reviewing the curated list of 153 AI small caps, which may draw additional attention over time.
- Search for resilient balance sheets while they may still trade on earlier assumptions by using the targeted list of solid balance sheet and fundamentals (207 results) to highlight financially robust candidates at an earlier stage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com