


CCC Intelligent Solutions Holdings came into this Q3 2026 report priced for perfection, trading on a rich 60.9x trailing P/E after a strong 90 day run. The stock barely twitched, up just 0.1% on the day, yet the headline result was far more lively than the share move suggests.
Revenue reached US$294.1 million and basic earnings per share landed at US$0.05, extending the shift to consistent profitability. For a software platform often treated as a steady compounder, that kind of earnings traction, alongside a valuation still below one discounted cash flow estimate, presents a story that is more interesting than the flat chart implies.
Love CCC Intelligent Solutions Holdings' steady profitability but concerned about paying a 60.9x trailing P/E for it? Compare this setup with a curated group of stocks that pair quality earnings profiles with more grounded valuations in our 30 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$294.1 million vs. US$267.1 million (up about 10.1%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$30.2 million vs. a loss of US$2.0 million (swing back to profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.0525 vs. a loss of US$0.0031 per share (returned to positive earnings per share)
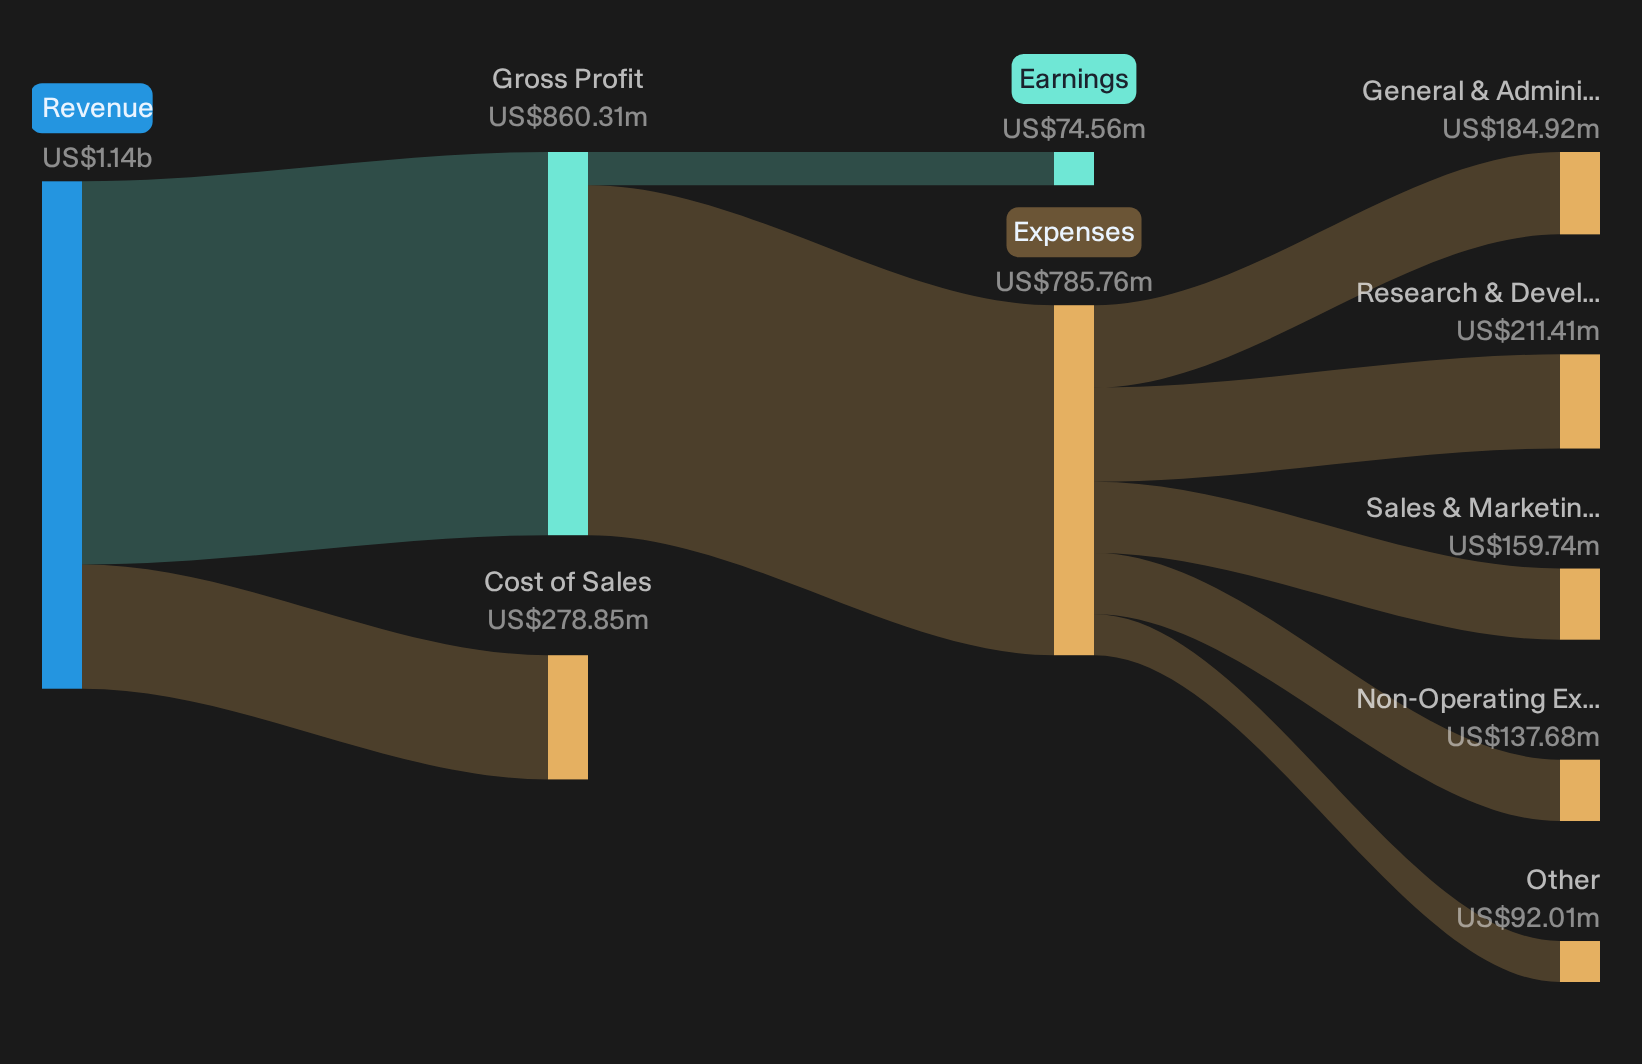
- Trailing Twelve Month Revenue (TTM, Q3 2026 vs Q3 2025): US$1.14b vs. US$1.03b (up about 11.1%)
Earnings flipped positive, but interest coverage still looks tight. Ask Charlie which risk matters most for CCC Intelligent Solutions.
CCC bullish thesis: AI traction meets profit milestones
Fans of CCC Intelligent Solutions argue that expanding AI across a complex claims ecosystem can support richer usage and healthy software profitability.
"The main factor that has to go right is that CCC Intelligent Solutions Holdings continues to convert rising workflow complexity and its broad insurer and repair ecosystem into deeper AI and cross sell penetration without eroding software margins."
Q3 shows this ambition holding up. AI and cross sell had previously contributed meaningfully to growth, and the latest quarter delivered US$294.1 million of revenue with US$30.2 million of adjusted profit and positive EPS, so higher product intensity is arriving without evident margin damage.
CCC bearish thesis: AI data and execution risks linger
On the risk side, the concern is that AI rollout stumbles or legal and leadership issues chip away at the CCC Intelligent Solutions story.
"The company had previously faced delays in implementation and revenue recognition for EvolutionIQ solutions and has since moved ahead with using that technology in MedHub for complex auto medical claims. However, if broader rollout or adoption across casualty, disability and related areas is slower than planned, the expected incremental revenue contribution and margin expansion from these AI investments could fall short."
Q3 profitability and a return to positive EPS indicate no clear earnings drag from these rollouts yet, although the class action over data use means the AI roadmap still carries legal and operational uncertainty.
One Narrative disagrees with today's price. → See where this Narrative says CCC Intelligent Solutions Holdings should trade.
Hunt Quiet Mispricings Now
CCC Intelligent Solutions Holdings just showed how a busy earnings print can leave the share price almost unchanged. The potential opportunity is in stocks that may trade below what their fundamentals suggest.
- Company 1 - 21% below our estimate - uses surgical robotics and higher acuity procedures to deepen ties with hospitals adopting technology-driven operating rooms.
- Company 2 - 46% below our estimate - turns an AI recommendation engine into essential infrastructure that shapes what content appears and how products are positioned.
- Company 3 - 26% below our estimate - scales a low-cost digital banking model as customer adoption and efficiency improvements redefine a modern retail lender.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com