


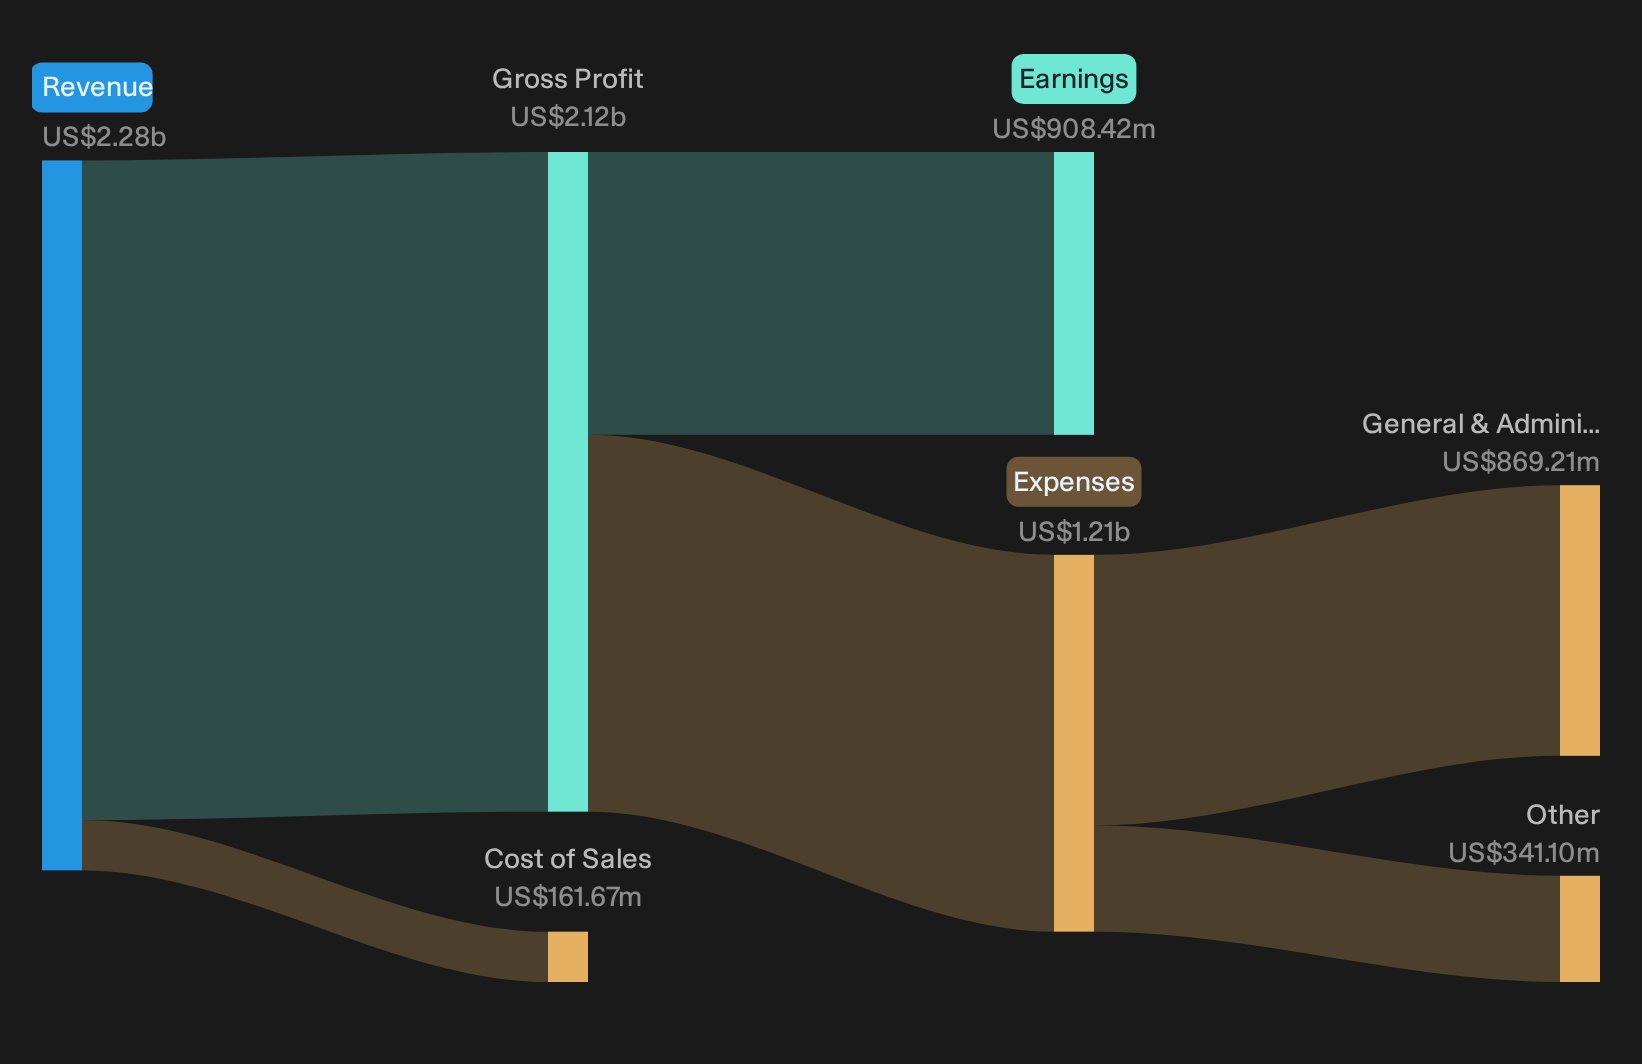
Tradeweb Markets entered its Q3 2026 report on a strong multi‑month run, with the share price up about 18% over the past quarter, yet the stock slipped 0.8% to US$118.88 in the first full day after earnings. That pullback jars against what the numbers actually show. Revenue reached US$584.0 million for the quarter and basic earnings per share came in at US$0.94, both anchored by firm profitability. The real tension for investors now sits in the gap between that solid profit engine and a valuation that already bakes in a rich future.
Love Tradeweb Markets' solid earnings print but concerned the valuation already assumes a lot of good news? You can run a quick comparison against a broader list of quality names using our 30 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$584.0 million vs. US$508.1 million (up about 15%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$197.5 million vs. US$185.5 million (up about 6%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.94 vs. US$0.87 (up about 9%)
- Adjusted EBITDA Margin (Q3 2026 vs prior period): 54.5% vs. just under 54% (slightly higher profitability on an adjusted basis)
Earnings tell you how profitable Tradeweb Markets looks on paper, but cash flows show how much money is actually coming through the door and available to support that performance. When you look at Tradeweb Markets' cash flows alone, the stock could be a hefty 42% overvalued.
Evaluating Tradeweb’s High‑Volume Automation Story
Supporters argue that Tradeweb Markets can turn automation, data and global reach into a self reinforcing engine for revenue and cash generation.
"The main thing that has to go right is that Tradeweb Markets turns rising electronic market share, international growth and AI driven data investments into revenue that more than offsets lower fees per million and higher technology and occupancy expenses."
Q3 progress lines up with that ambition. Revenue grew faster than adjusted expenses, so the adjusted EBITDA margin edged higher even as technology and occupancy costs rose sharply. International turnover expanded at a quicker clip than the group and market share in swaps, Treasuries and credit increased, which suggests volume and mix are, for now, outrunning fee compression and heavier investment.
The price and this Narrative do not agree. → Uncover what this Narrative says Tradeweb Markets is actually worth.
Tradeweb Margins Hold, But Cost Risks Build
Bears argue that Tradeweb Markets is on a path where rising tech and occupancy costs eventually bite into profitability if revenue momentum slows.
"While Tradeweb Markets is expanding AI driven tools such as TARA, AiEX and data distribution partnerships, the 38.9% rise in technology and communication costs tied to these projects exposes the company to the risk that customer adoption or pricing does not fully offset higher fixed and variable spend."
This quarter, that concern only partly shows up. Technology and communication outlays rose roughly 32% and occupancy costs climbed about 23%. However, adjusted expenses grew slightly slower than revenue and the adjusted EBITDA margin inched higher to 54.5%. The risk around under earning these investments is intact, but not confirmed by Q3 delivery.
Hunt Mispriced Earnings Stories
Tradeweb Markets just showed how a solid profit engine can align with a cautious share price reaction. The real opportunity could be recognizing stocks that appear mispriced before the wider market reassesses them.
- Company 1 - 25% below our estimate - uses AI centric networking and data center gear to convert hardware buyers into longer service relationships.
- Company 2 - 32% below our estimate - supplies GPUs and an integrated software stack so large data center customers can scale AI oriented computing.
- Company 3 - 40% below our estimate - expands coconut based drinks into mainstream shelves while adding private label supply for retailers.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com