


Why Omnicom Group Stock Is Back in Focus
Omnicom Group (OMC) has jumped onto investors’ radar after a busy October, combining fresh quarterly results, an expanded relationship with The Coca-Cola Company in North America and continued share repurchases.
Those headlines landed alongside a 1-day share price return of 4.11%, which pushed Omnicom Group to US$80.97, capping a 30-day share price gain of 9.21% even though the year-to-date share price return is slightly down 0.43%. With a 1-year total shareholder return of 12.36% and a 5-year total shareholder return of 43.13%, the recent move suggests momentum has been rebuilding as investors weigh the Coca-Cola mandate, strong quarterly earnings and an active buyback program against the stock’s longer track record.
Scan how Omnicom Group compares with a curated set of peers by reviewing the list of solid balance sheet and fundamentals (23 results)
.After a sharp October move, new Coca-Cola work in North America and an active buyback program, Omnicom Group looks very different at US$80.97 than it did a month ago. Does the current valuation still skew the risk reward toward buyers?
Most Popular Narrative: 20.6% Undervalued
On the most followed view, Omnicom Group’s fair value sits at $102, comfortably above the last close at $80.97. This frames the recent rally as only part of the story.
The expanded cost reduction and portfolio pruning program, which now targets disposals of about US$3.5b to US$3.6b of largely lower growth revenue and gross cost synergies of US$1.5b by mid 2028, is designed to support higher Core Operations margins and EBITA growth as remaining businesses scale.
See why 42 investors see Omnicom Group as 21% undervalued.
That narrative leans on a relatively high 11.04% discount rate, which incorporates meaningful execution and financing risk while still pointing to a fair value above the current share price. It also assumes Omnicom Group can reach a 9.9% profit margin and support a future P/E of 18.1x, which is lower than the current P/E for the wider US Media industry at 23.4x, so the implied outcome does not require a premium multiple.
Pulling these inputs together, the narrative presents Omnicom Group as undervalued on cash flow and earnings potential rather than cheap on today’s reported net income, especially given the impact of one off items on recent results. For readers, the key question is whether that margin rebuild, portfolio pruning and capital return plan looks achievable on your own assumptions, because the 20.6% gap to fair value only holds if those steps stay on track.
Result: Fair Value of $102 (UNDERVALUED)
Still, Omnicom Group’s thesis depends on cost cuts and divestments landing as planned, as well as on softer regions like Asia Pacific and the Middle East recovering.
Find out about the key risks to this Omnicom Group narrative.
Another View: What Omnicom Group’s P/E Is Telling You
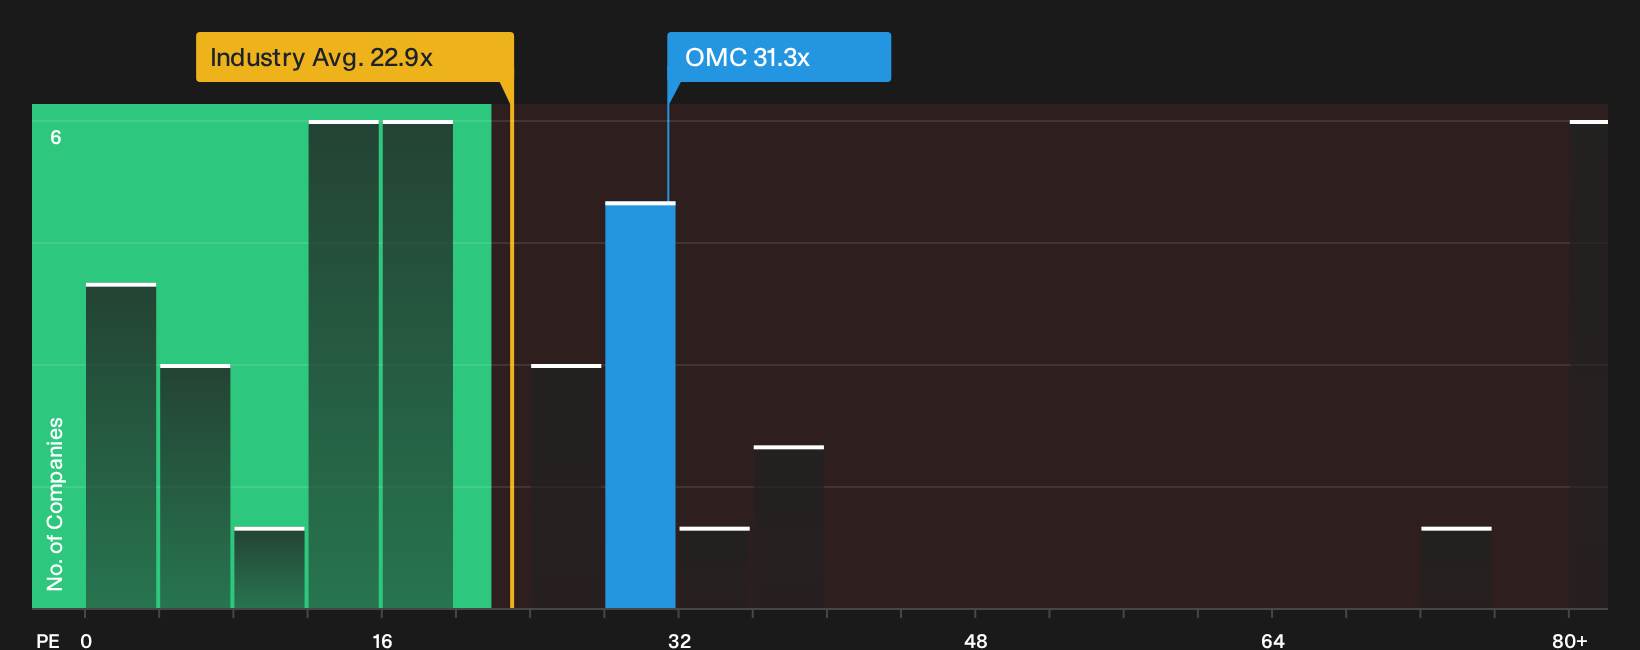
That 20.6% gap to a $102 fair value presents Omnicom Group as attractive on future cash flows. The P/E ratio tells a sharper story. At 31.3x earnings, the shares trade well above the US Media industry on 23.5x and above a fair ratio of 25.1x that the market could eventually lean toward.
This richer multiple also sits higher than a 22.4x peer average, which points to less margin for error if earnings or integration progress disappoint. For investors weighing the upbeat fair value against a premium current P/E, the key question is which signal feels more credible for your time horizon and risk tolerance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Balancing the mix of enthusiasm and caution around Omnicom Group? Take timely action, review the underlying data, and evaluate the 3 key rewards and 5 important warning signs.
Looking for more ideas beyond Omnicom Group?
If Omnicom Group has sharpened your focus, do not stop here. Broaden your watchlist with data driven ideas tailored to different styles and risk levels.
- Target potential bargains backed by strong fundamentals by scanning our universe of 30 high quality undervalued stocks that may align with your preferred margin of safety.
- Prioritise resilience and capital strength by filtering for a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio through different market conditions.
- Get ahead of the crowd by reviewing 18 high quality undiscovered gems before they land on everyone else’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com