


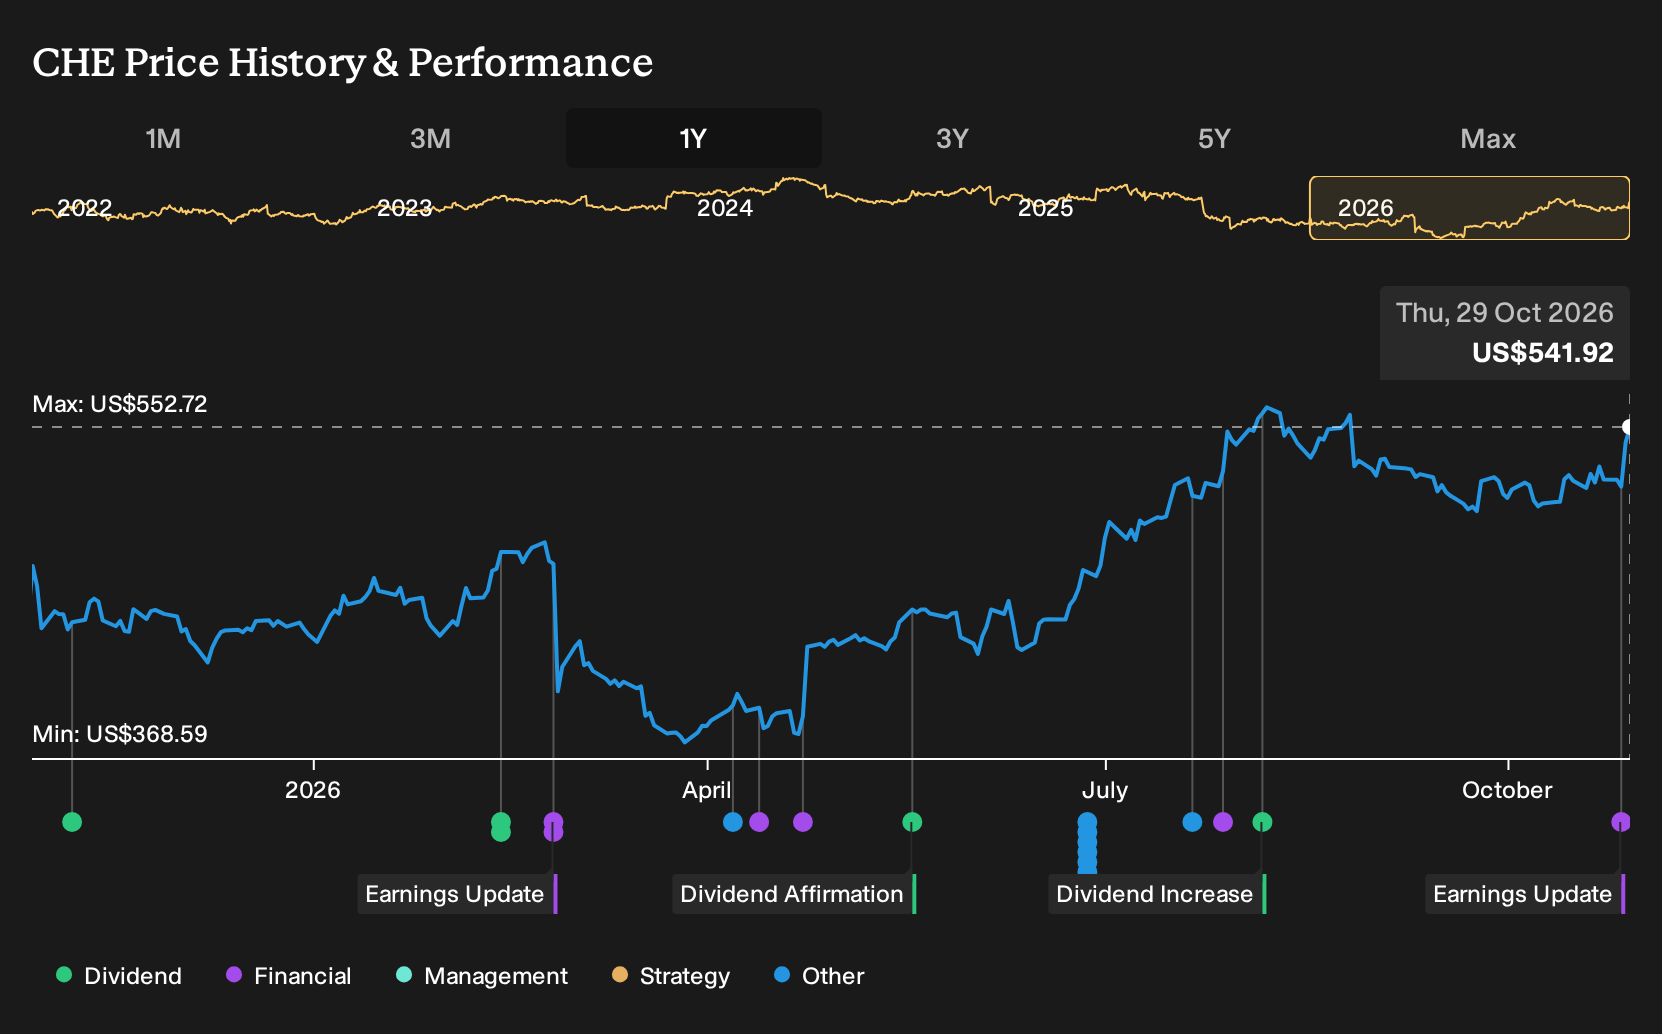
- Chemed Corporation reported third quarter 2026 net income of US$71.65 million and basic earnings per share from continuing operations of US$5.49, with both quarterly and nine month results above the prior year.
- The latest figures highlight how VITAS hospice care and Roto Rooter plumbing services are both contributing to earnings, while cost pressures in areas like marketing and fuel still influence how much of that revenue converts into profit.
- This article reviews how Chemed's investment narrative is affected by this earnings beat, with particular attention to the stronger VITAS hospice performance.
Scan how Chemed’s earnings beat compares with other operators by reviewing our hand picked 36 healthcare AI stocks that blend healthcare exposure with AI driven business models.
Chemed Investment Narrative Recap
Owning Chemed means believing VITAS can keep converting hospice demand into steady earnings, while Roto Rooter manages higher marketing and fuel costs without squeezing profits too much. The latest quarter supports that view. Net income of US$71.65 million and basic EPS of US$5.49 show both arms of the group are still pulling their weight.
The near term swing factor is whether VITAS can hold its admission strength and cost discipline while Medicare and Medicaid rules stay manageable. The biggest risk is that Roto Rooter customer acquisition costs stay structurally high, which could cap margin improvement even as franchise reacquisitions add revenue.
The most relevant recent development is Chemed’s third quarter 2026 report, which showed net income of US$71.65 million versus US$64.24 million a year earlier and nine month net income of US$205.65 million compared with US$188.49 million. Basic EPS from continuing operations reached US$5.49 in the quarter and US$15.46 year to date.
Those numbers matter because they give investors fresh evidence on the key catalysts and risks already in focus. VITAS is delivering higher earnings while working within reimbursement constraints, and Roto Rooter is absorbing margin pressure as Chemed acquires more franchises, a process that could influence both near term profitability and longer term scale benefits.
What The Chemed Forecasts Assume
Chemed's narrative projects forecast revenue of US$3.2b and earnings of US$401.0 million by 2029, based on analysts assuming 7.0% yearly revenue growth and an earnings increase of about US$126.0 million from current earnings of US$275.0 million.
Uncover why Chemed's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$592.60 to US$731.30, so retail views on Chemed’s worth already stretch across a wide band. Set that beside reimbursement risk at VITAS and elevated lead costs at Roto Rooter, and you can see why opinions differ. It may be useful to explore several viewpoints before drawing conclusions.
Explore 2 other Chemed fair value estimates, including one that suggests it could be worth just $592.60.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Chemed research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chemed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Chemed's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chemed?
Once you have a view on Chemed, it can help to compare it with other opportunities that fit different risk and return profiles across the market.
- For investors who want stability first, review a list of solid balance sheet and fundamentals (23 results) that may better match a preference for robust financial footing.
- If capital preservation matters as much as upside, consider a 30 resilient stocks with low risk scores that screens for businesses with more resilient profiles.
- When you are hunting for underfollowed opportunities, scan a 18 high quality undiscovered gems that combine healthy fundamentals with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com