


Texas Pacific Land has delivered strong long term share price gains, which naturally puts the spotlight on whether its current market value is still supported by the earnings power of the business. With the stock now trading around US$327.96, the key issue is how that price lines up with what the company actually earns today.
- Texas Pacific Land has returned about 152.7% over the past 5 years, which makes the question of what investors are paying for its earnings especially important.
- The business generates its results from energy related assets and royalty income, so any change in commodity pricing, production volumes or operating efficiency can feed directly into profit levels and reshape what looks reasonable for an earnings based valuation.
- Your read on Texas Pacific Land is one view; the desks covering it have another. See what analysts think Texas Pacific Land's shares could be worth.
The issue now is whether Texas Pacific Land's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want more ideas that start with the same question you are asking about Texas Pacific Land, a focused stock screen built around 30 high quality undervalued stocks can be a useful next step in your research.
Is Texas Pacific Land Getting Expensive on Earnings?
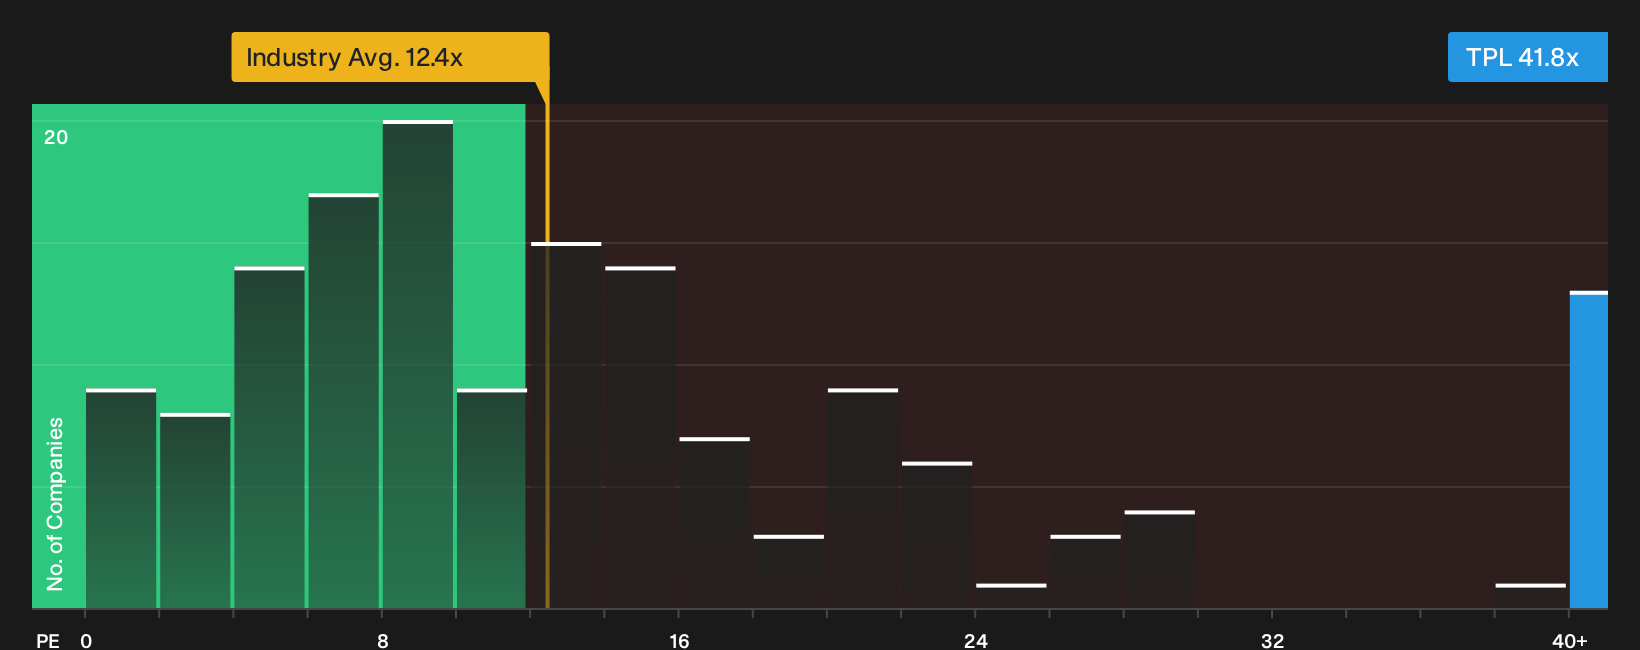
The P/E ratio suits Texas Pacific Land because most of its value story ultimately comes back to the profits it earns on its royalty and energy related assets. At a current P/E of about 41.8x, the stock trades at a much richer earnings multiple than the Oil and Gas sector average of roughly 12.4x and the broader peer group around 12.1x.
The Fair Ratio, which looks at what a more tailored P/E might be given Texas Pacific Land's business mix, size and risk profile, points to a lower level than where the shares currently change hands. That gap suggests investors are paying a premium price for each dollar of current earnings relative to what this framework implies as a more grounded range. For anyone assessing Texas Pacific Land today, the key question is whether the quality and durability of its royalty income stream justify that richer P/E, or whether it leaves less room for error at the current share price. Explore the numbers behind Texas Pacific Land's P/E valuation.
The Texas Pacific Land Narrative: What Would Justify Today's Price?
Narratives on Texas Pacific Land pick up where this valuation puzzle leaves off, by spelling out which combinations of future growth, profitability and earnings power would need to hold for the current price to look meaningfully higher or lower. Each one turns fair value into a clear, trackable hypothesis about Texas Pacific Land's business, so you can see how that view holds up over time, and they sit on Simply Wall St's Community page.
Texas Pacific Land splits opinion, with one camp arguing the current price underplays its assets while another sees expectations already stretched.
Bull case: 26% undervalued
"Diversified revenue streams, stable royalty income, scalable operations, and infrastructure initiatives position the company for resilient earnings, reduced volatility, and long-term growth potential…"
Discover why this Narrative puts Texas Pacific Land at 26% undervalued.
Bear case: 33% overvalued
"The numbers and recent research cuts to price targets into the US$360s, along with commentary that the stock appears expensive, imply a share price that already incorporates very optimistic assumptions for Texas Pacific Land and leaves limited room for disappointment…"
Explore why this Narrative puts Texas Pacific Land at 33% overvalued.
One more Texas Pacific Land check before you move on
Price and earnings only tell part of the story, because Texas Pacific Land also triggers specific risk checks that investors often prefer to weigh carefully before getting comfortable with any valuation. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com