


Snap has seen its share price fall sharply over the past few years, which puts fresh focus on a basic question for investors who still follow the stock. Is the current US$5.68 price tag adequately supported by the revenue that Snap is generating today and what the market expects from its sales in the future?
- Over the past 5 years the share price has dropped 89.1%, which puts the entire Snap equity story under scrutiny through the lens of what its sales are actually worth to the market.
- The move of Snapchat’s first product manager to Elon Musk’s X may influence how investors think about Snap’s ability to convert its user base and product roadmap into sustainable sales growth and cash generation.
- Your read on Snap is one view; the desks covering it have another. See what analysts think Snap's shares could be worth.
For investors, the debate is whether Snap’s current valuation is justified by its sales given this share price history and shifting expectations for the business.
If you are questioning whether Snap’s US$5.68 share price lines up with its sales, it can help to compare that same valuation puzzle across 30 high quality undervalued stocks.
Does Snap Look Undervalued on Sales?
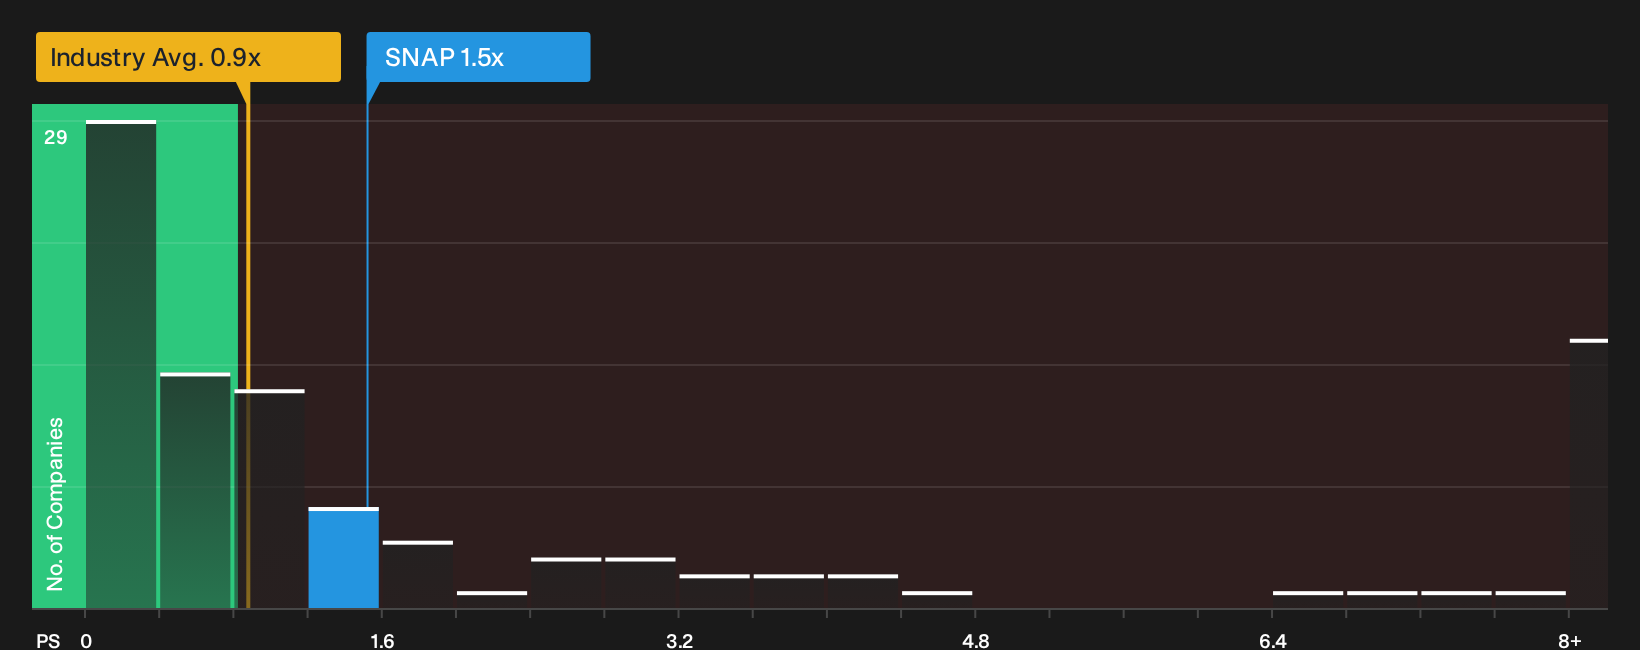
P/S fits Snap reasonably well because investors still anchor heavily on what each dollar of revenue is worth while the business model matures. At the current price, Snap trades on about 1.5x P/S, which is below the Interactive Media and Services industry average of around 0.9x and below the peer group at roughly 2.0x. That puts the stock in a middle ground where the market is not paying up for revenue like faster growing peers, yet is still valuing it more highly than the sector overall.
The Fair Ratio model, which adjusts the benchmark multiple for Snap’s margins, risk profile and size, points to a higher P/S than where the shares change hands today, so the stock screens as undervalued on this yardstick. Because Snapchat’s first product manager has moved to Elon Musk’s X, some investors may question product execution, yet the current P/S still prices the company at a discount to what this framework suggests its revenue could justify. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Snap Narratives on Simply Wall St pick up where the valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price.
Each scenario lays out the moving pieces behind its view of fair value rather than relying on a single multiple or model output. This means you can line those assumptions up against Snap's reported results as they come through. Narratives sit on Simply Wall St's Community page and give you a structured way to test how your own expectations compare with those embedded in the market.
Community views on Snap split between those who see early AR and subscription progress as underappreciated and those who think execution and youth risk are already fully priced in.
Bull case: 23% undervalued
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base..."
Discover why this Narrative puts Snap at 23% undervalued.
Bear case: 14% overvalued
"The numbers imply that Snap’s share price already reflects successful execution on AI, subscriptions, hardware and cost restructuring..."
Explore why this Narrative puts Snap at 14% overvalued.
One more Snap check that belongs beside the price tag
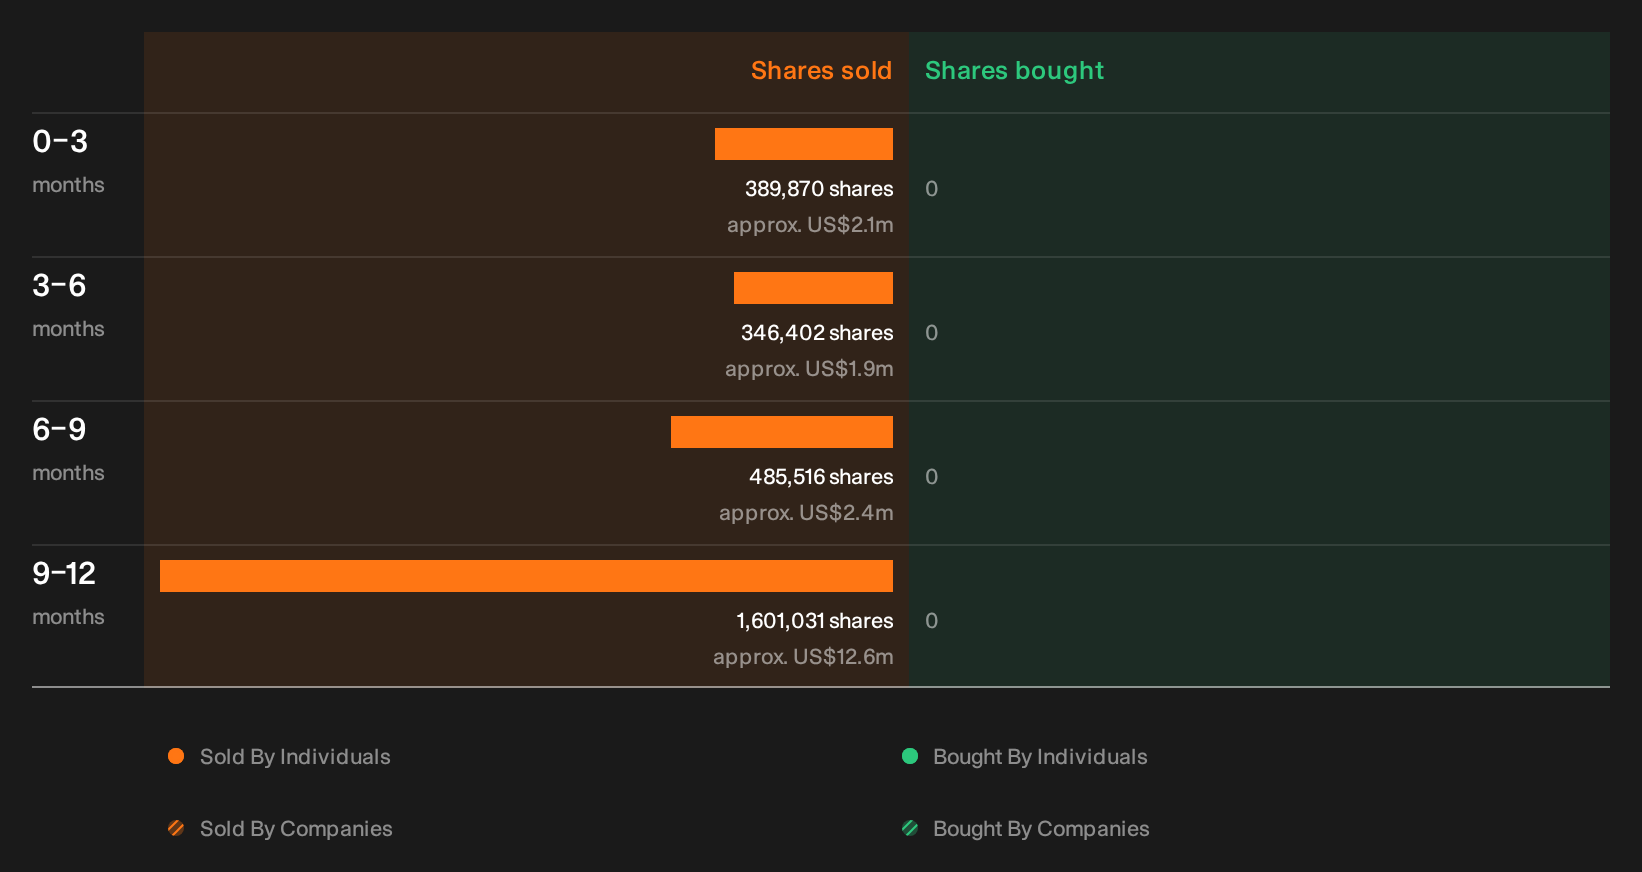
Before you move on, it is worth knowing that Simply Wall St’s checklist has picked up recent trading by people inside Snap, and the identities, scale and possible read through of those moves are all there for you to review. See the recent insider selling flagged for Snap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com