


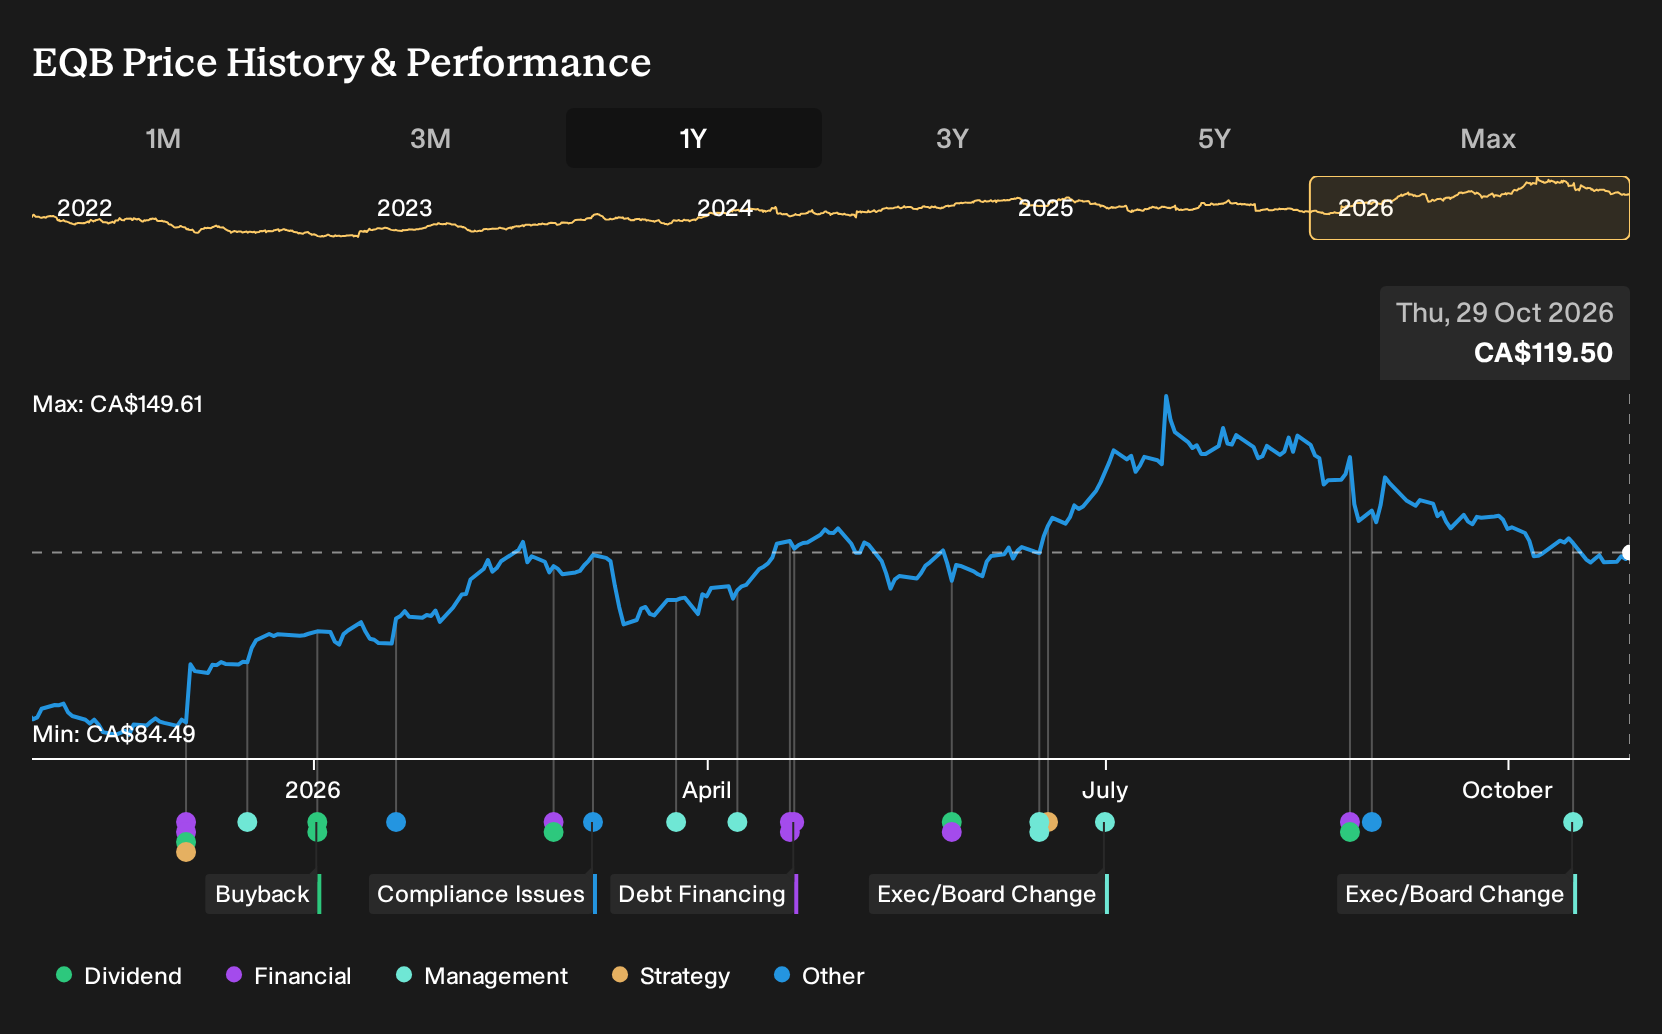
- EQB Inc., through Equitable Bank and Concentra Bank, raised their prime lending rates by 25 basis points to 4.70% from 4.45%, following the Bank of Canada’s move, with changes effective October 29, 2026.
- This prime rate shift directly affects EQB's lending spreads and the way it monetizes the enlarged PC Financial and Loblaw linked customer base through both interest and fee income.
- This development will be monitored to see how EQB's investment narrative evolves as its higher prime rate interacts with the PC Financial growth opportunity.
Scan how EQB’s move on rates and risk oversight compares with other resilient lenders by reviewing our hand picked 8 resilient stocks with low risk scores in the current interest rate cycle.
EQB Investment Narrative Recap
To own EQB, you need to believe the enlarged PC Financial and Loblaw linked platform can turn a wider customer base into durable deposit, card and fee income while credit costs stay contained. The prime rate increase changes pricing mechanics, but the near term catalyst still sits in how effectively EQB monetizes those 4 million PC Financial customers and the broader 18 million member ecosystem.
The biggest immediate risk remains credit quality and capital tied up in impaired mortgages and commercial loans, especially after the recent CA$127.3 million loss tied to provisions. The latest rate move does not materially change that. It simply adds another variable to watch as higher pricing meets already elevated provisions and longer collection timelines.
The board change around risk oversight is the clearest link to what matters next for EQB. Vivian Abdelmessih joining as Chair of the Risk & Capital Committee brings a deep focus on enterprise risk, regulatory compliance and capital structure, at the same time the bank is balancing higher bad loans, a low 45% allowance for bad loans and court driven delays in collections.
For you as a shareholder, the interest rests in execution. EQB is working to integrate PC Financial, manage a growing credit card and mortgage book and keep its CET1 ratio supportive of future projects while still paying a dividend that is not well covered today. Strong risk and capital governance will likely be central to whether those growth catalysts translate into more stable earnings.
EQB's current analyst story points to CA$3.0b in revenue and CA$815.1m in earnings by 2029. This aligns with a forecast 50.6% yearly revenue growth rate and implies earnings would need to rise by about CA$826m from the current loss of CA$11.3m reported today.
Uncover why EQB's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some analysts focus less on credit risk and more on EQB’s revenue potential from PC Financial. Before this rate move and board change, the most optimistic group was working off forecasts of about CA$3.0b in revenue and CA$759.1m in earnings by 2029. You should treat those upbeat assumptions as one lens, and compare them with several other views.
Explore another EQB fair value estimate, including one that suggests potential upside of up to 77% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and approach.
- A great starting point for your EQB research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for EQB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EQB's overall financial health at a glance.
Looking for more EQB investment ideas and peers?
If the EQB story has you thinking about portfolio balance, use this moment to widen your lens and scan other stocks that match the kind of risk and return profile you want.
- For investors hunting for value with quality in mind, review a curated set of 4 high quality undervalued stocks that pair stronger balance sheets with discounted prices.
- If steady income is a priority, focus on payout resilience by assessing our hand picked 3 dividend fortresses that combine higher yields with more robust fundamentals.
- When capital preservation ranks high on your checklist, stress test your ideas against a 8 resilient stocks with low risk scores that screens for sturdier financial health and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com