


In October 2026, the European market has been navigating a challenging landscape characterized by heightened inflationary pressures and geopolitical tensions, which have contributed to a decline in key indices such as the STOXX Europe 600. Amid this backdrop, small-cap stocks have gained attention for their potential resilience and growth opportunities, especially when accompanied by insider activity that may signal confidence in their future prospects.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| LSL Property Services | 14.9x | 1.4x | 43.25% | ★★★★★☆ |
| Domino's Pizza Group | 14.6x | 1.2x | 29.27% | ★★★★★☆ |
| Hanza | 27.1x | 1.1x | 38.44% | ★★★★☆☆ |
| Franchise Brands | 27.3x | 2.0x | 47.51% | ★★★★☆☆ |
| Saniona | 8.6x | 3.7x | 20.02% | ★★★★☆☆ |
| Cityvarasto Oyj | 11.3x | 3.7x | 36.08% | ★★★★☆☆ |
| Nyab | 19.5x | 0.9x | 30.29% | ★★★☆☆☆ |
| Cibus Real Estate | 11.4x | 4.8x | -2886.40% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -236.67% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.04% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
AB Dynamics (AIM:ABDP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: AB Dynamics is a company that specializes in providing simulation, testing products, and testing services for the automotive industry, with a market cap of approximately £0.52 billion.
Operations: AB Dynamics generates revenue primarily from Testing Products (£67.80 million), followed by Simulation (£22.30 million) and Testing Services (£15.40 million). The company's gross profit margin has shown an upward trend, reaching 63.79% by February 2026, reflecting efficient management of production costs relative to sales growth over time.
PE: -35.3x
AB Dynamics, a player in the European market, is currently drawing attention due to its growth potential and insider confidence. Earnings are projected to grow by 97% annually, indicating strong future prospects. Despite relying solely on external borrowing for funding—which carries higher risk—the company maintains a strategic focus on innovation. Recent leadership changes include Edward James Haycock joining as director in September 2026, potentially steering the company towards new opportunities. Revenue guidance for fiscal year ending August 2026 is set at £91.6 million, reflecting steady operational progress.
- Get an in-depth perspective on AB Dynamics' performance by reading our valuation report here.
Review our historical performance report to gain insights into AB Dynamics''s past performance.
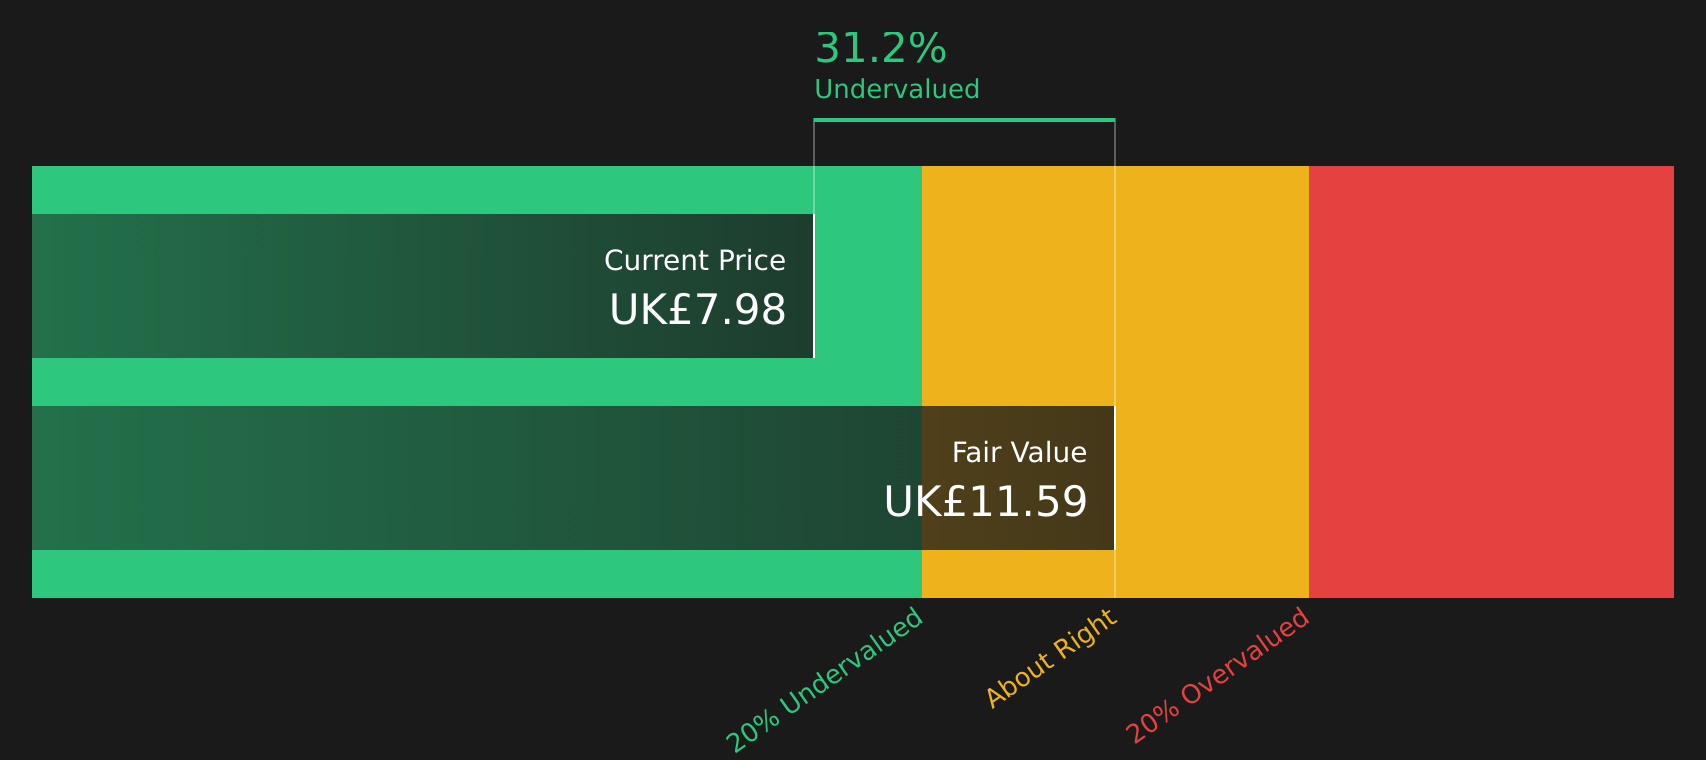
Wizz Air Holdings (LSE:WIZZ)
Simply Wall St Value Rating: ★★★★★☆
Overview: Wizz Air Holdings is a European low-cost airline focusing on providing affordable air travel across various destinations, with a market capitalization of approximately €2.47 billion.
Operations: The company primarily generates revenue from its airline operations, with a recent revenue figure of €5.77 billion. A significant portion of costs is attributed to COGS, which amounted to €4.68 billion in the latest period. The gross profit margin has been observed at 18.84% in the most recent data point provided, indicating the percentage of revenue that exceeds the cost of goods sold before accounting for other expenses.
PE: -5.3x
Wizz Air Holdings, a smaller European airline company, is catching attention for its potential value. Despite a challenging financial position with debt not well covered by operating cash flow and reliance on external borrowing, the company shows promising growth prospects with earnings projected to increase 61.2% annually. Recent operating results highlight significant capacity and passenger growth year-over-year, though load factors slightly dipped. Insider confidence is evident through recent share purchases in the past months, suggesting optimism about future performance amidst strategic plans to optimize networks and manage costs effectively by fiscal 2030.
- Dive into the specifics of Wizz Air Holdings here with our thorough valuation report.
Assess Wizz Air Holdings' past performance with our detailed historical performance reports.
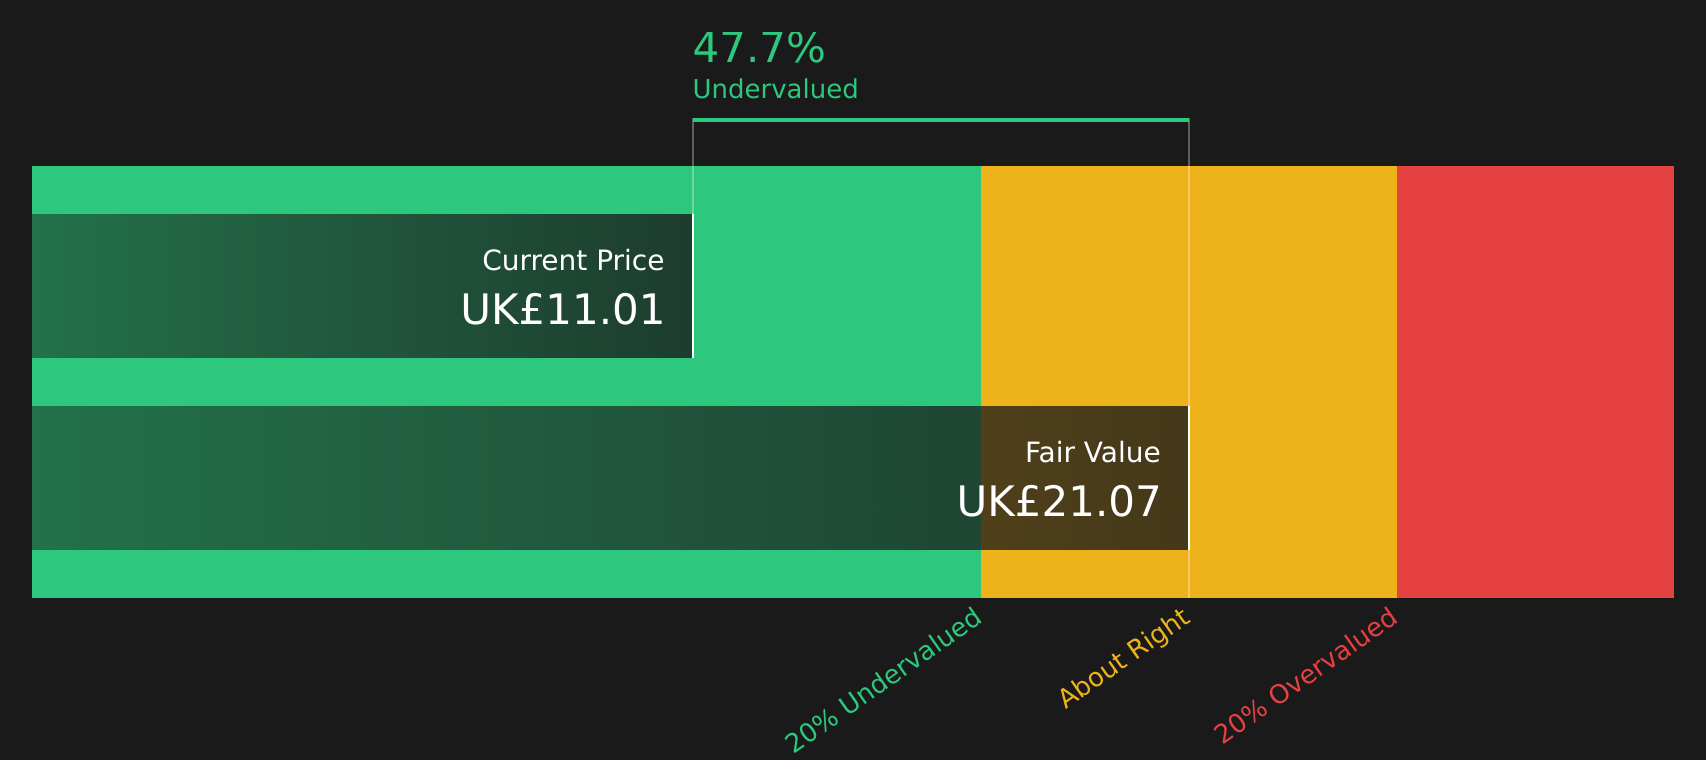
Attendo (OM:ATT)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Attendo is a leading provider of care and health care services, with operations focused on delivering high-quality care solutions.
Operations: The company's revenue primarily comes from its Care and Health Care Services, totaling SEK 18.97 billion in the most recent period. The gross profit margin has seen fluctuations, reaching 36.90% in the latest quarter, indicating changes in cost management or pricing strategies over time. Operating expenses are a significant part of the cost structure, with general and administrative expenses consistently forming a large portion of these costs.
PE: 16.9x
Attendo, a European care service provider, is expanding with new facilities in Finland and Sweden, including the recently completed Attendo Kuisma in Helsinki. The company has shown insider confidence through share purchases between May and June 2026, acquiring 2.1 million shares for SEK 241 million. Despite relying on external borrowing for funding, Attendo's earnings per share have doubled from SEK 0.59 to SEK 1.32 year-on-year by Q2 2026. Future growth could be bolstered by strategic acquisitions and ongoing expansions in response to increasing demand for elderly care services across Europe.
- Unlock comprehensive insights into our analysis of Attendo stock in this valuation report.
Examine Attendo's past performance report to understand how it has performed in the past.
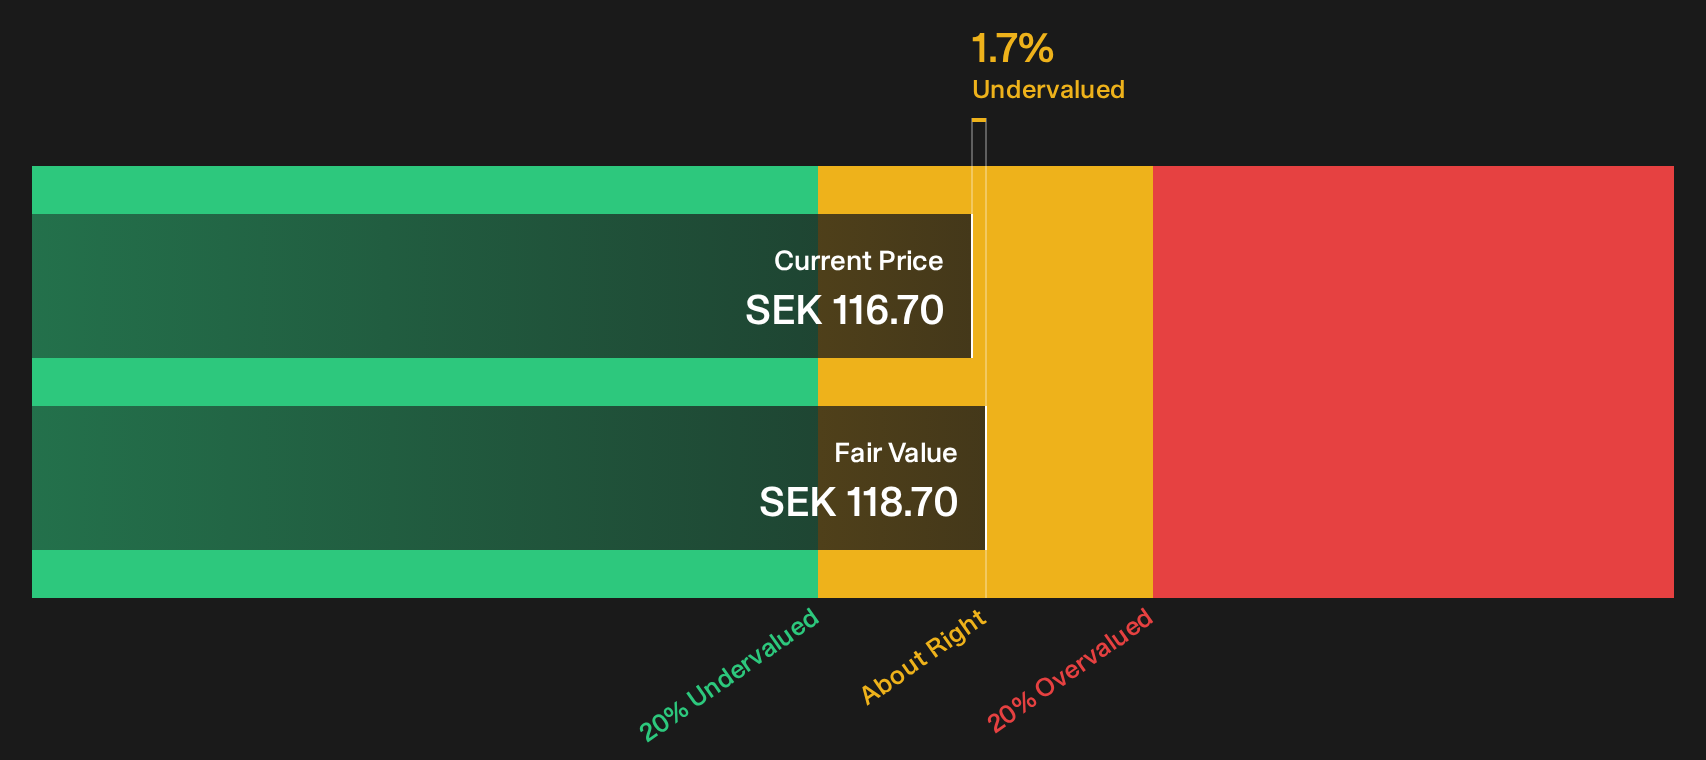
Next Steps
- Investigate our full lineup of 29 Undervalued European Small Caps With Insider Buying right here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com