


Why Kesko Oyj’s latest earnings matter for shareholders
Kesko Oyj (HLSE:KESKOB) just released third quarter and nine month figures that showed higher sales, net income and earnings per share compared with the same periods in 2025.
The update provides fresh detail on how the retailer’s grocery, building and technical, and car activities translated into €3,394.5 million of quarterly sales and €162.9 million in profit.
At a share price of €25.34, Kesko Oyj has seen strong momentum, with a 30 day share price return of 9.98% and a year to date share price return of 32.53%, while the 3 year total shareholder return of 81.35% points to sustained gains. The latest earnings release adds another near term catalyst to that trend.
Capture this earnings momentum in context and scan a curated 195 high quality undervalued stocks that share characteristics with Kesko Oyj's scale and multi-division model.Kesko Oyj is delivering higher sales and profit, and the share price has raced ahead this year. The open question now is whether that strength is already fully reflected in the valuation.
Most Popular Narrative: 9% Overvalued
Kesko Oyj closed at €25.34, while the most followed narrative points to a fair value of €23.30 based on its long term cash flow outlook and a 6.49% discount rate. That gap puts the spotlight on whether the recent earnings strength and share price rally have pulled future returns forward.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €14.6 billion, earnings will come to €589.7 million, and it would be trading on a PE ratio of 19.0x, assuming you use a discount rate of 6.5%.
Given the current share price of €24.4, the analyst price target of €23.3 is 4.7% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 10 investors see Kesko Oyj as 9% overvalued.
Result: Fair Value of €23.30 (OVERVALUED)
Still, that overvaluation story can unravel quickly if heavy grocery investment fails to lift returns, or if weaker construction activity keeps Building and Technical Trade profitability under pressure.
Find out about the key risks to this Kesko Oyj narrative.
Another View: Kesko Oyj Through a Cash Flow Lens
While the popular narrative sees Kesko Oyj as 9% overvalued at €25.34 against a fair value of €23.30 based on earnings and P/E, the SWS DCF model points in the opposite direction. In that framework, the shares sit at a steep discount to an estimated future cash flow value of €59.93, suggesting the earnings based view might be missing part of the story.
Both lenses are built on explicit assumptions about growth, margins and required returns. The real question for you as a shareholder is which set of expectations feels closer to how Kesko Oyj will actually run its grocery, building and car businesses over the coming years, and which one you trust when those assumptions are tested.
Look into how the SWS DCF model arrives at its fair value.
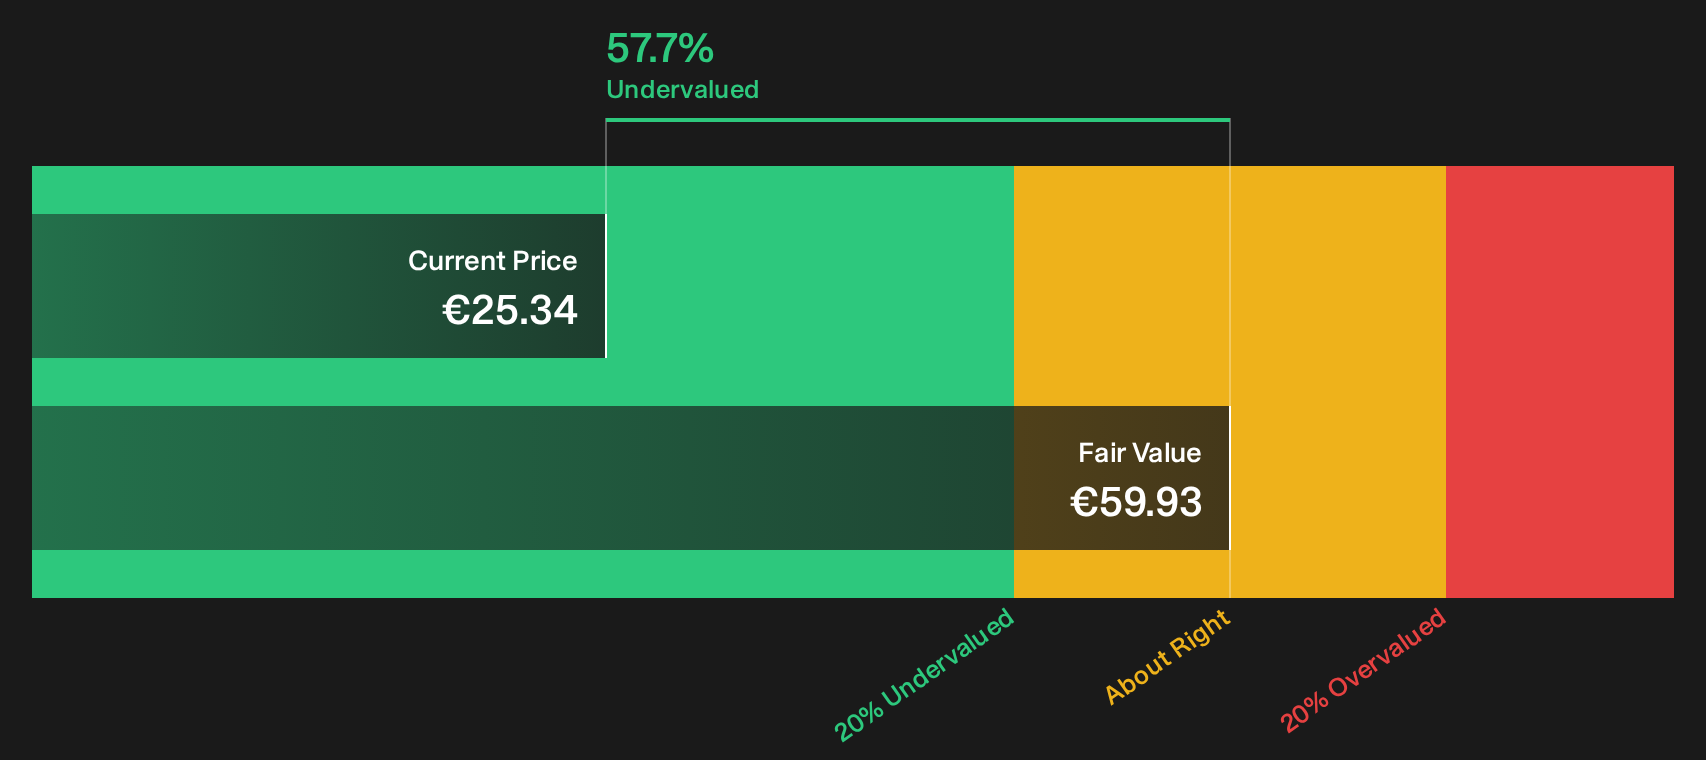
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kesko Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like this rarely stay unresolved for long, so it helps to look under the hood yourself and form a clear stance. To weigh up both the concerns and the upside potential, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kesko Oyj?
Do not stop at Kesko Oyj. The market is full of other possibilities, and a few minutes with a focused screener can completely change your shortlist.
- Target stability and income by reviewing strong cash generators that also pay out meaningful yields through the 228 dividend fortresses.
- Hunt for quality at a sensible entry point by checking companies that look mispriced on fundamentals using the 195 high quality undervalued stocks.
- Reduce unwanted shocks in your portfolio by scanning resilient businesses with healthier risk profiles through the 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com