


- Metsä Board Oyj reported third quarter 2026 sales of €402.3 million and a net loss of €2.4 million, with nine month sales of €1,227.9 million and a loss of €23.2 million, all lower than the prior year’s levels.
- The company’s losses narrowed sharply compared with a year earlier even as revenue softened, which points to tighter cost control and more disciplined operations at Metsä Board Oyj.
- We will now look at how Metsä Board Oyj's investment narrative is influenced by the sharply reduced quarterly loss despite softer sales.
Scan other paper and packaging players that combine cost discipline with earnings recovery potential. You can use our hand picked list of list of solid balance sheet and fundamentals (207 results) as a starting point.
Metsä Board Oyj Investment Narrative Recap
To own Metsä Board Oyj, you need to believe that a smaller, more efficient paperboard producer can turn cost work into durable profitability even in choppy demand. The sharp reduction in quarterly losses suggests the cost program is flowing through the income statement. The near term swing factor still looks like execution on identified savings while keeping capital spending low.
The biggest operational risk right now is that mills exposed to pulp pricing, wood costs and US folding boxboard demand, such as Husum, keep dragging on results despite these efforts. The latest quarter did not remove that risk, although it did show that broader cost discipline can partly offset a soft top line.
The earnings release for the third quarter and nine month period is the key disclosure for this story. It showed sales of €402.3 million in the quarter and €1,227.9 million for the year to date, with much smaller losses than a year earlier. That outcome lines up with the already announced €200 million EBITDA improvement and cost saving ambition.
For you as a shareholder, the link is simple. If Metsä Board Oyj keeps turning that program into lower unit costs while capital expenditure stays clearly below €100 million a year, any improvement in demand or pricing would have a cleaner path into earnings. If pulp markets, Husum and US folding boxboard volumes stay weak, that same operating leverage cuts the other way and could hold back the recovery story.
Metsä Board Oyj's current analyst storyline points to revenues of €2.0 billion and earnings of €207.2 million by 2029, built on an assumed 7.0% yearly rise in revenue and an earnings swing of about €356 million from a loss of €148.8 million today to the forecast profit level.
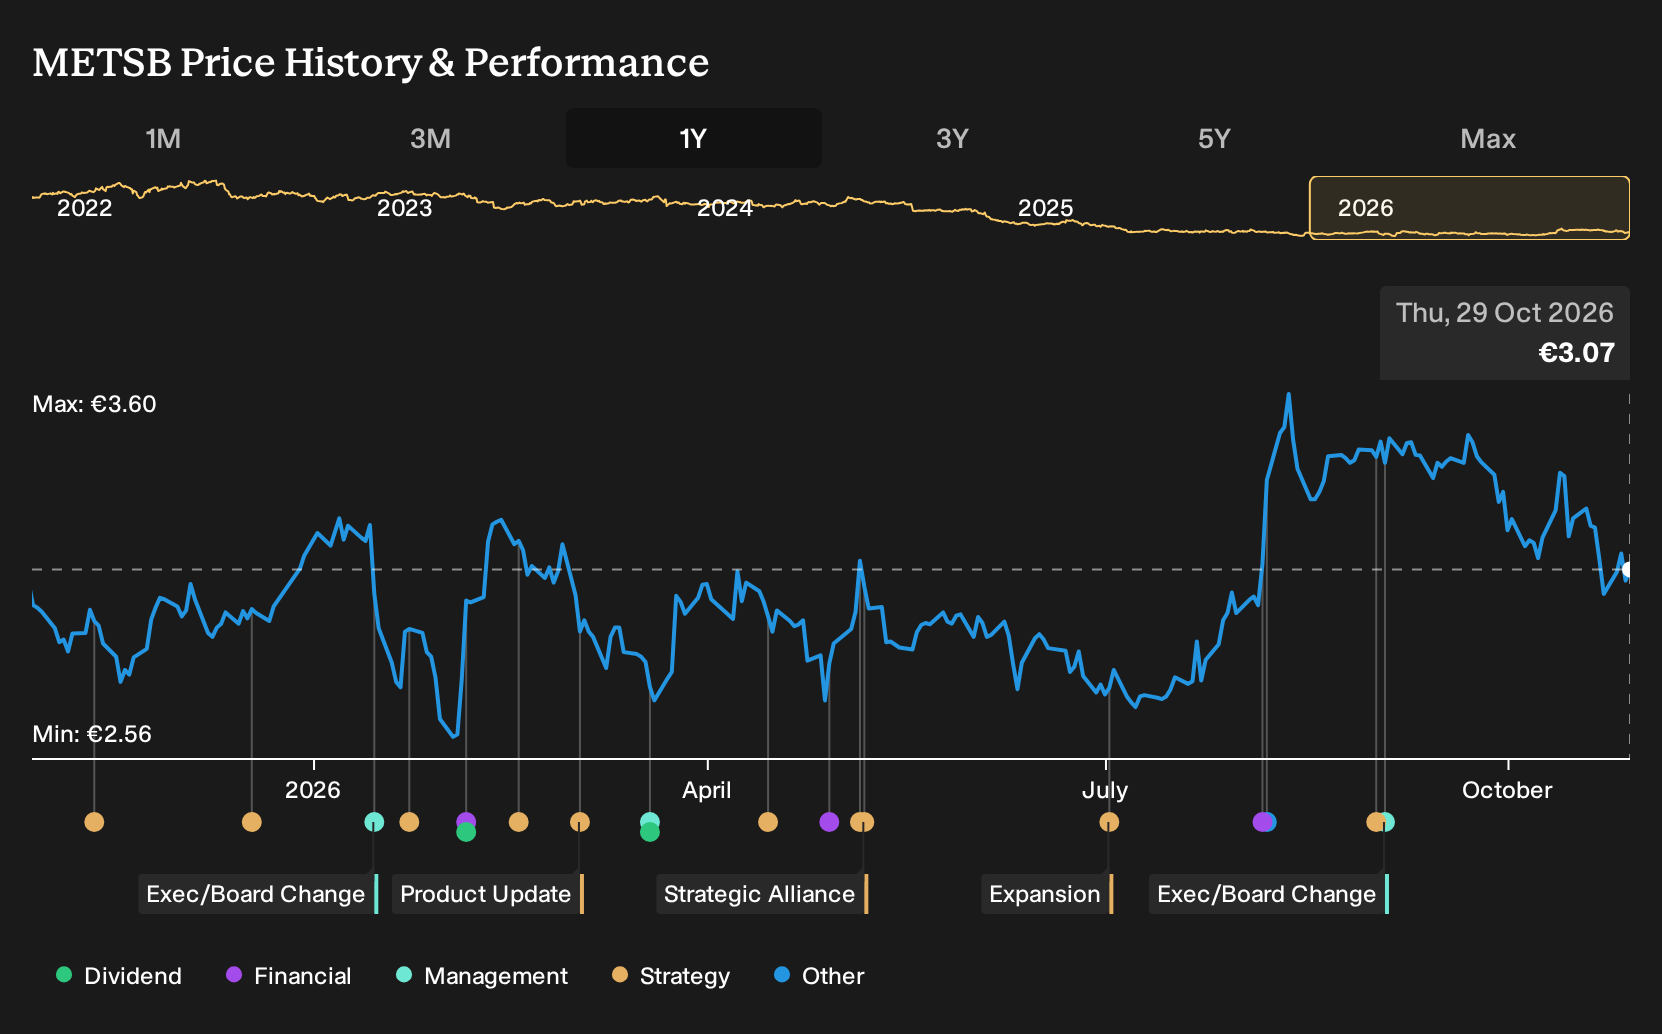
Uncover how Metsä Board Oyj's fair value indicates a 9% potential upside to its current price that could narrow quickly as expectations reset.
Exploring Other Perspectives
The bearish narrative for Metsä Board Oyj leans heavily on Husum risk. Those analysts argue that ongoing weakness there could cap earnings, which is why they were only pencilling in about €1.8b of revenue and €176.2 million of profit by 2029. That is far more cautious than consensus, and this fresh earnings release may reshape both stories.
Explore another Metsä Board Oyj fair value estimate, including one that suggests it could be worth just €3.35.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Metsä Board Oyj research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Metsä Board Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Metsä Board Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Metsä Board Oyj?
If the Metsä Board Oyj story has you thinking about where risk, balance sheets and earnings potential line up best, it can help to compare it with a wider set of opportunities using the Simply Wall St Screener.
- For investors who want potential upside without ignoring fundamentals, scan a curated set of 607 high quality undiscovered gems that pair quality metrics with less crowded tickers.
- If balance sheet strength is near the top of your checklist, focus on stability first by reviewing a 228 resilient stocks with low risk scores that tends to hold up better when conditions get tougher.
- Income seekers who care about cash returns today as much as capital gains tomorrow can start with a focused group of 228 dividend fortresses built around yields from 5% and above.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com