


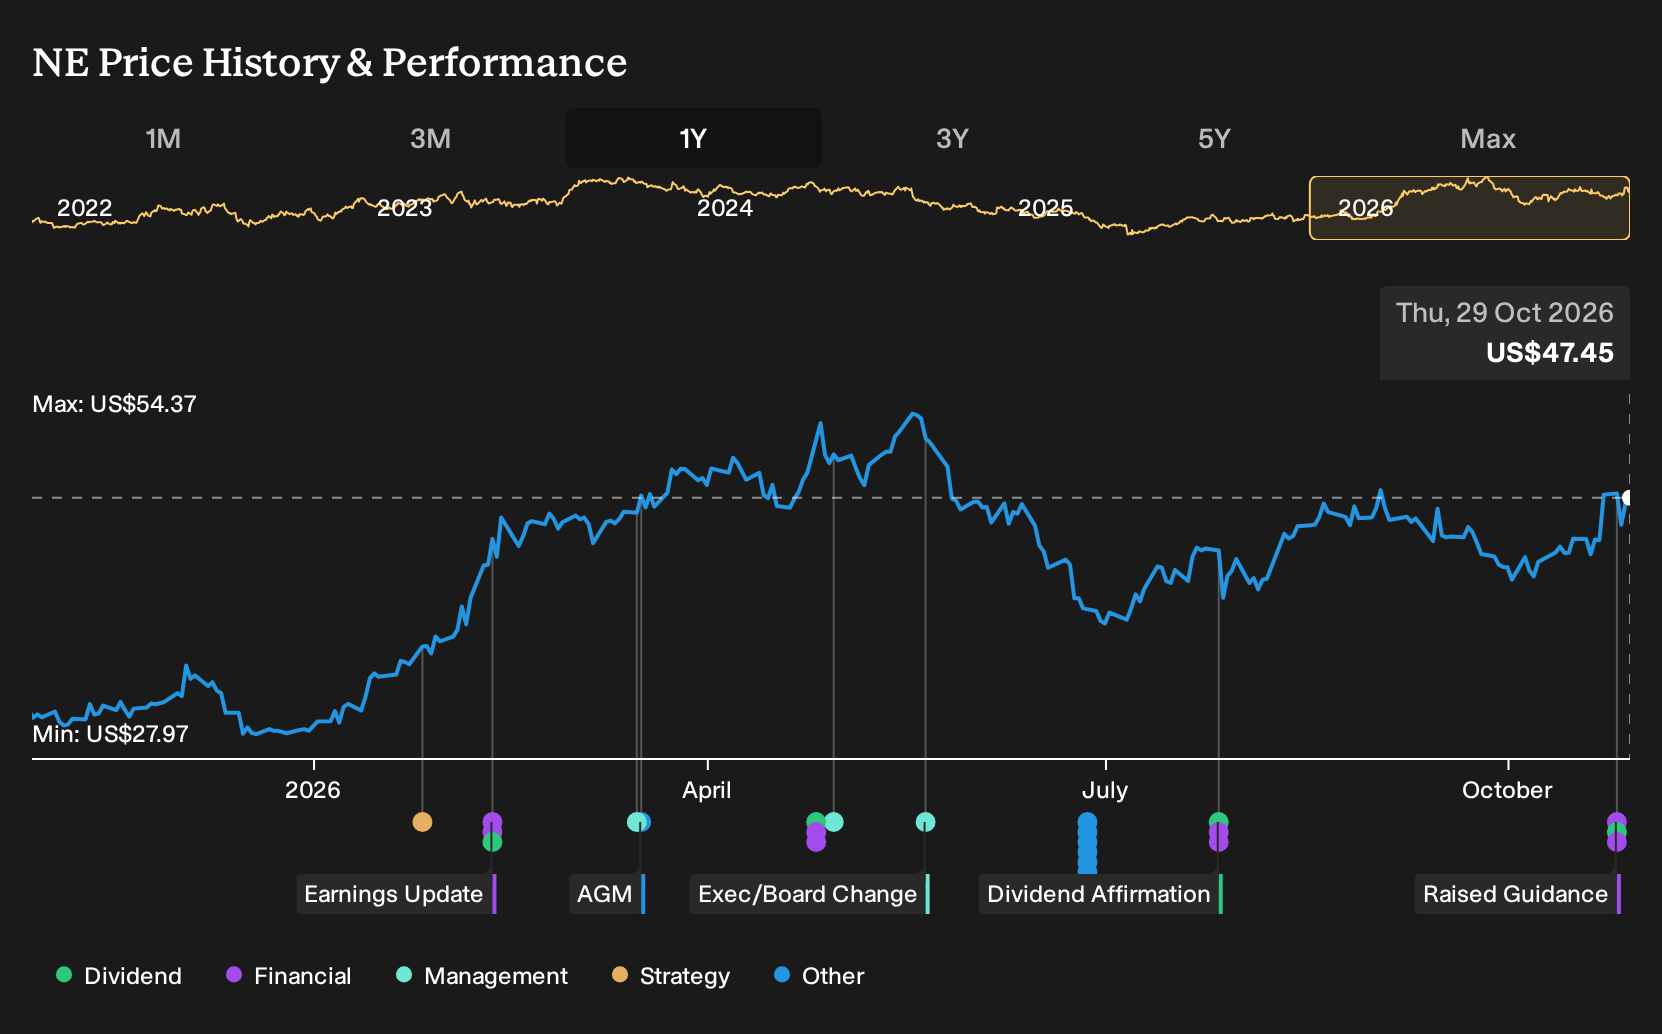
- Noble Corporation reported Q3 2026 revenue of US$728.76 million and a net loss of US$117.02 million. The company reaffirmed full year guidance, narrowing 2026 revenue expectations to a range of US$2.85 billion to US$2.9 billion, and its board approved a US$0.50 per share quarterly dividend to be paid in December 2026.
- The drilling contractor combined a wider reported loss with a US$6.7 billion contracted backlog and roughly US$560 million of fresh awards, highlighting the tension between current operational setbacks and visibility on future offshore work, especially in deepwater projects.
- The focus now shifts to what this combination of a Q3 loss and reaffirmed 2026 guidance may indicate for Noble's broader investment narrative.
Compare Noble's guidance and backlog story with other offshore and energy contractors that screen well on cash flow and balance sheets by using our hand picked list of solid balance sheet and fundamentals (23 results) for context.
Noble Investment Narrative Recap
To own Noble, you need to believe that a tight ultra deepwater market and a US$6.7b backlog can outweigh messy near term execution. The narrowed 2026 revenue guidance to US$2.85b to US$2.9b signals management still sees the core demand story intact. The immediate swing factor is how smoothly Noble turns rig reactivations and upgrades into usable contracted days.
The biggest near term risk is operational disruption, especially around Brazilian rigs and any fresh downtime that slows backlog conversion into cash. The Q3 net loss and softer nine month revenue underline that this risk is already live. The latest update changes the narrative tone but does not alter the fundamental risk profile in a dramatic way.
The clearest announcement to focus on here is the narrowed full year 2026 outlook. Adjusted EBITDA guidance is held at US$850m to US$900m, and revenue is tightened to US$2.85b to US$2.9b. That sits against around US$2.6b of backlog scheduled for 2027 and about 20% more contracted fleet capacity expected in the second half of 2027 compared with the first half.
For you as a shareholder or prospective investor, the link is simple. Guidance assumes Noble can work through timing issues, execute on reactivations and keep rigs in markets like Brazil and Norway earning at current day rates. Any fresh delays, legal costs from the Brazil investigation or dividend commitments that run ahead of free cash flow would quickly become the key pressure points on that story.
Noble Guidance Versus Long Term Analyst Models
Noble's narrative projects US$3.6b revenue and US$748.0m earnings by 2029. This rests on analysts assuming 7.7% yearly revenue growth and earnings rising by about US$598m from US$149.6m today.
Discover why the current outlook for Noble's fair value appears to be consistent with its existing market price.
Exploring Other Perspectives
For a very different lens on Noble, focus on capital strain rather than backlog strength. The most cautious analysts saw 2029 earnings closer to US$555.7 million on about US$3.7b of revenue, and argued the stock merited roughly a US$27.75 fair value. That is a much harsher story. These views were formed before the latest guidance and results, so treat them as starting points and explore how your own expectations might shift after this news.
Explore 4 other Noble fair value estimates, including one that suggests as much as 42% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Noble research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Noble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Noble's overall financial health at a glance.
Looking For More Investment Ideas Beyond Noble?
Once you have a view on Noble, it can help to compare that thesis with other companies that match the type of quality or risk profile you want in a portfolio. The Simply Wall St Screener is built for exactly that kind of targeted search, so you can move from a single stock story to a broader watchlist that fits your own rules.
- For investors who want staying power as a starting point, focus on balance sheet resilience and cash generation by scanning our list of solid balance sheet and fundamentals (23 results) and see which businesses clear a similar quality bar.
- If you are hunting for mispriced opportunities, filter by valuation and financial strength with our 30 high quality undervalued stocks and compare where expectations and current prices look out of sync.
- Income focused readers who care about cash returns can zero in on payout strength and yield reliability using our 7 dividend fortresses to surface higher yielding options for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com