


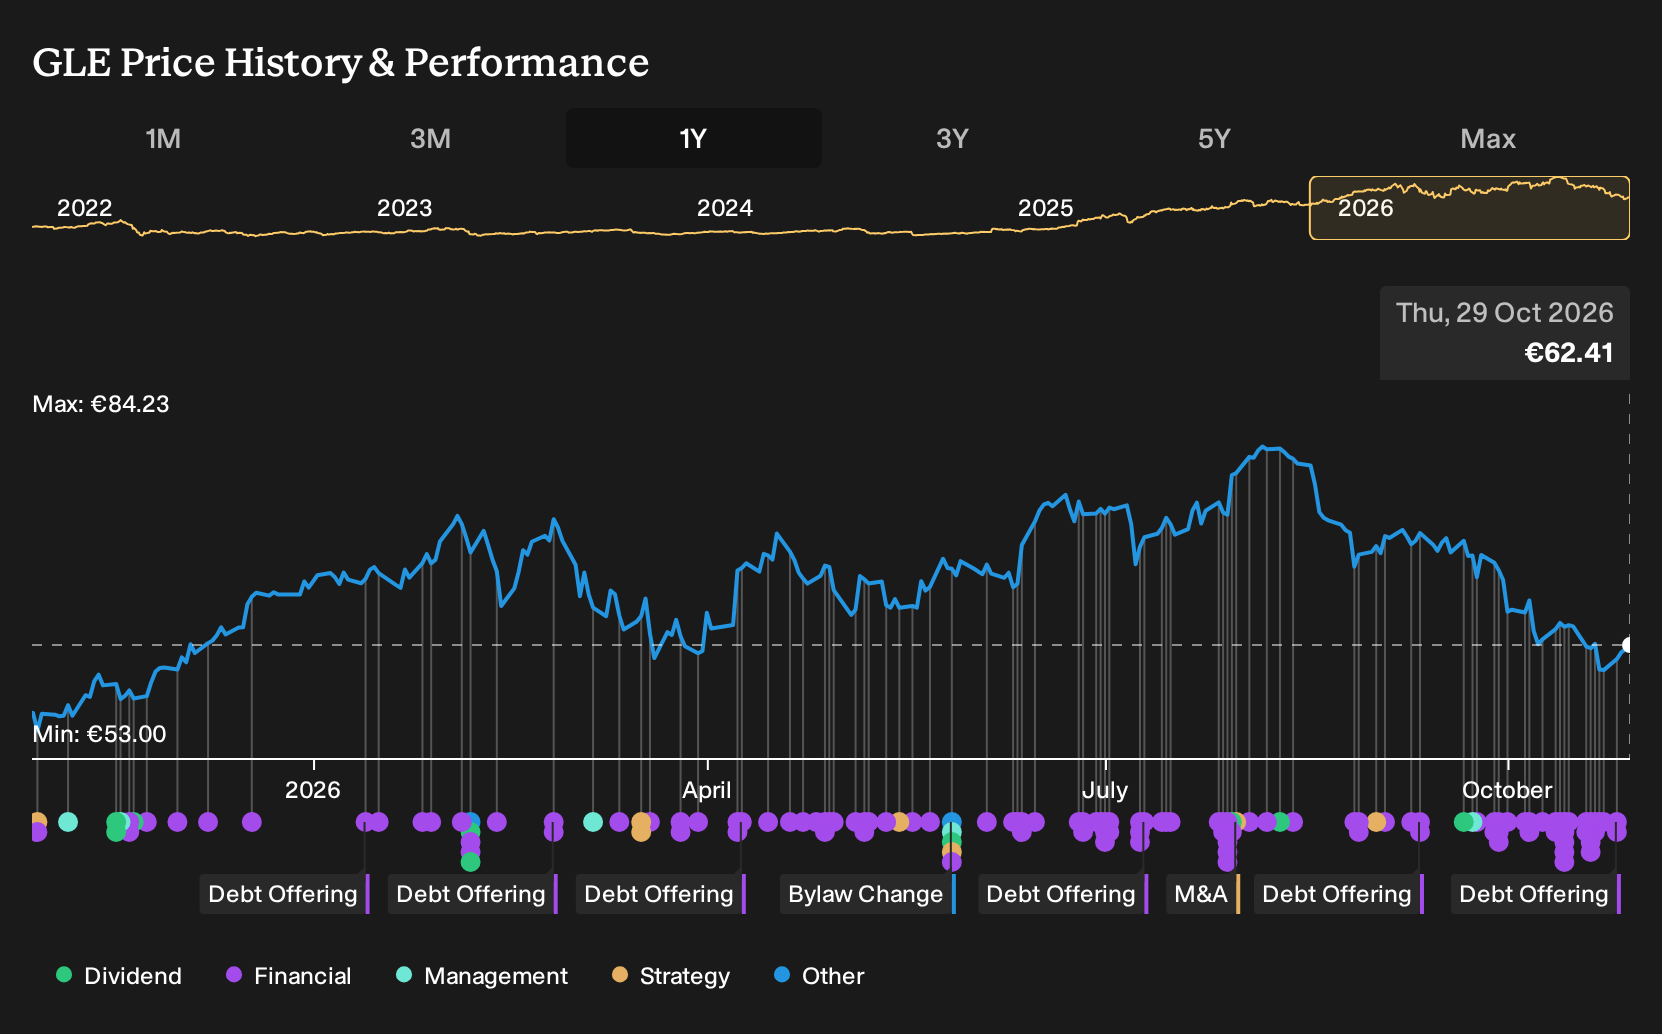
- Société Générale Société anonyme reported stronger third quarter 2026 results, with net income of €1,888 million and nine month net income of €5,374 million, alongside multiple new fixed income offerings across euros and dollars.
- The group combined higher net interest income and solid nine month profitability with continued bond issuance activity that spans callable senior unsecured notes and green preferred securities across a wide range of maturities and coupon levels.
- We will look at how Société Générale's stronger nine month net income shapes the investment narrative around cost efficiency and returns.
Scan how Société Générale's earnings and bond issuance compare with peers by reviewing a curated list of banks and lenders screened for balance sheet strength and fundamentals in the list of solid balance sheet and fundamentals (207 results).
Société Générale Société anonyme Investment Narrative Recap
To own Société Générale Société anonyme, you need to believe the cost efficiency, digital retail push and capital light businesses can sustain returns while keeping capital strong. The latest nine month net income of €5,374 million and 12.3% ROTE show the plan currently working. The near term swing factor is whether this profitability level can be held while French retail, markets activity and credit costs stay disciplined.
The biggest risk is that much of the cost story is already baked into expectations. With a cost to income ratio now at 58.8%, any slip in revenue, higher funding costs or a cost of risk closer to historical stress levels could quickly pressure that ratio. If investors start to doubt the balance between high payout ambitions and a CET1 ratio just above 13%, the equity could see pressure even if earnings remain broadly in line.
The most relevant update is the third quarter 2026 earnings print. Net interest income reached €7,173 million in the quarter and €21,375 million for the first nine months, with group net income of €1,888 million in Q3. That performance, together with the 12.3% nine month ROTE, already sits above the 2026 target of around 11%. This directly connects to the cost and capital narrative.
For you as a shareholder, this matters because execution risk now shifts from promise to proof. Management is running a cost to income ratio below the 60% threshold and has just completed a €1.5b share buyback while keeping the CET1 ratio at 13.4%. The catalyst is whether that combination of efficiency and capital return can be repeated without eroding buffers, given existing concerns about higher risk funding, bad loans and a low allowance for bad loans.
Société Générale Société anonyme's narrative projects €30.3 billion revenue and €7.8 billion earnings by 2029. This reflects an assumed 5.1% yearly revenue growth and an earnings increase of about €2.1 billion from €5.7 billion today.
Uncover why Société Générale Société anonyme's fair value indicates a 42% potential upside to its current price, a discount that could close faster than expected.
Exploring Other Perspectives
Cost risk sits at the center of the bearish view. The most cautious analysts worry that Société Générale Société anonyme is already close to peak efficiency and that future savings will be slower and messier. They were only penciling in about €30.3b of 2029 revenue and €7.2b of earnings, so this latest earnings beat and steady bond issuance could force them to rethink. You can treat that lower bar as a stress test and compare it with the consensus case before deciding which story is closer to your own expectations.
Explore 3 other Société Générale Société anonyme fair value estimates, including one that suggests it could be worth just €88.63!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Société Générale Société anonyme research is our analysis highlighting 5 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Société Générale Société anonyme. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Société Générale Société anonyme's overall financial health at a glance.
Looking For More Investment Ideas Beyond Société Générale?
If this Société Générale Société anonyme story has sharpened your thinking on banks and lenders, use that same lens across the wider market. A focused screener can help you quickly surface a shortlist of stocks that match the balance of quality, risk and income you want.
- For investors who care most about resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (207 results) that keeps financial strength front and center.
- If you are hunting for quality at a reasonable price, scan a hand picked group of 195 high quality undervalued stocks that combine solid businesses with potentially appealing valuations.
- Income focused investors can concentrate on cash payouts by reviewing a targeted selection of 228 dividend fortresses that aim to pair higher yields with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com