


Endesa (BME:ELE) has released its nine-month 2026 earnings, reporting higher sales, revenue and net income compared with the same period in 2025.
Endesa’s recent report lands after a strong run in the shares, with the stock closing at €43.46 and a year-to-date share price return of 39.61%. This aligns with a 44.15% total shareholder return over twelve months and hints at positive momentum building around the earnings story.
Scan other utilities showing similar earnings traction by reviewing our curated 43 power grid technology and infrastructure stocks alongside Endesa’s latest numbers.
After a 39.61% gain this year and sizeable three and five year total returns, the key issue for Endesa holders is simple. Is most of the rerating already in the price, or is there still clear upside left?
Most Popular Narrative: 20.8% Overvalued
Endesa’s most followed narrative pins fair value at €35.97, well below the recent €43.46 close. This frames the latest rally as generous against the cash flows analysts are modelling under a 7.4% discount rate.
The current valuation implies the market is placing a rich multiple on Endesa’s relatively stable earnings mix and capital return plans. This is hard to reconcile with this narrative’s view that the stock is overvalued and that bearish concerns on growth and competition remain underappreciated.
See why 30 investors see Endesa as 21% overvalued.
Result: Fair Value of €35.97 (OVERVALUED)
Still, if Spanish regulators keep allowed returns steady and Endesa delivers on fixed cost cuts, the current rich multiple could appear less stretched.
Find out about the key risks to this Endesa narrative.
Another View: Endesa Through The Earnings Lens
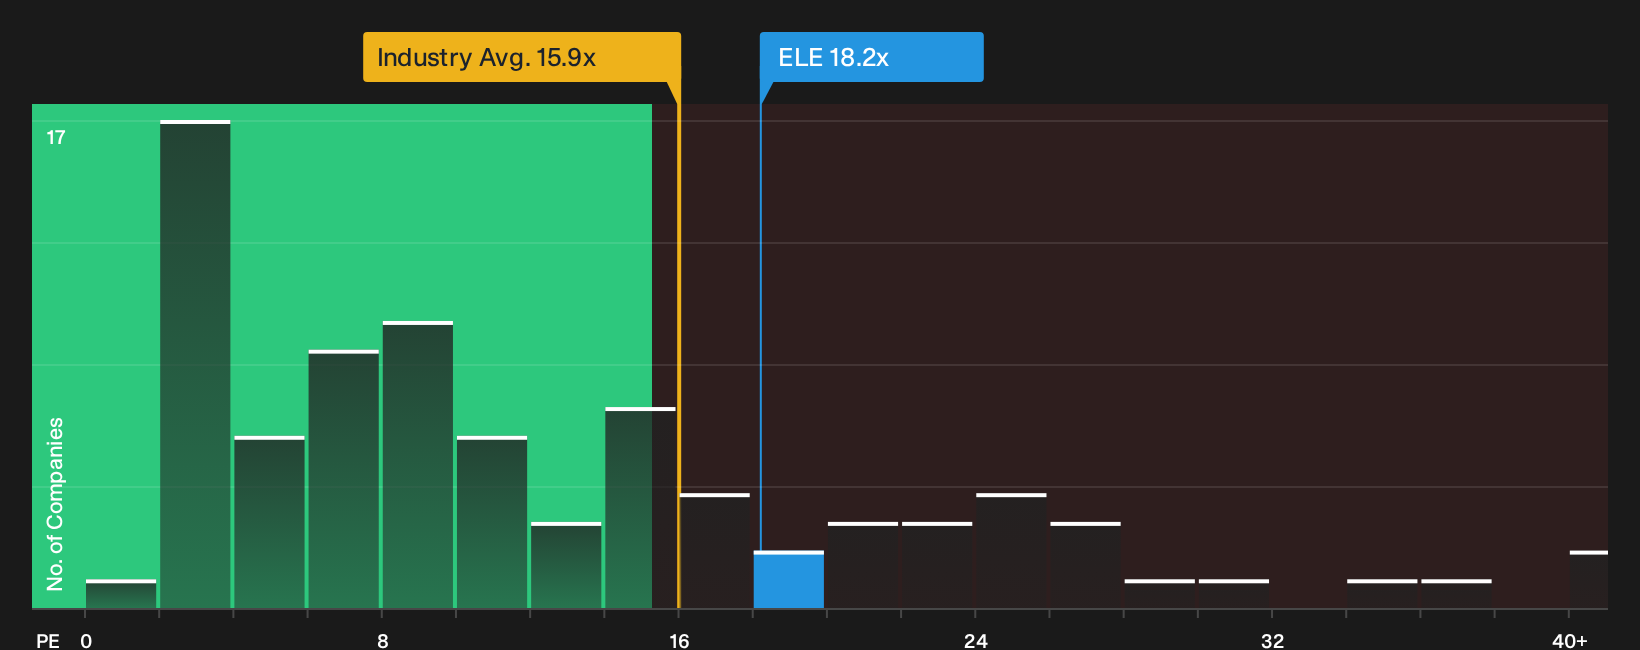
The earlier narrative leans on fair value of €35.97, yet Endesa’s current P/E of 18.2x tells a slightly different story. That ratio is almost identical to the fair ratio of 18.3x, higher than the European utilities average of 15.7x, and below peer levels at 21.8x.
In practice, that mix points to a stock that screens as roughly in line with its own fundamentals, richer than the wider sector, and cheaper than closer comparables. It raises a simple question for investors: Is this a reasonable premium for Endesa’s profile or a tight margin for error at €43.46?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Endesa’s valuation can be hard to sit with, especially when both risks and rewards are clearly on the table. Act quickly, review the underlying data yourself and pressure test both sides of the argument with the 1 key reward and 2 important warning signs
Looking for more Endesa sized investment ideas?
If Endesa has you thinking about what else might be hiding in plain sight, now is the moment to broaden your watchlist before the crowd catches up.
- Target resilient balance sheets and strong fundamentals by scanning a curated list of solid balance sheet and fundamentals (207 results) that can support cash flows through different market conditions.
- Hunt for quality at a sensible price with our data driven 195 high quality undervalued stocks that highlights stocks combining robust metrics with appealing valuations.
- Lock in potential income ideas by reviewing a focused 228 dividend fortresses built around companies offering higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com