


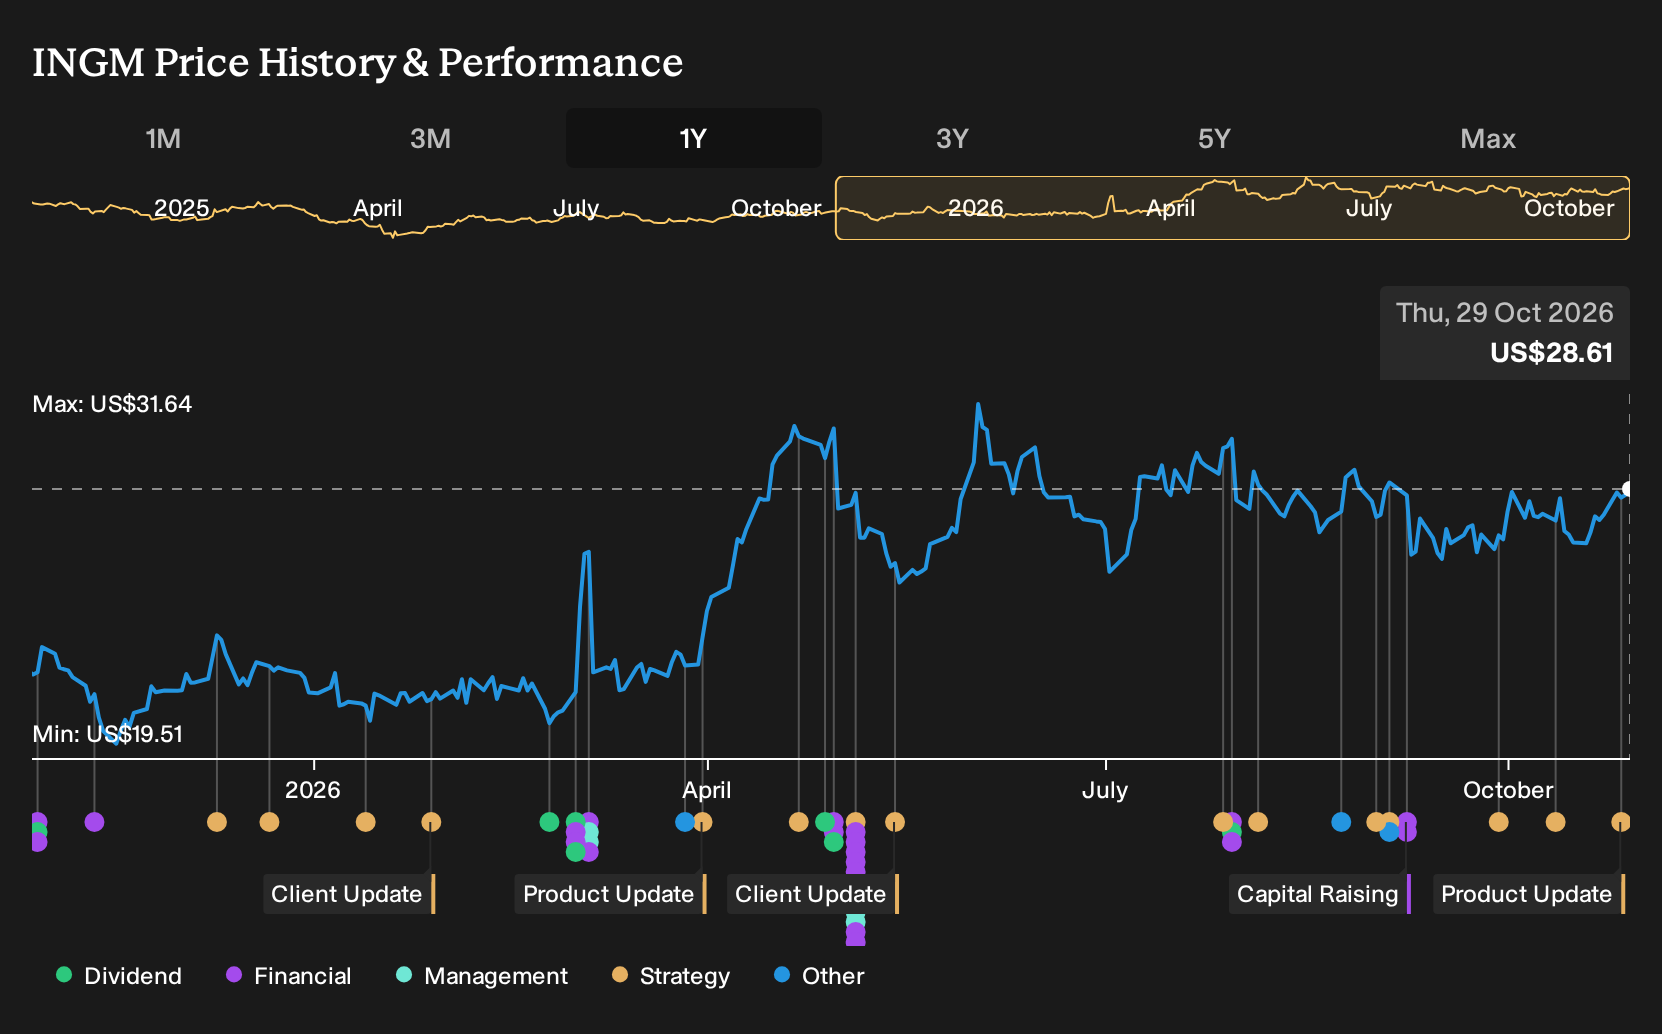
- Ingram Micro Holding reported Q3 2026 sales of US$15,220.46 million and net income of US$131.08 million, with earnings per share from continuing operations of US$0.57, and issued Q4 2026 net sales guidance of US$17.5 billion to US$17.9 billion.
- The company paired these results with a higher quarterly dividend and the planned rollout of its SMB Quick Buy AI powered purchasing flow for Cisco solutions, which together indicate an emphasis on both shareholder cash returns and scaling higher efficiency digital distribution.
- We will now look at how Ingram Micro Holding’s reported earnings and higher dividend may relate to its longer term investment narrative.
Extend your search beyond Ingram Micro Holding and review a curated set of peers that have already been vetted for balance sheet strength and fundamentals with the list of solid balance sheet and fundamentals (23 results).
Ingram Micro Holding Investment Narrative Recap
To own Ingram Micro Holding, you need to be comfortable with a low margin distribution model that depends on volume, vendor relationships and tight working capital management. The Q3 report, with US$15,220.46 million in sales and US$131.08 million in net income, suggests operations are currently scaling, but the model still relies on efficient inventory turns and access to funding.
The key near term catalyst is execution on higher value AI centric solutions and digital platforms like Xvantage, without letting low margin GPU and server deals dominate the mix. The biggest risk remains capital intensity and leverage, where any slowdown in sell through or tighter credit could quickly pressure cash generation despite the current earnings run rate.
The rollout of SMB Quick Buy on Xvantage for Cisco solutions looks most relevant to the current earnings story. It ties directly into Ingram Micro Holding’s goal of using AI and automation to lower cost to serve and make smaller SMB transactions more economical. That speaks to margin mix, not just headline revenue.
For you as a shareholder, the question is whether SMB Quick Buy and similar tools can meaningfully lift higher margin SMB and cloud activity versus large, low margin infrastructure deals. Execution risk is real, since slower partner adoption or competing ecosystems could limit the impact of these platforms and leave the business more exposed to hardware cycles and working capital swings.
Ingram Micro Holding's current analyst narrative points to revenues of US$61.4b and earnings of US$678.6 million by 2029, based on an assumed 3.1% yearly revenue growth rate and a forecast consensus earnings increase of about US$248 million from earnings today of US$430.6 million.
Uncover how Ingram Micro Holding's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You are seeing two very different stories around Ingram Micro Holding. The bearish view fixates on free cash flow risk, with forecasts pointing to revenue of about US$60.2b and earnings of roughly US$668.3 million by 2029. That is only slightly below consensus, yet it supports a far more cautious stance. Those estimates were set before this Q3 beat, the Q4 guidance range and the dividend increase, so you may want to explore how new data could push those expectations higher or lower, and where your own conviction sits between these opposing narratives.
Explore another Ingram Micro Holding fair value estimate, including one that suggests as much as 38% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingram Micro Holding research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ingram Micro Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingram Micro Holding's overall financial health at a glance.
Looking for more investment ideas beyond Ingram Micro Holding?
Once you have a handle on Ingram Micro Holding, it can help to set it alongside other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for financial traits that matter to you, then compare business quality and balance sheet strength in a consistent way.
- If you want to keep risk in check while staying invested, start with a set of companies flagged for resilience and lower risk profiles through the 30 resilient stocks with low risk scores.
- For investors focused on total return potential with stronger fundamentals, review a hand picked group of attractively priced businesses via the 30 high quality undervalued stocks.
- If income is your priority and you care about yield today, scan for stocks with higher payout levels using the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com