


- Recent news highlights tougher regulation for Uber Technologies, including a future UK VAT shift on full private hire fares and expanded FTC data scrutiny in the US.
- These policy changes directly target how Uber Technologies prices trips and compensates drivers, which could influence profitability in its Mobility and Delivery segments.
- The key issue now is how Uber Technologies' investment narrative holds up as regulators challenge its pricing and data practices.
Uber Technologies Investment Narrative Recap
To own Uber Technologies, you need to believe its three pillars, human driven rides, delivery and autonomous investments, can collectively support durable earnings, even as regulation tightens. The short term swing factor is how management addresses UK VAT and US data scrutiny without eroding trip volumes or driver supply, especially in core Mobility markets.
The biggest near term risk is that regulatory changes and heavier competition in both delivery and robotaxis pressure pricing and margins, while Uber is also spending around US$10b on autonomous partnerships. Recent headlines add noise but do not yet change the central question around turning scale and AV spending into better unit economics.
The most relevant fresh development is the Key Food partnership that brings more than 300 co op supermarkets onto Uber Eats across the Northeast and Florida. This pushes Uber Technologies deeper into everyday grocery baskets, which tend to be higher frequency and stickier than takeaway meals and can feed into Uber One engagement.
For you as an investor, this matters because the main bullish catalysts rely on deeper cross platform use and scaling higher margin services like advertising and memberships. If Uber executes well with Key Food and similar partners, grocery traffic can support those goals, even as regulatory and autonomous vehicle risks keep execution quality under closer scrutiny.
What Current Forecasts Assume About Uber Technologies
Uber Technologies' narrative projects revenue of US$80.2b and earnings of US$11.7b by 2029, which lines up with analysts assuming 13.3% yearly revenue growth and an earnings increase of about US$2.1b from US$9.6b today.
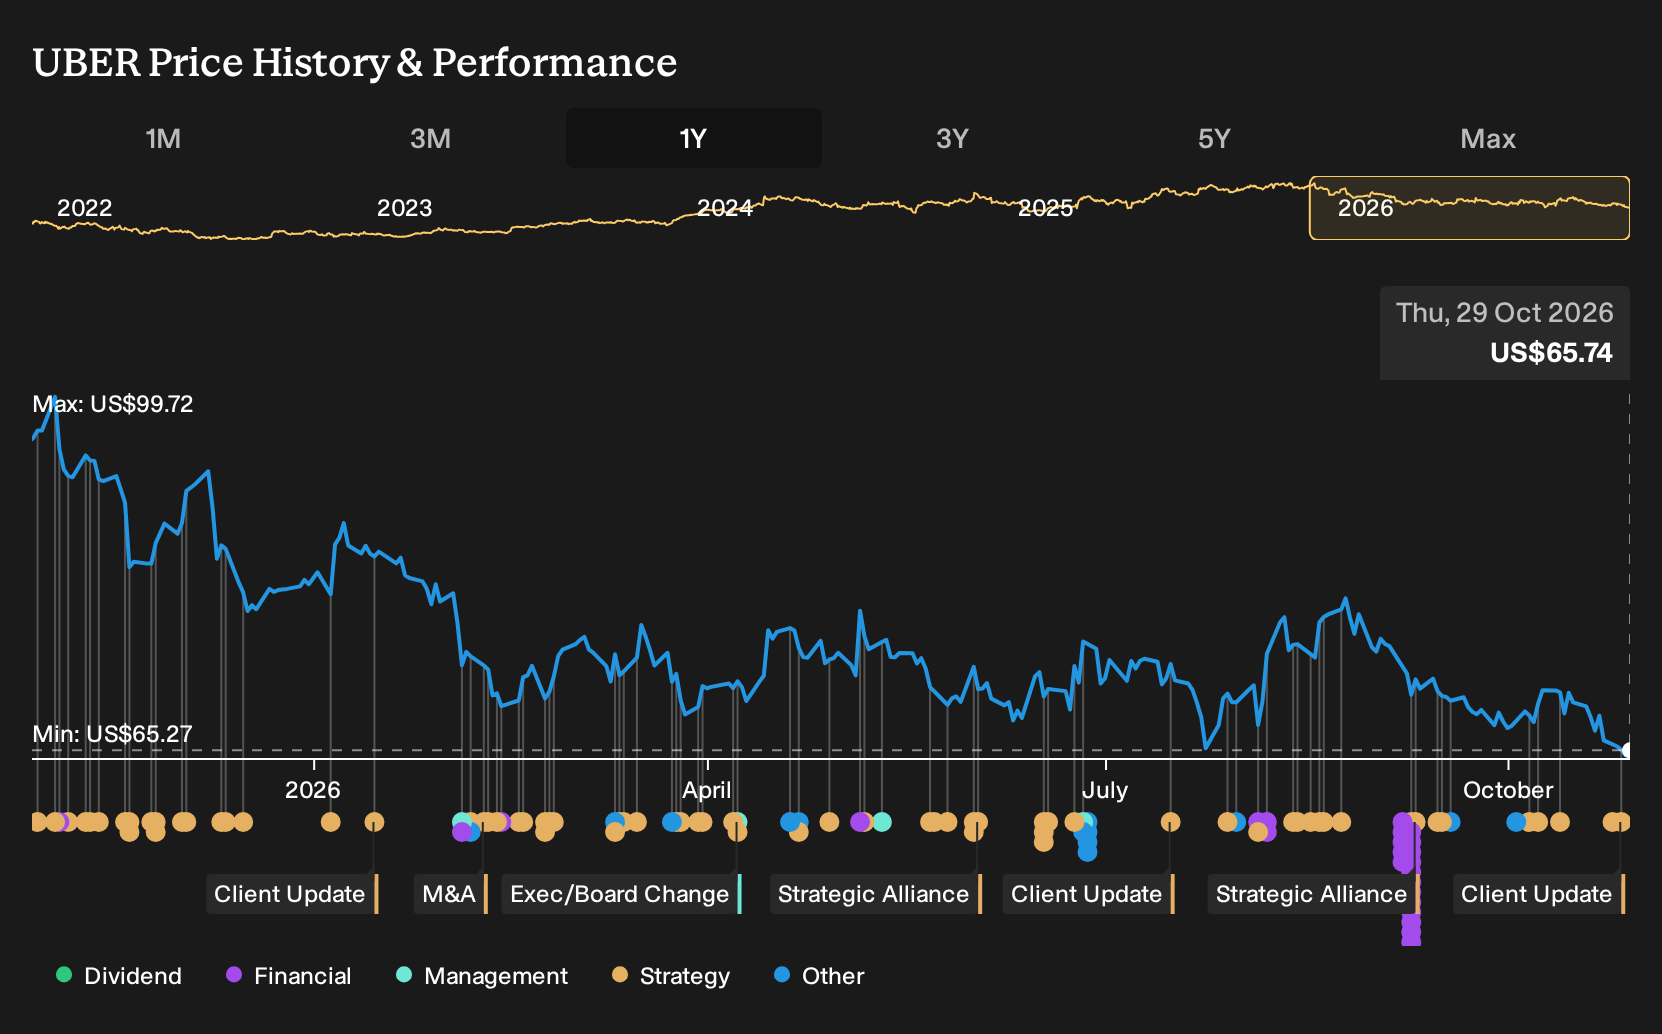
Uncover why Uber Technologies' fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle treats grocery as the weak link for Uber Technologies. The most cautious analysts were pencilling in only 6.3% yearly revenue growth to about US$66.4b and earnings of roughly US$8.2b by 2029, before this Key Food deal. That is a far more muted story. Use it as a prompt to compare multiple narratives yourself.
Explore 24 other Uber Technologies fair value estimates, including one that suggests it could be worth just $77.19.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Uber Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Uber Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Uber Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Uber Technologies?
If the Uber Technologies story has sharpened your view on risk, regulation and upside, use that lens to scan a broader watchlist. The Simply Wall St Screener can help you quickly focus on listed businesses that match the kind of balance between resilience and opportunity you want.
- Prefer staying on the front foot with potential mispricing? Review a curated 30 high quality undervalued stocks that already pass basic quality checks and might warrant a closer look.
- If capital preservation matters just as much as return potential, narrow your universe to a 30 resilient stocks with low risk scores that screen well on financial strength and earnings stability.
- For investors hunting for less crowded ideas, work through a 18 high quality undiscovered gems that combine solid fundamentals with lower current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com