


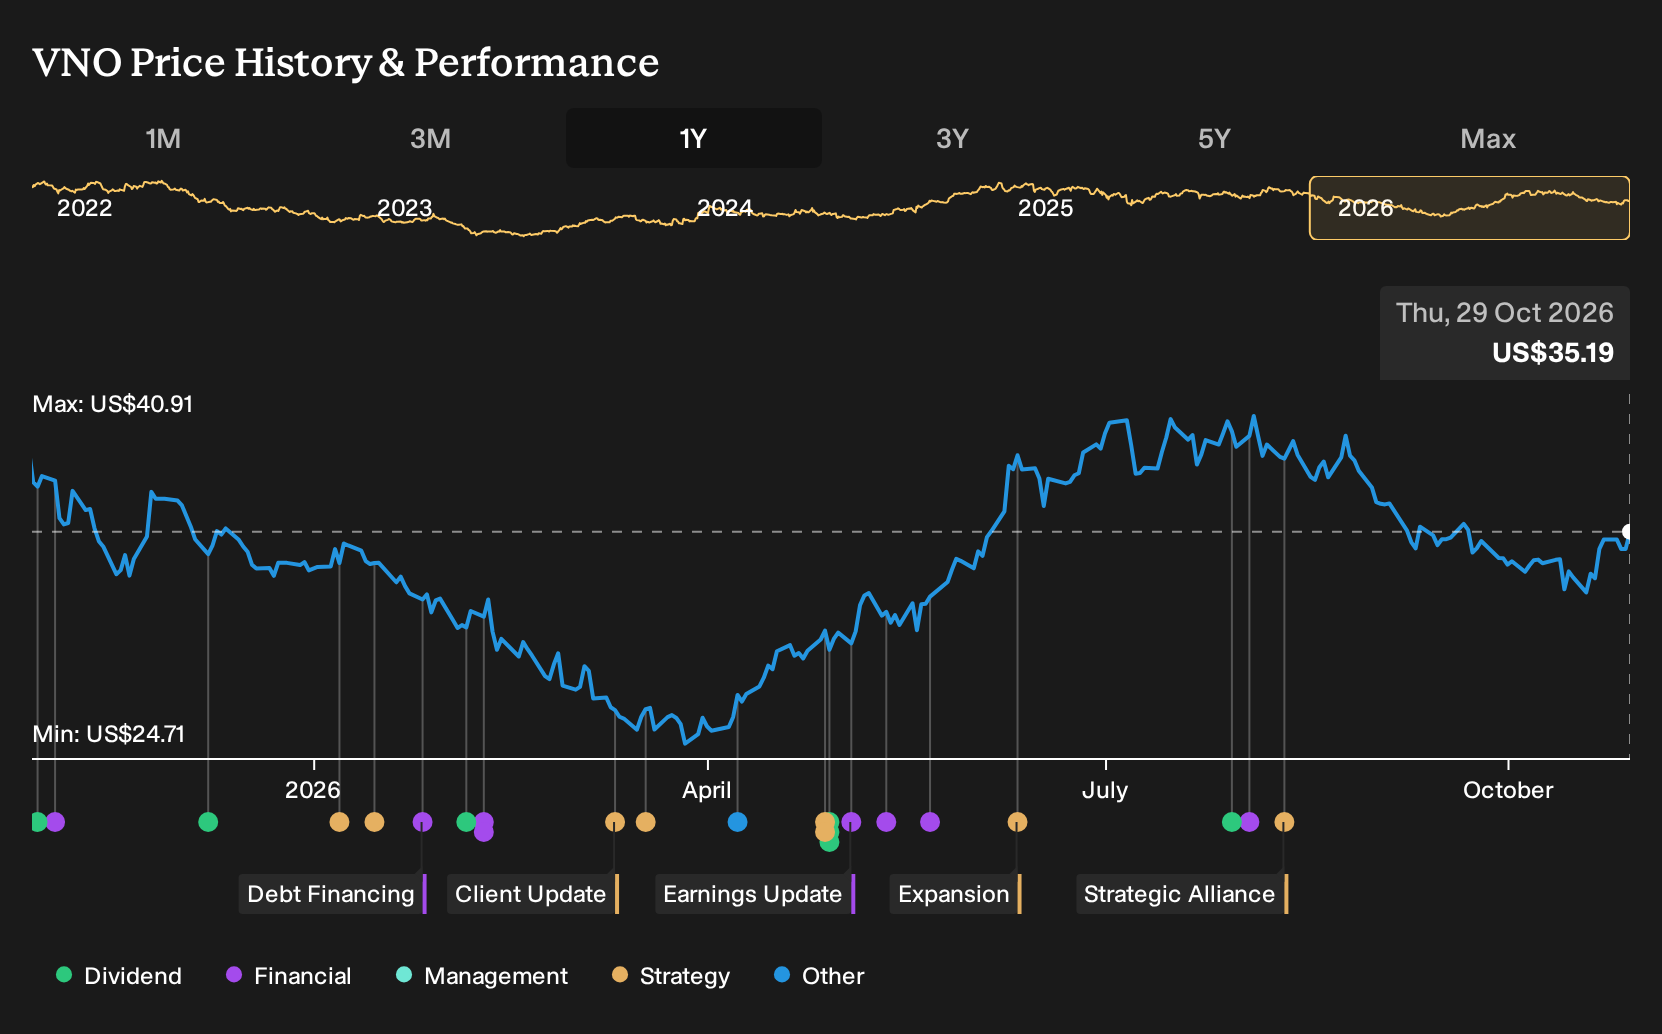
- Vornado Realty Trust declared quarterly preferred dividends across multiple series, with payments scheduled for January 4, 2027 to holders of record on December 15, 2026. Analysts currently expect September quarter earnings of $0.64 per share on revenue of $471.93 million.
- The combination of confirmed preferred payouts and expectations for higher quarterly earnings and revenue highlights how Vornado Realty Trust is balancing income commitments with operating performance as it works through large redevelopment and leasing projects.
- We will examine how Vornado Realty Trust’s investment narrative is affected by expected earnings strength supported by the Citadel lease and construction loan.
Vornado Realty Trust Investment Narrative Recap
To own Vornado Realty Trust, you need to believe its Manhattan focused redevelopment story can convert premium office demand and a signed but not occupied rent pipeline into steadier cash generation. The preferred dividend declaration signals a willingness to keep honoring capital commitments, yet does not fundamentally change that core thesis.
The key near term swing factor remains lease up and rent commencement at projects like PENN and 350 Park, especially as interest expense and tenant improvement outlays stay heavy. The biggest risk is that higher funding costs and elevated concessions keep free cash flow thin, which could slow progress on that earnings uplift.
The preferred dividend announcement across Series A, L, M, N and O matters because it sits directly on top of that funding and execution story. Regular payments on these securities mean a fixed claim on cash that comes before common shareholders and competes with redevelopment spending.
For you as a potential investor, the question is whether expected earnings of US$0.64 per share on US$471.93 million of quarterly revenue leave enough room to comfortably cover interest, preferred payouts and heavy project budgets. If leasing at assets like 350 Park and PENN tracks expectations, those cash outflows become easier to absorb over time.
Vornado Realty Trust Long Term Earnings Set Up
Vornado Realty Trust's longer term story leans heavily on what analysts are building into their models for revenue growth, margin improvement and earnings by the late 2020s. Those assumptions give a sense of how much operating progress would need to show up in the numbers for the current redevelopment and leasing plan to look justified.
Analysts are incorporating revenue growth of 4.9% per year over the next three years, alongside an increase in profit margin from 0.3% to 7.4% by 2029. On these inputs, earnings today of US$5.8 million are projected to reach US$160.9 million, which is roughly a 27x increase in profit and would equate to earnings per share of US$0.94 in 2029.
Those same forecasts imply that by 2029 Vornado Realty Trust would be generating about US$2.2b of revenue and US$160.9 million of earnings. For an investor weighing the stock today, the core question is whether the PENN District projects, 350 Park and assets like Park Avenue Plaza can realistically support that level of scale and profitability without stretching the balance sheet too far.
Vornado Realty Trust's narrative uses projections of about US$2.2b of revenue and US$160.9 million of earnings by 2029. This assumes yearly revenue growth of 4.9% and an earnings increase from US$5.8 million today to US$160.9 million at the forecast point.
Uncover how Vornado Realty Trust's fair value indicates a 13% potential upside to its current price before the market closes this discount.
Exploring Other Perspectives
One point the more cautious analysts keep stressing is balance sheet risk at Vornado Realty Trust. They see slower revenue growth of about 3.4% a year and 2029 earnings nearer US$154.0 million, instead of US$160.9 million. They also worry that high leverage plus these fresh preferred dividends could push future estimates in either direction once the news is fully reflected.
Explore 3 other Vornado Realty Trust fair value estimates, including one that suggests as much as 12% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vornado Realty Trust research is our analysis highlighting 1 key reward and 6 important warning signs that could impact your investment decision.
- See our latest analysis for Vornado Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vornado Realty Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vornado Realty Trust?
If you want to round out your watchlist beyond Vornado Realty Trust, the Simply Wall St Screener can help you quickly sort through stocks that fit very different goals, from income resilience to balance sheet strength or future growth potential.
- For investors who want potential upside while still paying close attention to quality and valuation, scan a curated set of 30 high quality undervalued stocks that already clear fundamental checks.
- If capital preservation and financial strength matter most to you, filter for companies on our list of solid balance sheet and fundamentals (23 results) to see which businesses carry stronger buffers against shocks.
- For those who like finding tomorrow's stories before they become crowded trades, use the 18 high quality undiscovered gems to surface stocks with solid fundamentals that have not yet drawn broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com