


- Japan Tobacco lifted its full year earnings forecast after a 13% rise in third quarter adjusted operating profit, helped by higher tobacco pricing, reduced risk product demand and a weaker yen, while keeping its planned annual dividend.
- Reduced risk products remain a key focus, with Ploom led heated tobacco and other alternatives seeing a 26.6% increase in sales volume in the recent quarter.
- We will look at how Japan Tobacco's investment narrative is influenced by the upgraded full year outlook driven by stronger heated tobacco.
Scan how Japan Tobacco's upgraded guidance and heated tobacco momentum compare with other income plays by running your eye over the 30 dividend fortresses.
Japan Tobacco Investment Narrative Recap
To own Japan Tobacco, you need to be comfortable with a business that still leans heavily on combustible pricing while trying to build a second profit engine in reduced risk products. The upgraded full year guidance reinforces that near term earnings are tracking ahead of earlier expectations, helped by heated tobacco and currency, but it does not change the basic thesis.
The key short term catalyst remains execution in Ploom and other reduced risk products across priority markets, where sustained volume and share gains could support mix and margin. The largest immediate risk is that higher excise or weaker consumer wallets in markets like Russia or Turkey pressure combustible volumes and limit the cushion that pricing currently provides.
The most relevant announcement here is the revised earnings outlook itself. Management lifted full year guidance after adjusted operating profit in the third quarter rose 13%, supported by tobacco pricing, stronger reduced risk product demand and a weaker yen, while keeping the annual dividend plan unchanged.
For you, that combination ties straight back to the catalysts and risks. Stronger Ploom volumes, with reduced risk product sales up 26.6%, suggest progress toward the planned ¥800b RRP investment program from 2026 to 2028. However, the cash commitment required and ongoing dependence on combustible markets mean execution quality and tax or macro shocks remain central to the story.
What The Analyst Scenario Implies For Japan Tobacco
Analysts sketch a path for Japan Tobacco that leans on both steady revenue expansion and a meaningful step up in profitability. Their models assume revenue grows at 5.5% a year over the next three years and that profit margins rise from 16.4% today to 19.9% in the same window. Forecast earnings sit at ¥867.8b by about 2029 compared with earnings today of ¥610.0b, which implies an earnings increase of roughly ¥257.8b. The forecast period is not risk free, given the spread between the most optimistic profit view of ¥1,022.9b and the most cautious estimate of ¥722.9b. Even so, it gives a sense of the range of expectations currently embedded in the share price.
Japan Tobacco's narrative projects ¥4,368.5b revenue and ¥867.8b earnings by 2029. This requires 5.5% yearly revenue growth and an earnings increase of roughly ¥257.8b from ¥610.0b today.
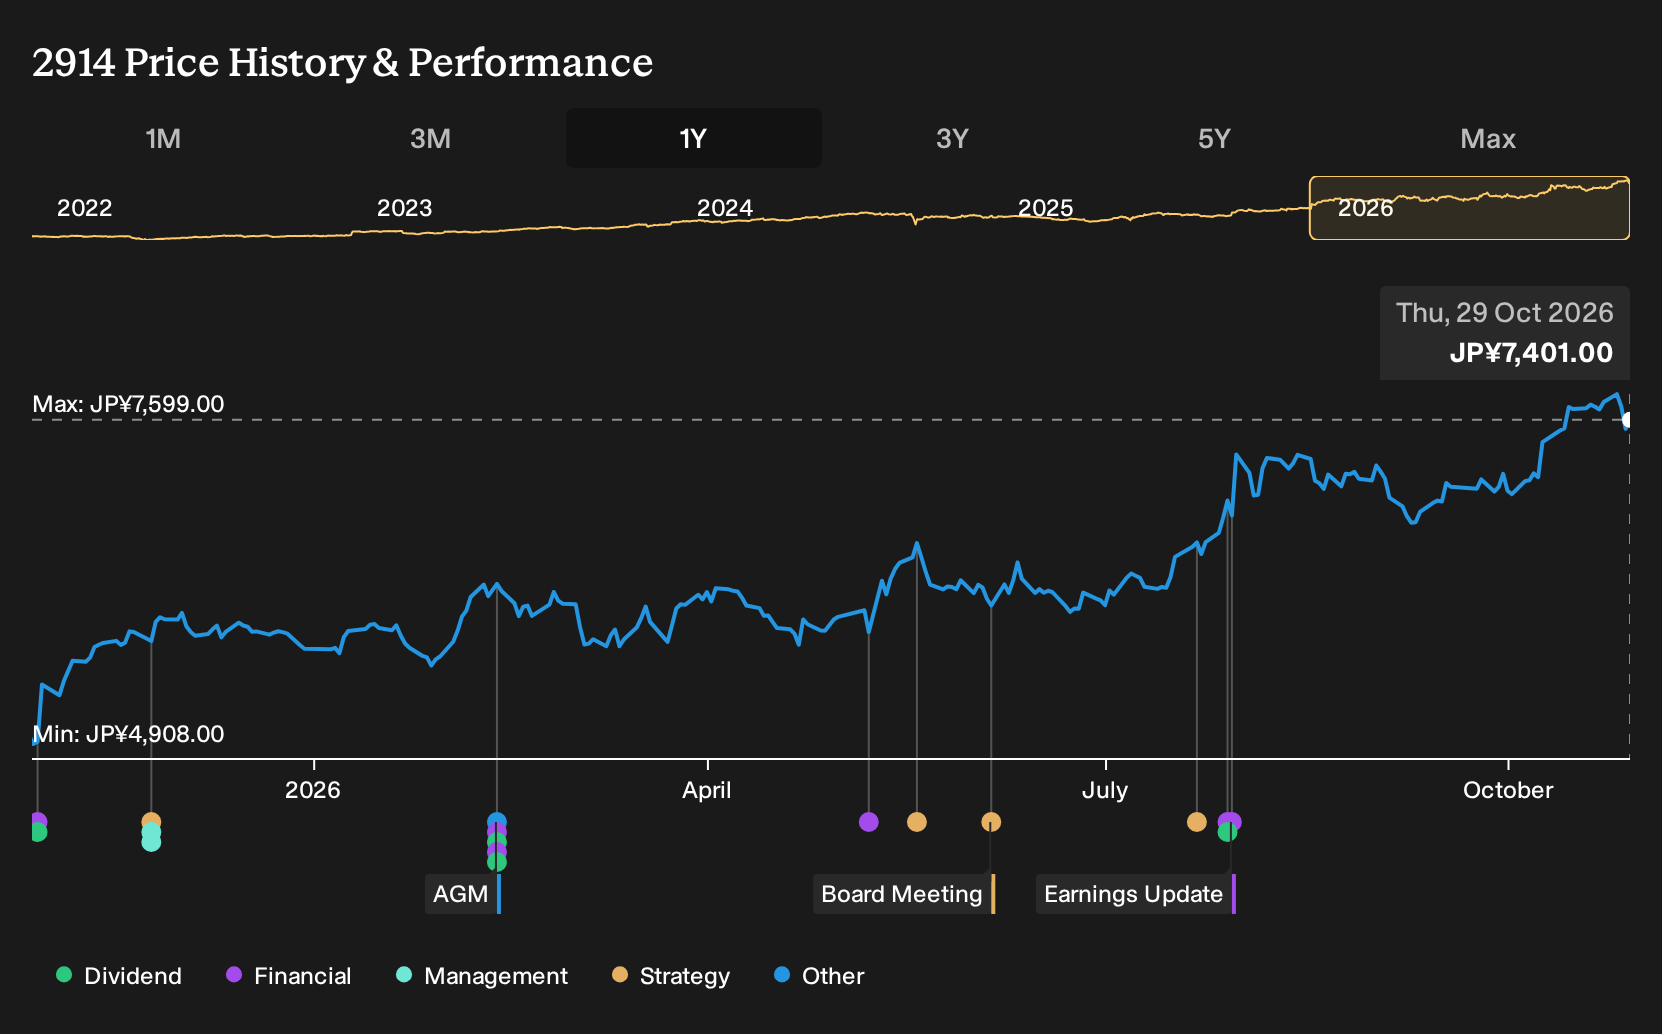
The same scenario feeds directly into how the equity is framed on valuation. To line up with the analyst case, the assumptions include those ¥867.8b of earnings in 2029 and a P/E of 18.1x on that profit, compared with 21.8x today and an industry level of 22.1x. Consensus fair value sits at ¥7,483.36 per share, with individual targets running from ¥6,400.0 to ¥8,700.0, against a current share price of ¥7,504.0 as at late October 2026. The 0.3% gap between the live quote and the central target indicates that the market price is close to the average analyst view on future revenue, Ploom execution and the planned ramp in reduced risk product spending.
Uncover why Japan Tobacco's fair value indicates a valuation that is in line with its current price.
Exploring Other Perspectives
You might see this earnings upgrade and focus on Japan Tobacco’s reduced risk push, while the most optimistic analysts zero in on faster Ploom adoption. Before this news, they were already pencilling in ¥4,798.4b of revenue and ¥1,021.9b of earnings by 2029. Those assumptions may shift, so it can be helpful to compare several viewpoints before deciding what feels reasonable.
Explore another Japan Tobacco fair value estimate, including one that suggests as much as 56% potential increase from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Japan Tobacco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Japan Tobacco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Japan Tobacco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Japan Tobacco?
If this Japan Tobacco update has sharpened your thinking about income, risk and where future earnings might come from, it can be helpful to line it up against other opportunities using the Simply Wall St Screener.
- For readers who care most about resilience and want balance sheets that can absorb shocks, take a look at the list of solid balance sheet and fundamentals (23 results).
- If value is the priority and you are hunting for quality businesses that the market may be overlooking, scan through the 71 high quality undiscovered gems.
- When income is front and centre and you want yields backed by fundamentals instead of hope, compare Japan Tobacco with the 30 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com