


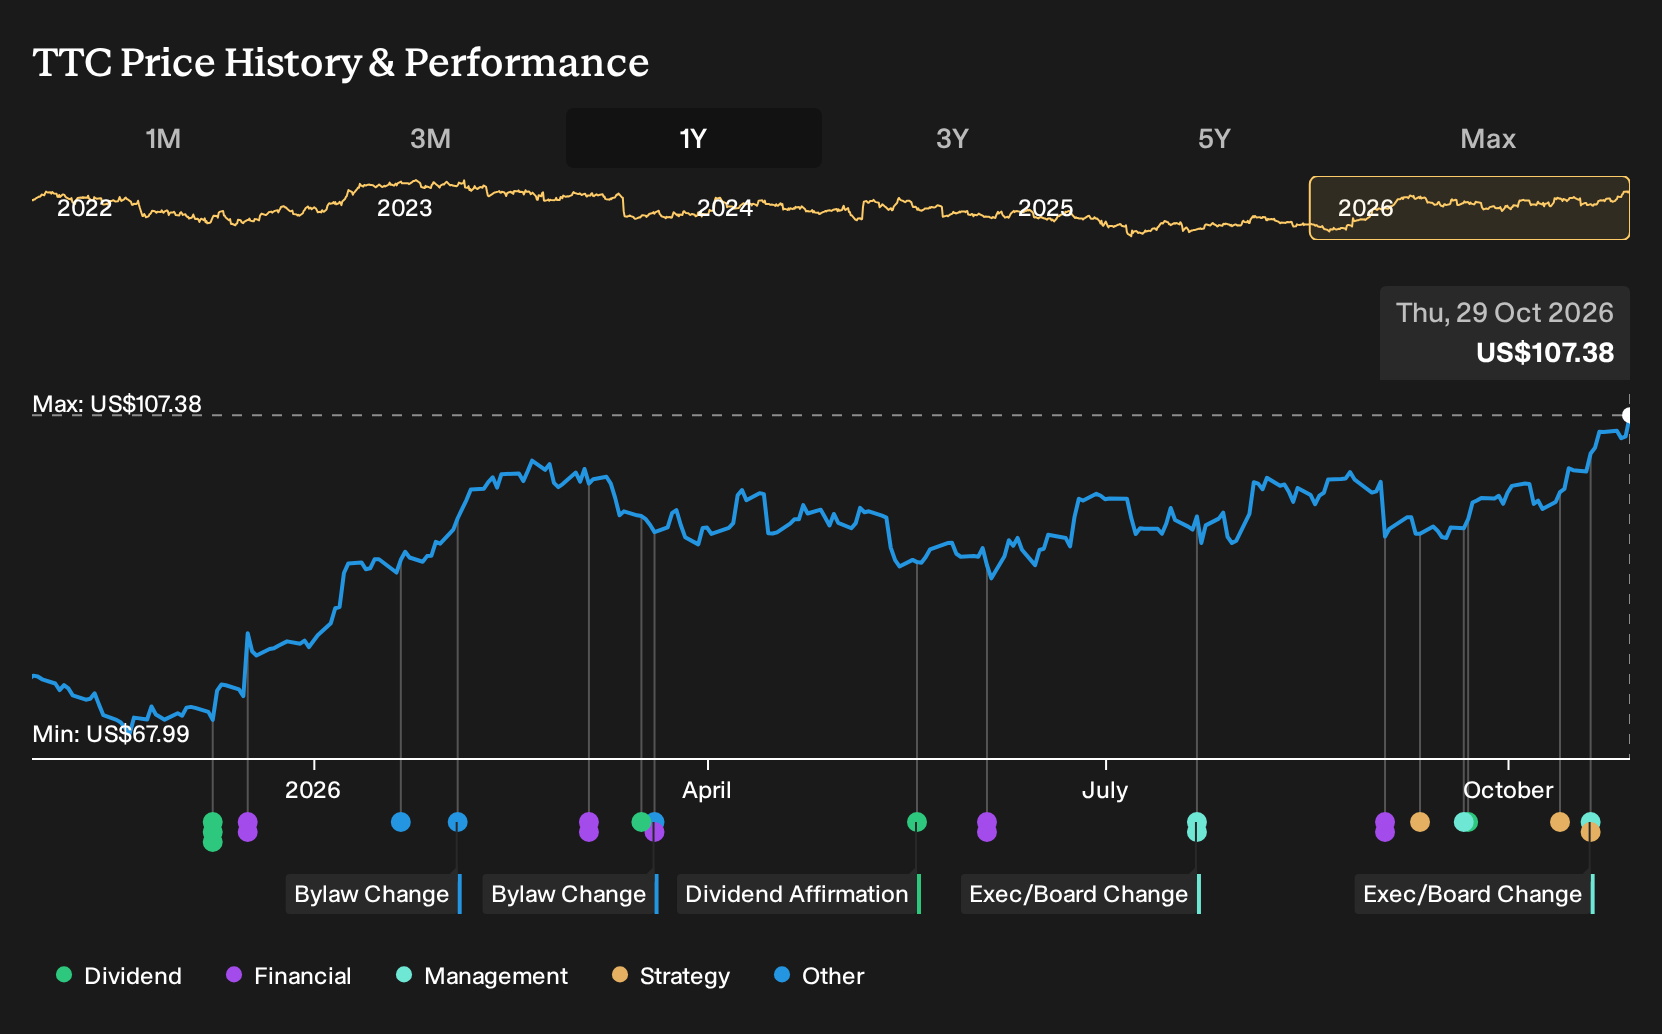
- The Toro Company recently appointed Neal M. Lackritz as its first chief technology officer and introduced the OneFleet program for qualifying fleet customers, offering exclusive savings across multiple brands and equipment categories.
- The combination of a unified technology leader and a cross-portfolio fleet program suggests Toro is focusing on execution around advanced equipment, autonomous systems and broader wallet share from existing professional customers.
- This development may influence how Toro's investment narrative is evaluated as OneFleet affects fleet economics across the portfolio.
Scan beyond Toro and see how other equipment makers with tech heavy fleets are positioned by reviewing our hand picked 93 robotics and automation stocks for your watchlist.
Toro Investment Narrative Recap
Toro asks you to believe that higher value turf, irrigation and underground equipment, paired with cost discipline, can offset slower forecast top line expansion of 3.3% a year and a high debt load. The CTO hire and tech focus speak directly to that story. The near term hinge point remains whether AMP productivity gains and channel normalization keep margins and cash generation on track.
The biggest risk is that structural profitability proves less durable than recent quarters imply, especially if efficiency wins fade while the stock trades on a 28x P/E above the Machinery average. The new technology structure does not remove that concern, but it gives management one more lever to support returns.
The creation of Toro’s chief technology officer role ties directly into previously flagged catalysts around smart, connected and autonomous turf and irrigation products. Those offerings, including autonomous golf units already in the field and the GeoLink Autonomous Fairway Mower, need tight coordination between engineering, software and commercial teams to scale effectively.
Centralizing global engineering and the Center for Technology, Research and Innovation under one leader could help execution around platform reuse, electronics and connected features. For you, the key watchpoints are simple: Do new autonomous, electrified and connected models help sustain earnings growth while debt remains elevated, and do they support the margin profile that current expectations already assume?
Toro's current analyst narrative points to about US$5.2b in revenue and US$554.9m in earnings by 2029, based on 3.4% yearly revenue growth and an earnings increase of roughly US$191.6m from the current US$363.3m base.
Discover why Toro's fair value indicates a 3% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Some analysts see Toro’s tech push very differently. The most pessimistic group worries that heavier spending on autonomous and connected gear raises costs if customer adoption stays slow. Before this CTO and OneFleet news, they were penciling in 3.7% yearly revenue growth to about US$5.2b and earnings of US$546.1m by 2029, which is a cooler story than consensus. That spread in expectations shows how wide opinions can run, so it makes sense to compare several viewpoints before deciding how this update might reshape your own Toro thesis.
Explore 2 other Toro fair value estimates, including one that suggests it could be worth just $111.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toro research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Toro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toro?
Once you have a view on Toro, it can help to compare it with other businesses that share some of the same qualities you care about, whether that is value, resilience or income.
- For readers focused on quality at a reasonable price, check out a curated 30 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- If stability and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (23 results) that can help you stress test ideas against tougher conditions.
- Income oriented investors who want yield alongside business resilience can review a focused 7 dividend fortresses that screens for higher payouts with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com