


Fluidra (BME:FDR) just reported nine month 2026 earnings, giving investors fresh numbers on sales, profit and guidance. The update pairs higher revenue with lower net income and reaffirmed full year targets.
The recent earnings release comes after a mixed year for the Fluidra share price. A 1 day share price return of 1.07% and a 7 day share price return of 5.06% hint at improving short term momentum, while the year to date share price return is down 19.53% and the 1 year total shareholder return has fallen 23.38%, even though the 3 year total shareholder return is up 18.66%.
Scan handpicked pool and water infrastructure peers showing resilient earnings trends and pricing power using our list of solid balance sheet and fundamentals (207 results) to see how Fluidra compares on quality and balance sheet strength.
Fluidra now pairs firmer earnings execution with a share price that is still down sharply over 12 months. Does that mix tilt the risk reward toward new buyers, or does it leave more downside than upside from here?
Most Popular Narrative: 27% Undervalued
Against Fluidra's last close at €18.91, the most followed valuation narrative points to a fair value of about €26.03. This frames the current pullback as a sizeable gap between price and what the underlying business might justify when discounted at 10.0%.
The multi year efficiency and footprint program, including plant closures, the Tangiers facility and targeted headcount reductions that have already produced about €15 million of savings in 2026, is set up to further lower the cost base and support net margin resilience as additional actions flow through.
See why 3 investors see Fluidra as 27% undervalued.
Result: Fair Value of €26.03 (UNDERVALUED)
Still, the narrative can crack if weak new pool construction persists for longer than analysts expect, or if high restructuring costs keep weighing on reported profit.
Find out about the key risks to this Fluidra narrative.
Another View: What Fluidra’s P/E Is Telling You
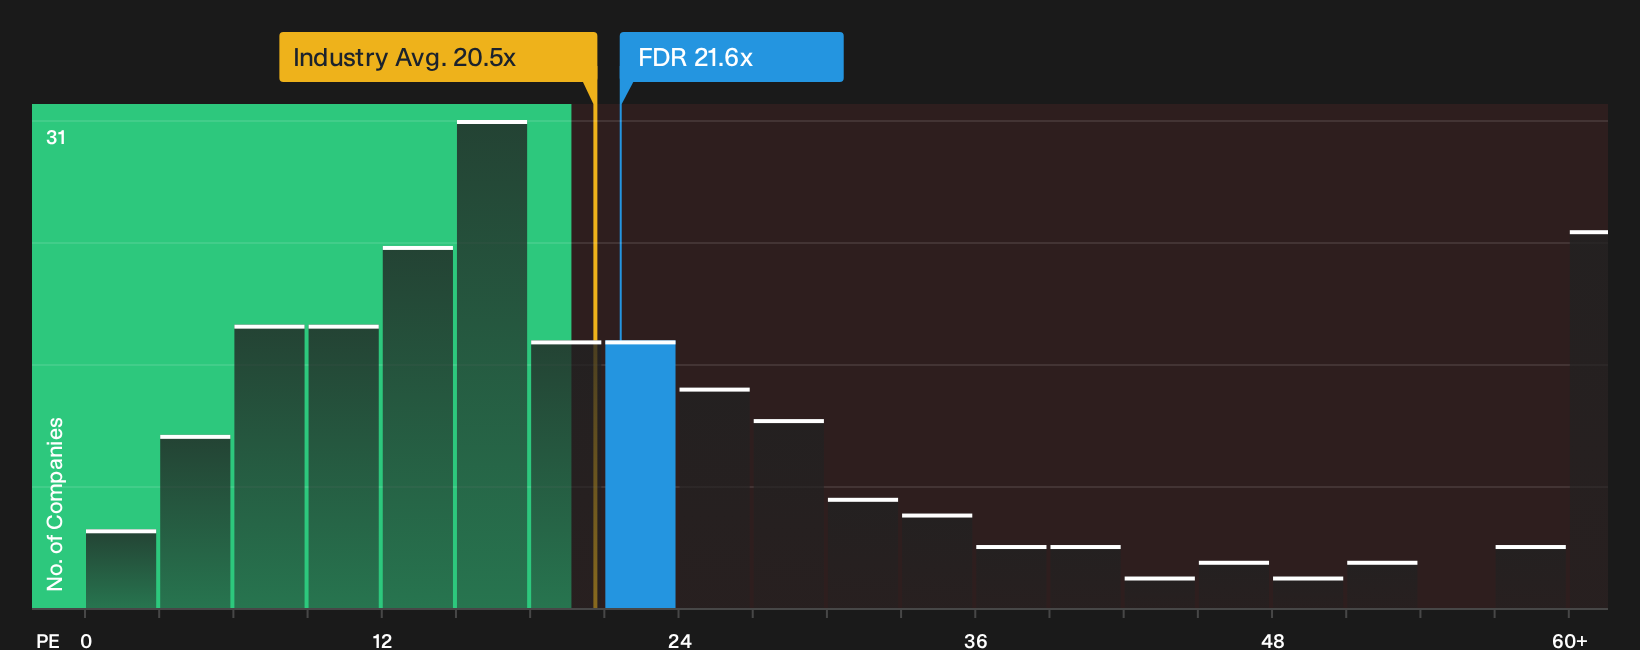
That 27% undervaluation story leans heavily on future cash flows. Yet on a plain P/E basis, Fluidra trades at 21.6x earnings, above both its peer group at 12.9x and the wider European Machinery sector at 20.3x, while our fair ratio is 23.5x.
Investors therefore face a trade off between a stock that appears inexpensive relative to this fair ratio and expensive relative to peers. The key question is which reference point is more appropriate for the level of risk being taken here: the broader peer group, or the fair ratio that the market may eventually converge toward.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Fluidra often create the most interesting setups. Move quickly, review the details, and weigh both sides for yourself with the 4 key rewards and 2 important warning signs.
Looking for more Fluidra sized investment ideas?
If Fluidra has your attention, do not stop here. Use the Simply Wall Street Screener to spot fresh opportunities before the wider market catches on.
- Target dependable quality by scanning companies with strong finances and durable business models through the list of solid balance sheet and fundamentals (207 results).
- Hunt for mispriced opportunities by focusing on companies that combine quality fundamentals with attractive valuations in the 195 high quality undervalued stocks.
- Build a cash flow focused watchlist by zeroing in on income ideas with resilient payout potential using the 228 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com