


- Dampskibsselskabet Norden reported Q3 2026 sales of US$1,114.9 million and net income of US$53.9 million, with basic EPS from continuing operations at US$2, alongside higher nine month revenue and profit versus the prior year.
- The combination of larger top line and higher earnings over both the quarter and year to date points to operating leverage in Dampskibsselskabet Norden's dry cargo and tanker activities, with improved profitability per share a central theme.
- We will now look at how this stronger earnings per share profile could reshape Dampskibsselskabet Norden's existing investment narrative.
Compare how Dampskibsselskabet Norden's earnings story aligns with other shipping and capital-intensive operators by reviewing our curated list of list of solid balance sheet and fundamentals (207 results)
Dampskibsselskabet Norden Investment Narrative Recap
Dampskibsselskabet Norden appeals to shareholders who buy into a freight operator that leans on asset agility, purchase options and long coverage in tankers to smooth out a choppy shipping cycle. The latest quarter, with higher sales and net income versus a year ago, supports that story but does not erase exposure to freight volatility or bunker and regional cost swings.
In the near term, the key catalyst is how efficiently the firm converts this stronger earnings per share profile into cash while ramping its multipurpose and Handysize fleet. The main risk is that softer utilization or weaker freight markets meet rising capital needs, which could pressure margins and dilute returns despite the recent EPS improvement.
The Q3 2026 earnings release is the most relevant update here. Dampskibsselskabet Norden reported quarterly sales of US$1,114.9 million and net income of US$53.9 million, with basic EPS from continuing operations at US$2. For the first nine months, sales were US$2,975.8 million and net income reached US$165.9 million, with basic EPS at US$5.9.
Those figures show that, at least through September 2026, the business is generating meaningfully higher profit per share than a year earlier. That is important for the current catalyst, which is demonstrating that the dry cargo operations, tanker coverage and fleet build out can support more stable earnings. It also frames the risk that high non cash earnings and capital demands could limit how much of this reported profitability ultimately reaches shareholders as resilient free cash flow.
Dampskibsselskabet Norden's current earnings sit at US$99.0 million, with analysts expecting profit to reach US$33.9 million in 2029 on forecast revenues of US$2.3b. This outlook assumes revenue falls by 9.4% a year and earnings decline by US$65.1 million by the 2029 estimate year.
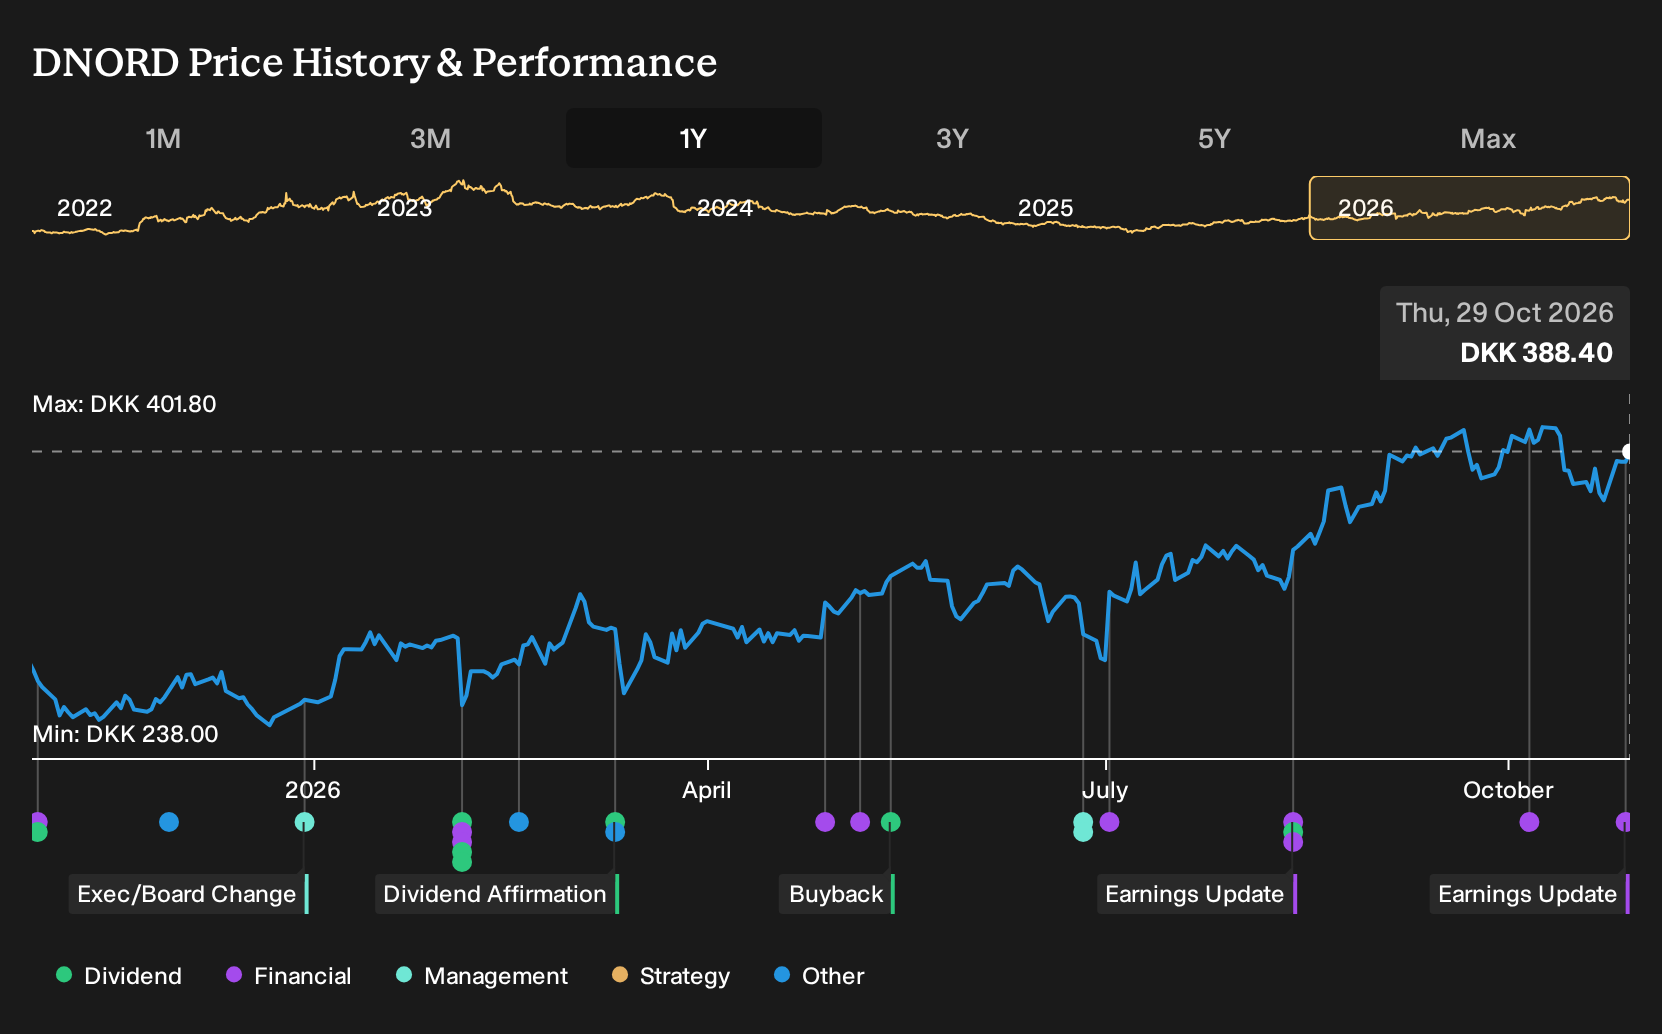
Uncover how Dampskibsselskabet Norden's fair value indicates a 16% potential downside to its current price, a premium that may not be sustained.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$195 to US$426 per share, with one retail forecast more than double the lowest. That spread sits beside Dampskibsselskabet Norden's recent Q3 earnings update, so you are weighing fresh profit data against older models and sharply different opinions.
Explore 3 other Dampskibsselskabet Norden fair value estimates, including one that suggests as much as 50% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dampskibsselskabet Norden research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dampskibsselskabet Norden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dampskibsselskabet Norden's overall financial health at a glance.
Looking for more Dampskibsselskabet Norden style ideas?
If Dampskibsselskabet Norden's mix of earnings power and capital intensity has your attention, it can help to line it up against other candidates that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricings with fundamentals to back them up, scan through 195 high quality undervalued stocks and see which stocks match your criteria.
- If resilience matters more than excitement, filter for companies with sturdier financial profiles through the 229 resilient stocks with low risk scores and compare how they stack up on debt and volatility.
- Income focused investors can search for yield opportunities using the 228 dividend fortresses and then judge which payouts align with their risk tolerance and cash flow needs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com