


Floor & Decor Holdings has seen its share price fall a long way over recent years, even as the business continues to focus on earnings and expansion. That drop raises a simple question for investors who follow Floor & Decor, whether the current price can be squared with what the company is actually earning today.
- Over the past 5 years the stock has fallen 64.9%, which puts the spotlight firmly on whether its earnings now justify even this lower valuation.
- Recent earnings growth alongside ongoing store openings can support expectations for future profit streams, which feeds directly into how much investors may be willing to pay for those earnings.
- Your read on Floor & Decor Holdings is one view; the desks covering it have another. See what analysts think Floor & Decor Holdings's shares could be worth.
The issue now is whether Floor & Decor's current market value is reasonable when judged purely against the earnings it is generating.
If you are weighing Floor & Decor Holdings against other earnings focused opportunities, it can help to compare it with companies surfaced by our 30 high quality undervalued stocks
Is Floor & Decor Holdings Getting Expensive on Earnings?
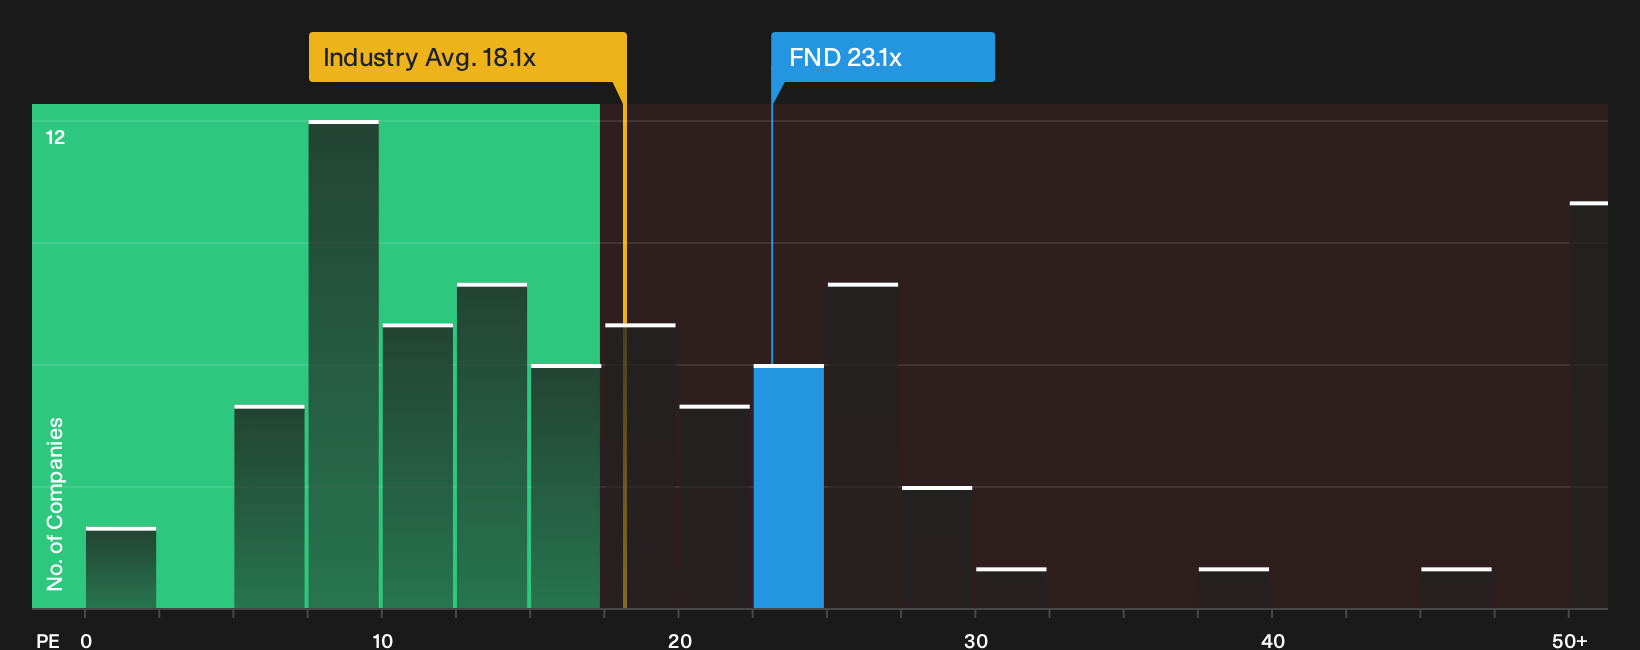
The P/E ratio fits Floor & Decor Holdings because investors are focused on its earnings power rather than dividends. On that yardstick, the stock trades at about 23.1x earnings, which is higher than both the specialty retail industry average of roughly 18.1x and a peer group around 11.8x. That gap means the market is attaching a richer price tag to each dollar of Floor & Decor's profit than to many comparable retailers.
Based on a tailored fair multiple that reflects the company's specific growth profile, margins, size and risks, the current 23.1x P/E screens as overvalued rather than cheap. Because recent Q3 results showed stronger earnings per share despite softer comparable sales, the current valuation suggests investors are already paying up for that resilience. If you hold or are considering Floor & Decor stock, the key question is whether the business can continue to justify paying this kind of premium for its earnings. Explore the numbers behind Floor & Decor Holdings's P/E valuation.
The Floor & Decor Holdings Narrative: What Would Justify Today's Price?
Narratives on Floor & Decor Holdings pick up where this valuation puzzle leaves off by spelling out what would need to happen to future growth, margins and earnings for the stock to be worth meaningfully more or materially less than it trades for today, and setting out the assumptions behind each fair value view so you can weigh those inputs against actual results as they arrive. They sit on Simply Wall St's Community page and give you a structured way to stress test your own expectations.
Community views on Floor & Decor split between those who think the earnings multiple still undershoots the story and those who see margin risk already fully reflected.
Bull case: 11% undervalued
"Deepening engagement with Pro customers, who generated about 55% of Q2 FY2026 sales and grew roughly 4% year over year with installation materials outperforming…"
Discover why this Narrative puts Floor & Decor Holdings at 11% undervalued.
Bear case: 29% overvalued
"New distribution centers in Seattle and Baltimore are expected to weigh on gross margin by about 70 to 100 basis points in FY25 and FY26 as they ramp…"
Explore why this Narrative puts Floor & Decor Holdings at 29% overvalued.
Floor & Decor Holdings: what the market is already assuming about tomorrow's earnings power
Everything so far has focused on what Floor & Decor looks like today. However, analyst models outline where revenue, profit and store economics could be a few years from now, giving you a separate yardstick to compare with the current valuation. Explore where analysts expect Floor & Decor Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com