


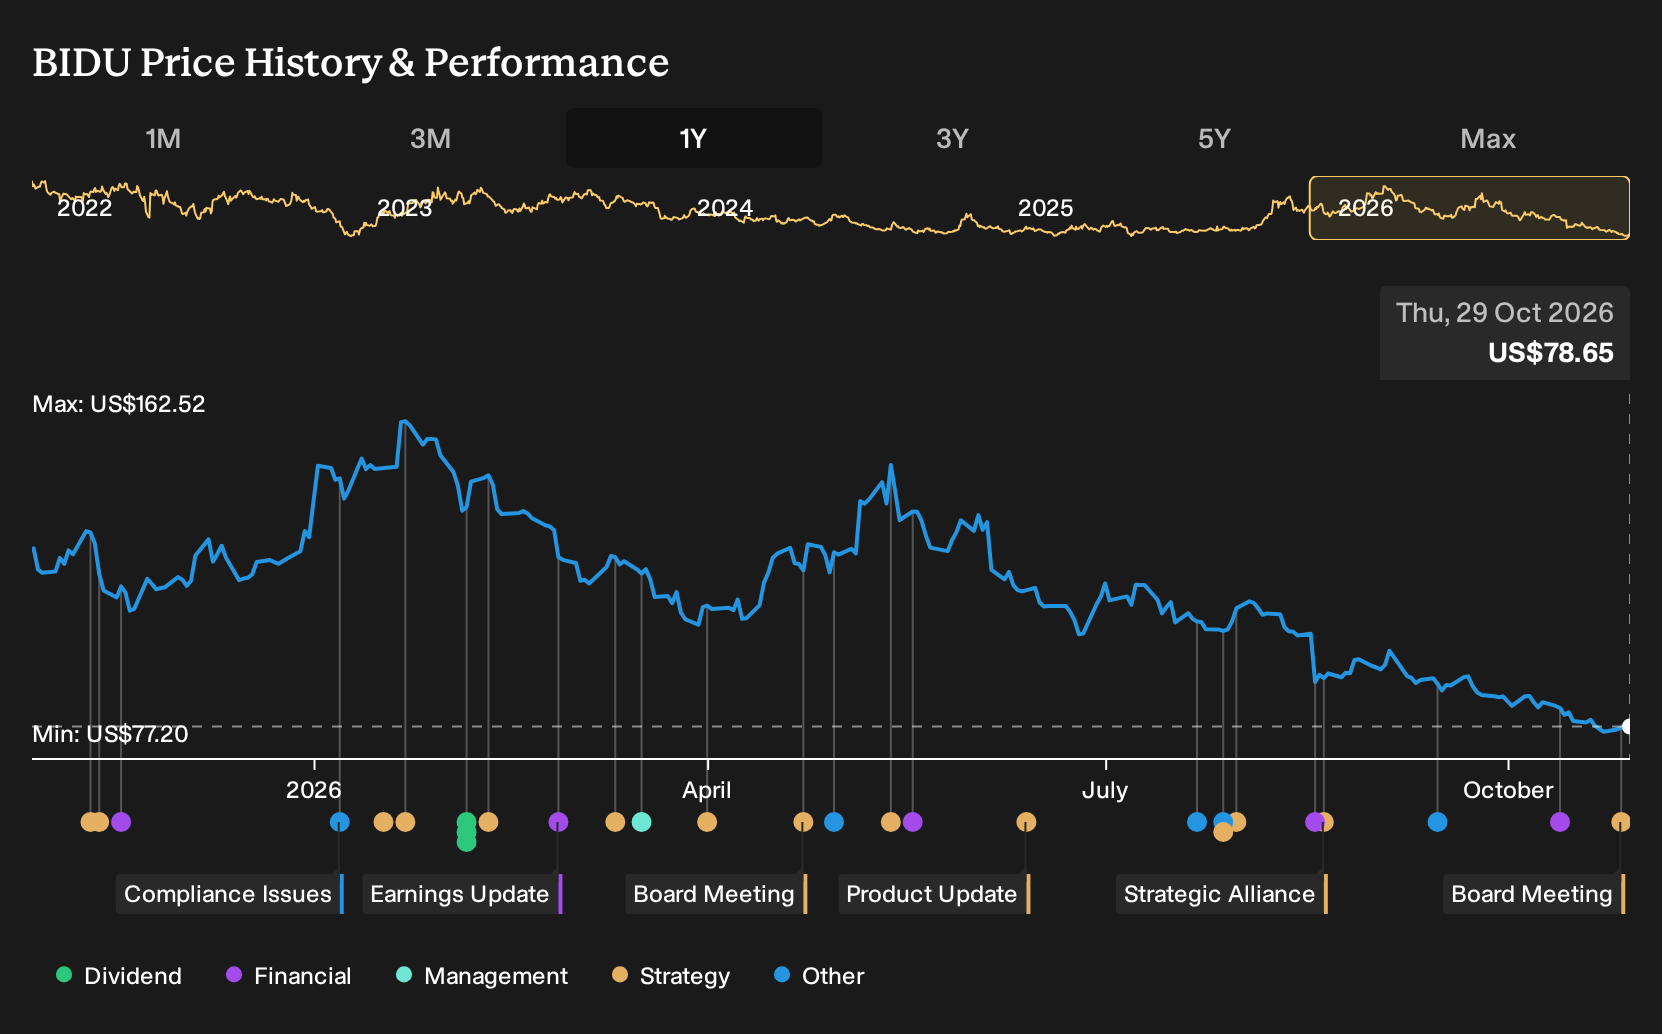
- Baidu is facing a securities class action filed by Levi & Korsinsky, LLP that accuses the company of misrepresenting its shift from legacy search advertising to AI cloud services after reported quarter over quarter revenue declines in both core AI powered operations and older advertising lines.
- The complaint links Baidu's operational transition issues directly to alleged information gaps around weakening AI driven and traditional businesses, while analysts have also cut earnings estimates and now expect lower earnings per share this fiscal year.
- We will now see how Baidu's investment narrative around AI driven growth holds up against allegations of undisclosed operational pressures in its transition.
Balance out Baidu's legal and earnings uncertainty by scanning 30 resilient stocks with low risk scores, which may offer more resilient profiles if you want steadier exposure alongside higher headline risk situations.
Baidu Investment Narrative Recap
Baidu is still a bet on whether AI cloud, autonomous driving and AI powered search can carry the business while legacy online marketing stays under pressure. For you to be comfortable as a shareholder, that AI mix shift needs to translate into cleaner earnings and fewer one off hits such as the RMB 16.2b impairment on old infrastructure.
The lawsuit and recent earnings estimate cuts mainly hit confidence around that transition and around disclosure quality. The most important near term catalyst remains execution in AI cloud and monetising ERNIE and Apollo Go. The biggest risk is that revenue softness, further write downs or delayed AI monetisation keep Baidu unprofitable for longer.
The earnings revisions tied to Baidu, including the lower consensus for this fiscal year and the Zacks Rank 5 label, are closely linked to the same issues raised in the lawsuit. Both point at pressure on AI operations and older ads businesses at the same time, which raises the bar for any improvement in reported profitability.
For you as an investor, that announcement matters because it highlights how sensitive the story is to each quarterly print. If operating performance in AI cloud or Apollo Go does not offset weaker marketing and higher AI spending, estimate cuts can continue. That would keep sentiment fragile even if long term AI catalysts remain intact.
Baidu Forecasts And What The Numbers Assume
Baidu's narrative projects CN¥154.7b revenue and CN¥15.6b earnings by 2029. This implies revenue growth of 6.7% per year and an earnings swing of about CN¥20.3b from a CN¥4.7b loss today to the projected profit level.
Uncover why Baidu's fair value indicates a 75% potential upside to its current price, which could narrow quickly as sentiment around Baidu's AI thesis resets.
Exploring Other Perspectives
One alternate angle on Baidu focuses on the risk that AI spending fails to translate into cleaner profits. The most pessimistic analysts were penciling in CN¥143.6b of revenue and CN¥14.8b of earnings by 2029 before this lawsuit surfaced. That is already a cooler story than consensus, and you should expect those views to evolve as the legal case unfolds.
Explore 4 other Baidu fair value estimates, including one that suggests it could be worth just $132.69!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Baidu research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Baidu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baidu's overall financial health at a glance.
Looking for more Baidu investment ideas and comparables?
If Baidu's mix of AI ambition and legal risk feels concentrated for your portfolio, consider broadening your watchlist with a few targeted filters that surface different types of listed businesses.
- For investors who want income as well as potential capital gains, scan a curated set of higher yielding payers through 7 dividend fortresses.
- If resilience and balance sheet strength matter most to you, focus on companies screened for low leverage and solid fundamentals with the list of solid balance sheet and fundamentals (23 results).
- When you want to hunt for opportunities that are less picked over by the market, start with a focused universe of 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com