


- GATX reported Q3 2026 revenue of US$598 million and net income of US$105.2 million, with diluted EPS from continuing operations at US$2.92. The company now expects 2026 earnings to modestly exceed the prior guidance high end of US$10.30 per share.
- Stronger leasing fundamentals, including 98.4% Rail North America utilization and successful integration of acquired rail assets, are contributing to higher earnings guidance and indicate how GATX is monetizing its expanded fleet and fee base.
- We will now look at how GATX's raised full year earnings outlook could reshape its investment narrative for long term investors.
Scan beyond GATX's upgraded outlook and line up other rail and industrial leasing stocks with resilient earnings profiles by reviewing the list of solid balance sheet and fundamentals (23 results).
GATX Investment Narrative Recap
To own GATX, you need to believe the high utilization, long lease terms and diversified leasing platforms can keep turning a largely fixed asset base into consistent earnings. The Q3 results and raised 2026 guidance lean on that idea. The near term swing factor still looks like lease demand and pricing in Rail North America.
The biggest operational risk has not disappeared. Management still depends on timing sensitive remarketing gains and meaningful leverage. If used railcar demand slows or funding costs climb, earnings could feel lumpier even with healthy utilization. The new guidance upgrade does not fully remove that concern for the next year.
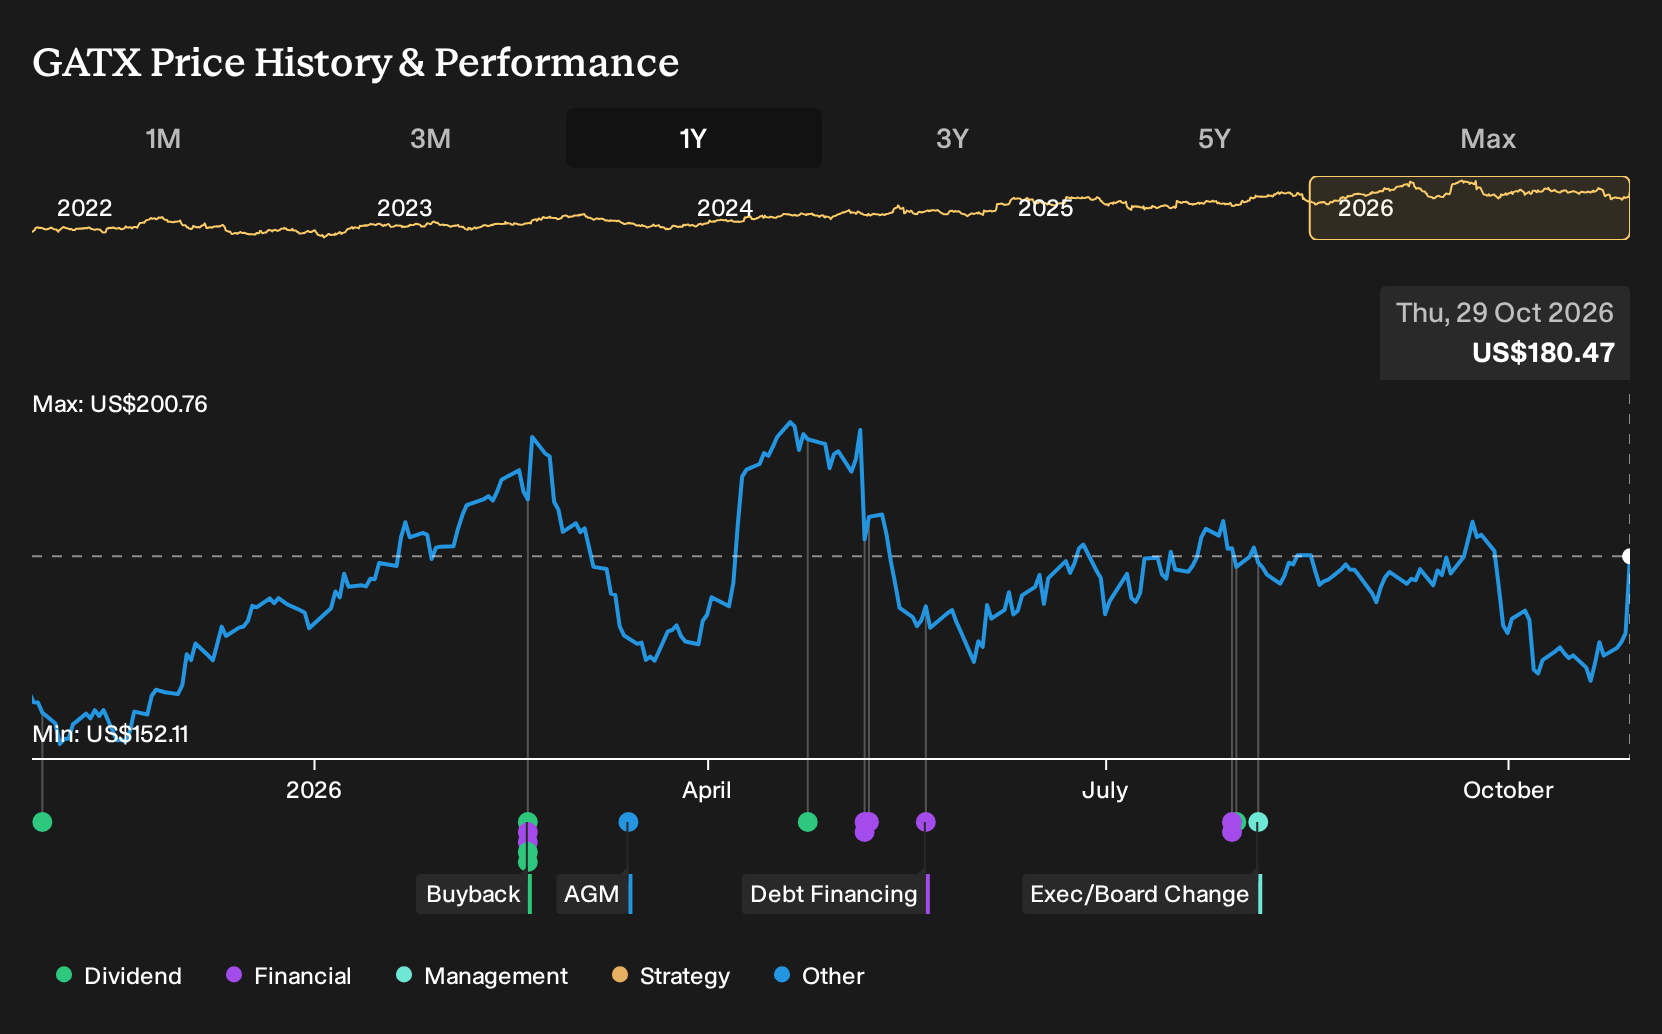
The clearest announcement tied to this catalyst is the guidance revision. GATX now expects 2026 diluted EPS to modestly exceed the prior US$9.90 to US$10.30 range. That outlook leans on strong Q3 revenue of US$598 million and diluted EPS from continuing operations of US$2.92.
Those figures sit alongside 98.4% Rail North America utilization and high renewal success rates, which together provide some operational backing to the raised outlook. For you as an investor, the question is whether that earnings power can offset ongoing balance sheet pressure and dependence on remarketing income over the next few quarters.
GATX's current analyst narrative points to revenues of US$2.6b and earnings of US$438.2 million by 2029, based on an assumed 8.5% yearly increase in revenue and an earnings rise of about US$76.3 million from US$361.9 million today.
Uncover why GATX's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community supplies 2 fair value views for GATX, stretching from about US$49.80 to US$219.25 per share. That spread clashes with optimism around tight railcar supply, high utilization and contribution from the Wells Fargo rail assets while reminding you that remarketing reliance, European softness and leverage leave plenty of room for sharply different opinions.
Explore another GATX fair value estimate, including one that suggests as much as 72% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GATX research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for GATX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GATX's overall financial health at a glance.
Looking for more GATX investment ideas?
If GATX has sharpened your focus on asset heavy businesses with recurring income, it can help to compare it with other opportunities that share some of the same strengths but differ on yield, risk or balance sheet quality.
- For investors who want potential mispricing backed by fundamentals, start by scanning a curated set of 30 high quality undervalued stocks that pair resilient cash flows with disciplined capital structures.
- If reliable income matters most to you, filter for companies that prioritize payouts and balance sheet strength through a group of 7 dividend fortresses built around higher yielding distributions.
- When capital preservation sits at the top of your checklist, narrow your watchlist to a 30 resilient stocks with low risk scores that screens for resilient businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com