


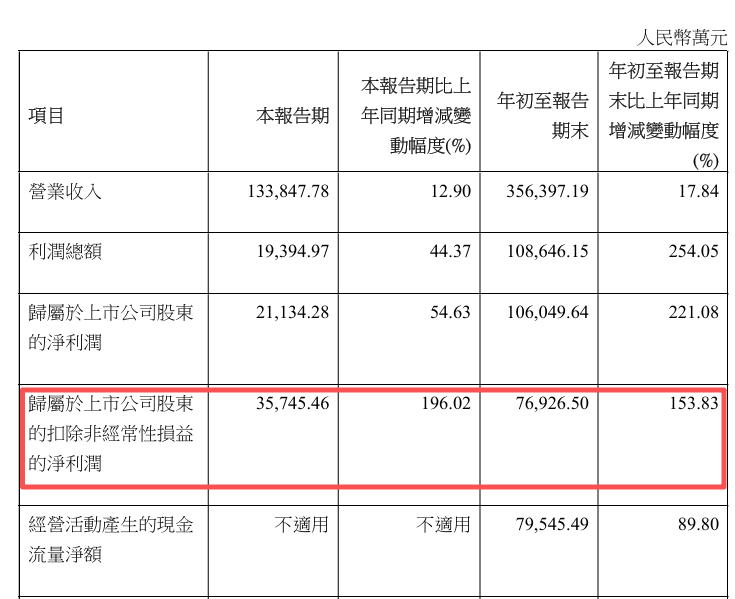
On October 28, Shanghai Fudan (01385) announced the results for the first three quarters of 2026. In the first three quarters, the company achieved revenue of 3,564 billion yuan, a year-on-year increase of 17.84%; net profit to mother of 1.06 billion yuan, an increase of 221.08%; and basic earnings per share of 1.29 yuan.
When the three numbers are put together, the most prominent one is not the total net profit of 1.06 billion yuan in Fudan, Shanghai, but the huge gap between profit growth of 221.08% and revenue growth of 17.84%. Profits are running ten times faster than revenue. Where does the money come from? Was it a one-time accounting reversal, or were changes in the business structure beginning to become apparent?
Product structure optimization and further release of profit flexibility
Looking deep into the Shanghai Fudan financial report, it is easy to find that the value of the company's three-quarter report is not the “221.08%” figure itself, but because it has verified one thing: after the inventory was cleared in 2025, the profit model of Fudan, Shanghai is shifting from being “dragged down by falling inventory prices” to “driven by product structure optimization.”
According to financial reports, net profit returned to mother in the first three quarters of Fudan, Shanghai still surged 153.83% year-on-year after deducting non-recurring profit and loss. This indicates a fundamental and trending improvement in the profitability of the main business. This is not only the result of a recovery in demand, but also a comprehensive reflection of the company's overall improvement in product competitiveness, cost control capabilities, and operational efficiency.
At the same time, the increase in gross margin is also a direct proof of the company's leap forward in profit quality. In the first three quarters, the company's comprehensive gross margin increased from 58.47% to 59.34%, and the third quarter's gross margin was as high as 63.26%, reflecting the increase in the share of high-margin products and the optimization of the product structure.
Judging from the business structure and inventory management, the explosive restoration of the profit side in Fudan, Shanghai is mainly unrelated to these two major internal changes.
In terms of business structure, during the reporting period, the company's product structure continued to be iterated at the high end, and the proportion of high-margin categories increased steadily. The company continues to eliminate low-value-added conventional products and concentrates resources on deepening high-barrier categories such as high-end programmable logic chips, automotive-grade chips, and intelligent computing power chips, driving the overall comprehensive gross margin to continue to rise, and profit space continues to open up.
According to financial reports, in the first three quarters, the company's FPGA and other product lines contributed 1,196 billion yuan in revenue in the first three quarters, which is the company's largest revenue source and core growth engine. This product line directly benefits from burgeoning demand in booming downstream fields such as artificial intelligence, high-performance computing, and communication base stations (5G-A). The “Fuwei Qinglong” JFMQL30TAI676H launched by the company uses a CPU+FPGA+AI multi-core heterogeneous fusion architecture to target high throughput and low latency scenarios such as image video, wireless communication, and data analysis, to promote the upgrading of products from traditional FPGA to heterogeneous intelligent computing power platforms. At the same time, the company launched the Agent intelligent FPGA development platform, covering code generation, simulation verification, deployment and delivery, and further improving the development ecosystem.
Non-volatile memory (revenue of 1,092 million yuan) and security and identification chips (revenue of 726 million yuan) form the company's stable cash flow and basic business market. Smart meter chips (revenue of 430 million yuan) and integrated circuit testing services (revenue of 120 million yuan) reflect the company's deep market segmentation and ability to vertically integrate the industrial chain, providing stable support for overall performance.
In terms of inventory management, the results of refined inventory management in Fudan, Shanghai were outstanding in the first three quarters, getting rid of the burden of historical operations. In the past downward cycle of the industry, chip companies generally faced inventory depreciation pressure, which eroded corporate profits. In 2025, the company's profits were suppressed by losses due to falling inventory prices. In 2026, this factor was reversed and became an important source of profit elasticity. During the period, the company actively optimized the inventory structure and strictly controlled inventory risks. Inventory price reduction losses fell sharply year on year, non-operating profit losses were drastically reduced, and profit flexibility was fully released.
As can be seen from the above, for Fudan in Shanghai, the three-quarter report is not a digital rebound under a low base, but rather a cash order where the product structure starts talking after inventory is cleared.
Prosperity has rebounded to the bottom, and domestic substitution and emerging scenarios are the wings
Of course, the profit elasticity of the Shanghai Fudan Third Quarterly Report is inseparable from coordination with industry trends.
In 2026, the domestic semiconductor industry ushered in a structural inflection point. The recovery in terminal demand was compounded by autonomous and controllable policies, and the boom in the chip industry continued to rise.
On the one hand, domestic replacement of high-end FPGA chips has entered a period of acceleration. For a long time, the domestic high-end programmable logic chip market has been monopolized by overseas oligarchs, the localization rate is low, and there is plenty of room for independent replacement. Under the general trend of localization of computing power and autonomous control of core chips, downstream government enterprises, industry, and computing power customers are rapidly entering the local supply chain. As a domestic FPGA leader, the company continues to seize the share of overseas alternatives with a mature product system and stable delivery capacity.
On the other hand, the three emerging booming racetracks continue to unleash dividends. Demand for AI edge computing power has exploded, driving demand for heterogeneous computing chips to continue to expand; domestic low-orbit satellite internet construction is speeding up, and the commercial aerospace industry chain has entered a period of rapid implementation; and the intelligent upgrading of new energy vehicles continues to drive demand for vehicle-grade storage and MCU chips. The combination of multiple industry trends has provided a broad market soil for the company to launch new products, and the external growth environment continues to improve.
Zhitong Finance has observed that during the reshuffle of the industry, market resources will also continue to be concentrated at the top — that is, leading companies with self-developed technical barriers, complete product matrices, and the ability to implement in multiple scenarios will also continue to reap market share and form a strong market pattern.
Among them, Shanghai Fudan, as a leading domestic FPGA company, is deeply tied to the booming industry circuit and fully enjoys the dual dividends of cyclical recovery+domestic substitution. Under the wave of localization of AI computing power, domestic demand for edge computing power and heterogeneous computing has exploded. The company's multi-core heterogeneous FPGA chips accurately match the needs of local computing power scenarios and continue to replace overseas products with the advantages of high adaptability, low cost, and customizability. The competitiveness of the industry continues to strengthen, and the leading position is becoming more stable.
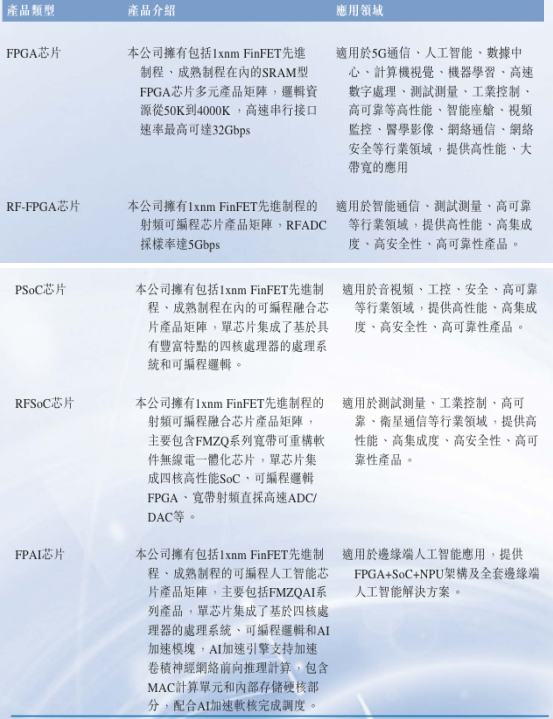
(Shanghai Fudan FPGA chip, source: 2025 report)
Therefore, as the boom in the chip industry continues to rise, Shanghai Fudan, as a leading domestic FPGA company, continues to reap the dividends of domestic substitution by relying on self-developed technology barriers, and the momentum for performance growth is also expected to be further unleashed.
Summarize
Reviewing the Shanghai Fudan 2026 three-quarter report, it is easy to find that the 221% increase in profit is not a short-term bubble, but an inevitable result of the company's cyclical hardening, continuous technological iteration, and deep cultivation of refined operations.
In the short term, industry recovery combined with inventory clearance, the company's profit flexibility was fully released, and the inflection point of operation was completely established; in the medium term, the product structure continued to be high-end, and the multi-category matrix hedged cycle fluctuations, and the growth chassis was solid; in the long run, the three golden tracks of card AI computing power, commercial aerospace, and automotive electronics continued to broaden, relying on the wave of domestic substitution.
This also means that even if the short-term stock price in Fudan, Shanghai follows mood swings, the long-term market capitalization still follows the implementation of performance — that is, performance continues to increase rapidly, and valuation repair comes to fruition. In the first half of 2026, the overall semiconductor sector fluctuated and adjusted, and the company's stock price fluctuated with industry sentiment, and valuations continued to be digested. As high-margin new products continue to be released, product structure continues to be optimized, and dividends on emerging tracks continue to be released, the company's profit elasticity is expected to continue to exceed expectations, and long-term value is entering a window of accelerated revaluation.