


Guidance Upgrade Puts Ipsen In Focus
Ipsen (ENXTPA:IPN) lifted its 2026 outlook, targeting around 23% sales growth at constant exchange rates and a core operating margin near 39%, supported by its core portfolio and Somatuline.
The guidance lift comes after a strong run in Ipsen’s share price, with a 1-month share price return of 8.8% and a year to date share price gain of 34.2%, even though the 90-day move declined 6.8%. Meanwhile, 1-year and 5-year total shareholder returns of 28.7% and 80.3% indicate that longer term holders have already seen substantial value creation around the upgraded outlook.
Scan how other pharmaceutical and biotech leaders are reacting to upgraded outlooks by reviewing the hand picked 227 resilient stocks with low risk scores alongside Ipsen.
Ipsen now looks like a stronger operation on paper after its upgraded 2026 targets and brisk share price climb. The harder question is whether that quality is already fully reflected in today’s €155.80 price.
Most Popular Narrative: 4% Undervalued
Ipsen's most followed valuation storyline places fair value at about €162.36, only modestly above the latest €155.80 close. This keeps attention firmly on what could shift that gap rather than on the headline number itself.
Anticipated late-stage pipeline catalysts in 2025 to 2026 across all three therapeutic areas, including pivotal readouts and further regulatory submissions, improve visibility on new product revenue streams, reducing future earnings risk from maturing assets.
Significant available cash and financial flexibility (€3b firepower, net cash balance) position the company to accelerate external innovation via targeted M&A or licensing, strengthening both pipeline depth and long-term earnings growth potential.
See why 7 investors see Ipsen as 4% undervalued.
Result: Fair Value of €162.36 (UNDERVALUED)
Still, Ipsen’s reliance on Somatuline and the possibility of tougher competition from products like CAM2029 could challenge the current pipeline-driven storyline.
Find out about the key risks to this Ipsen narrative.
Another Take On Ipsen’s Valuation
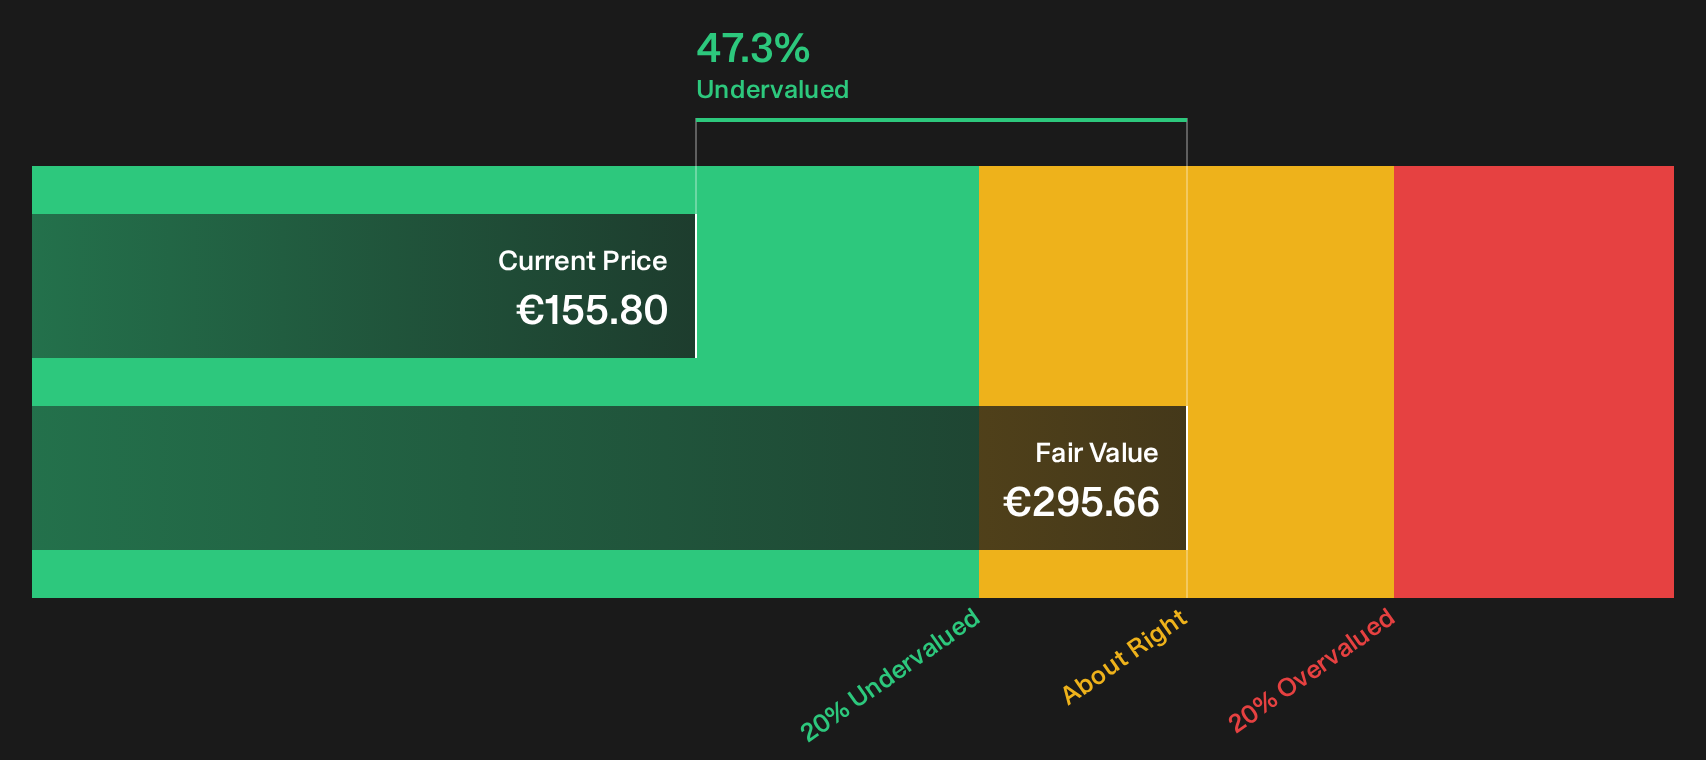
The first narrative leans on future earnings and analyst targets, which suggest Ipsen trades close to a fair value of about €162.36. A second lens tells a different story. Simply Wall St's DCF model puts future cash flow value near €295.66 per share, implying the current €155.80 price screens as heavily undervalued.
These two methods produce very different answers. This leaves you deciding which set of assumptions feels more realistic for Ipsen over the long haul.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in Ipsen's story so far. If that tension between risk and upside matters to you, move quickly and pressure test the company’s data, its pipeline expectations and its cash flow assumptions against your own thresholds, then close the loop by reviewing the 3 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Ipsen?
If Ipsen has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now or risk missing other compelling setups hiding in plain sight.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (204 results) before the market fully prices in their strength.
- Hunt for mispriced quality where expectations still look conservative by reviewing the 198 high quality undervalued stocks that fit your return and risk preferences.
- Secure a stream of cash returns while you wait for price moves by filtering through the income focused 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com