


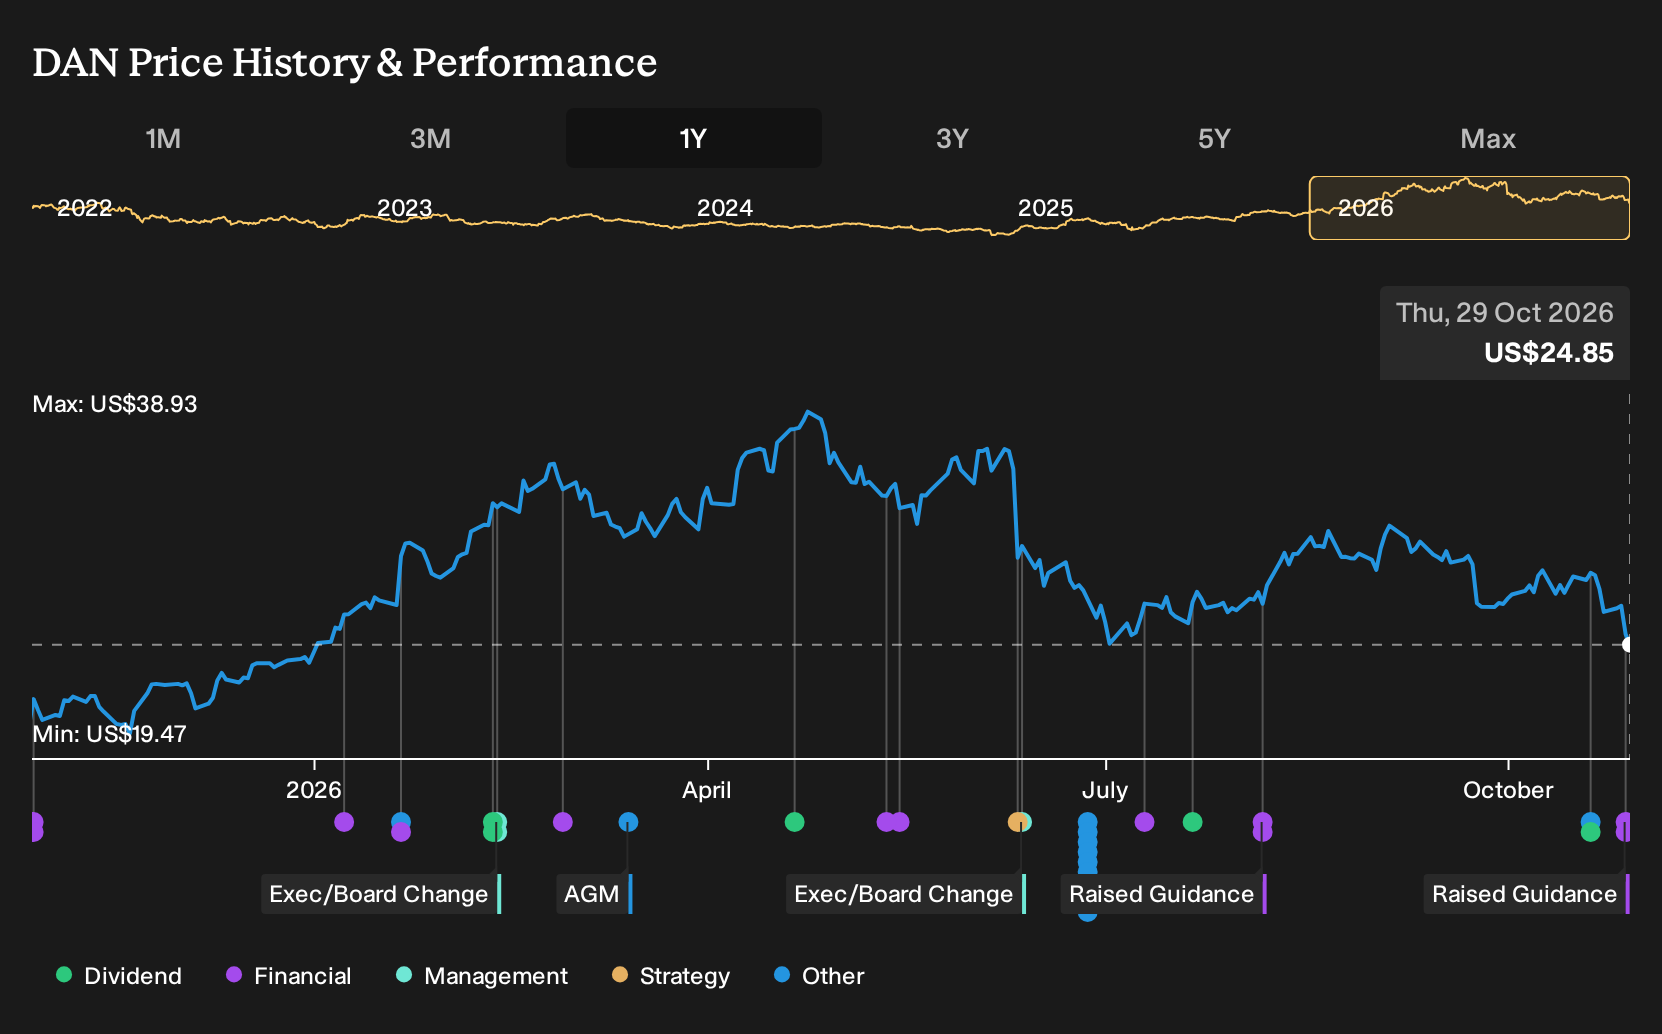
- Dana Incorporated reported third quarter 2026 sales of US$2,038 million and net income of US$15 million, raised its full year 2026 sales outlook to a range of US$7.75 billion to US$7.85 billion, and affirmed a quarterly dividend of US$0.12 per share.
- Despite higher sales and an expanded adjusted EBITDA margin, investor focus has shifted to Dana's uneven free cash flow and execution risks around cost savings and major programs.
- This article examines how Dana's raised 2026 sales guidance and free cash flow concerns could reshape the broader investment narrative.
Dana Investment Narrative Recap
To own Dana, you need to believe the business can turn healthy sales into more reliable earnings and cash, while managing its debt load and customer concentration. The raised 2026 revenue outlook points to firm demand and good backlog conversion. In the near term, the main swing factor is still execution on major programs and cost savings, not this modest guidance bump.
The biggest risk right now is that uneven free cash flow and program timing keep clashing with leverage, dividend commitments, and share repurchases. Q3 results, with sales growth but much lower quarterly net income versus last year, keep that concern front and center rather than resolving it.
The most relevant fresh data point is Dana’s raised 2026 sales outlook to US$7.75b to US$7.85b. That update sits alongside an expanded adjusted EBITDA margin and management commentary that most of the targeted US$325 million of cost savings is already in place. The operational story is about throughput and efficiency, not just top line.
For you as a shareholder, the key question is whether that higher expected revenue and margin profile actually drops through to steadier free cash flow after working capital, program launches, and interest. If free cash flow remains choppy, then cost targets, the Eaton Mobility deal, and share repurchases all become harder to execute without adding strain.
Dana's current analyst narrative points to about US$12.2b in revenue and US$1.0b in earnings by 2029, based on an assumed 17.1% yearly rise in sales and an earnings swing of roughly US$1.067b from a loss of US$67.0m today.
Uncover why Dana's fair value indicates a 51% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Dana centers on the bullish analysts who treat the Dana 2030 plan itself as the main catalyst. Before this Q3 report, that group was modeling revenue reaching about US$13.5b and earnings of roughly US$1.3b by 2029. Those forecasts did not factor in today’s guidance tweak, so opinions may change as new data becomes available.
Explore 2 other Dana fair value estimates, including one that suggests potential upside of up to 407% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dana research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dana. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dana's overall financial health at a glance.
Looking For More Ideas Beyond Dana?
If the Dana story has you thinking about where rising sales and tight execution could translate into better risk and reward, it can help to line it up against peers facing similar trade offs on cash generation, leverage, and capital returns.
- For investors who want value with quality, compare Dana's setup with a wider group of companies that screen as 30 high quality undervalued stocks and see which balance sheets and cash profiles you prefer.
- If capital preservation matters most, weigh Dana against a universe of businesses screened as 30 resilient stocks with low risk scores and check how their earnings stability and finances stack up.
- When you want resilience plus room to grow, set Dana alongside companies highlighted in our list of solid balance sheet and fundamentals (23 results) and see which ones fit your own comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com