


In recent weeks, global markets have experienced a shift in leadership as small-cap and value-oriented stocks outperformed amid volatility driven by AI investment concerns and rising oil prices. As the Russell 2000 Index leads gains among major benchmarks, investors are increasingly on the lookout for undiscovered gems that could offer promising potential in this dynamic environment. Identifying a good stock often involves looking for companies with strong fundamentals and growth prospects that can thrive despite broader market uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Shengda ResourcesLtd | 44.63% | 9.29% | 15.82% | ★★★★★☆ |
| Shandong Head GroupLtd | 48.27% | 6.77% | -13.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Infore Environment Technology Group | 28.47% | 4.58% | -7.19% | ★★★★★☆ |
| Shengyi Electronics | 40.67% | 26.18% | 51.71% | ★★★★☆☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
Let's dive into some prime choices out of from the screener.
Besqab (OM:BESQAB)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Besqab AB (publ) focuses on developing residential housing properties in Sweden, with a market capitalization of SEK2.77 billion.
Operations: Besqab generates revenue primarily from the development and sale of residential housing properties in Sweden. The company has a market capitalization of SEK2.77 billion.
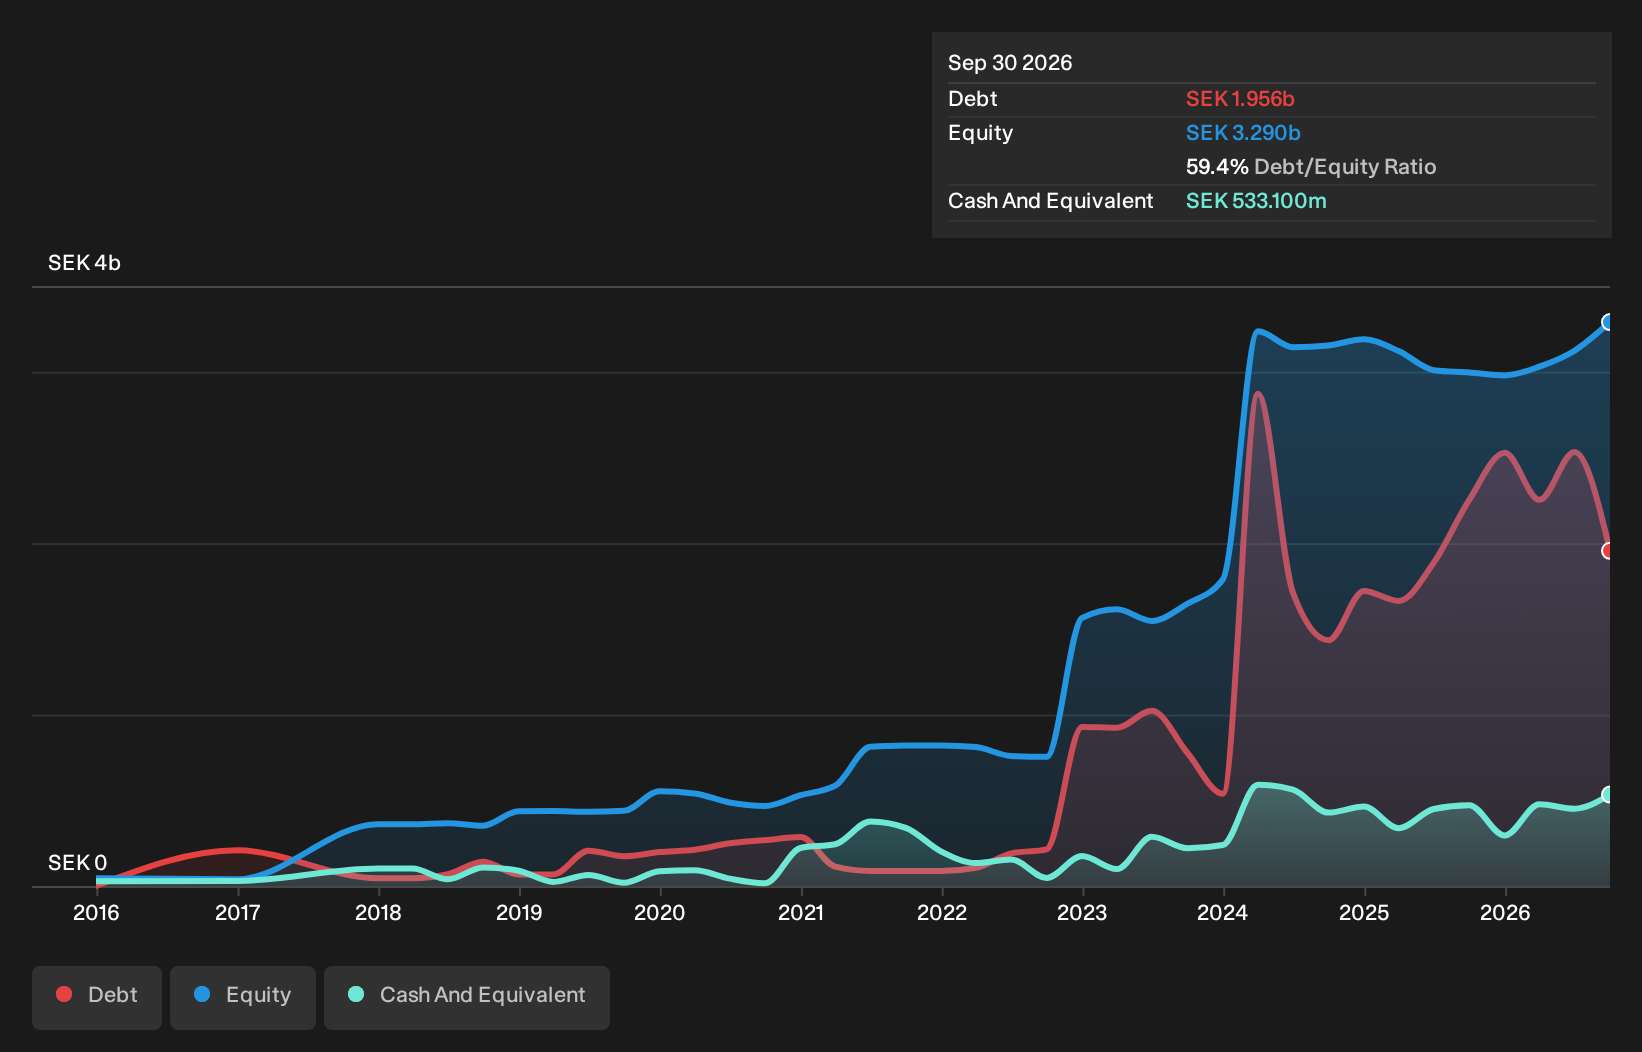
Besqab, a burgeoning player in the real estate sector, has recently showcased impressive financial strides. Reporting sales of SEK 1.49 billion for Q3 2026, up from SEK 332.3 million the previous year, Besqab also turned a net loss into a profit of SEK 221.2 million over the same period. The company's net debt to equity ratio stands at a high 43%, yet its interest coverage is robust with EBIT covering interest payments by 21.6 times. Despite not being free cash flow positive, Besqab's strategic focus on leadership and organizational growth seems poised to support its continued expansion efforts in residential development projects across Sweden.
- Dive into the specifics of Besqab here with our thorough health report.
Understand Besqab's track record by examining our Past report.
Henan Lingrui Pharmaceutical (SHSE:600285)
Simply Wall St Value Rating: ★★★★★☆
Overview: Henan Lingrui Pharmaceutical Co., Ltd. is involved in the research, development, production, and sale of drugs in China, with a market cap of CN¥11.34 billion.
Operations: Henan Lingrui Pharmaceutical generates revenue primarily from the sale of drugs in China. The company's financial performance is reflected in its market cap of CN¥11.34 billion.
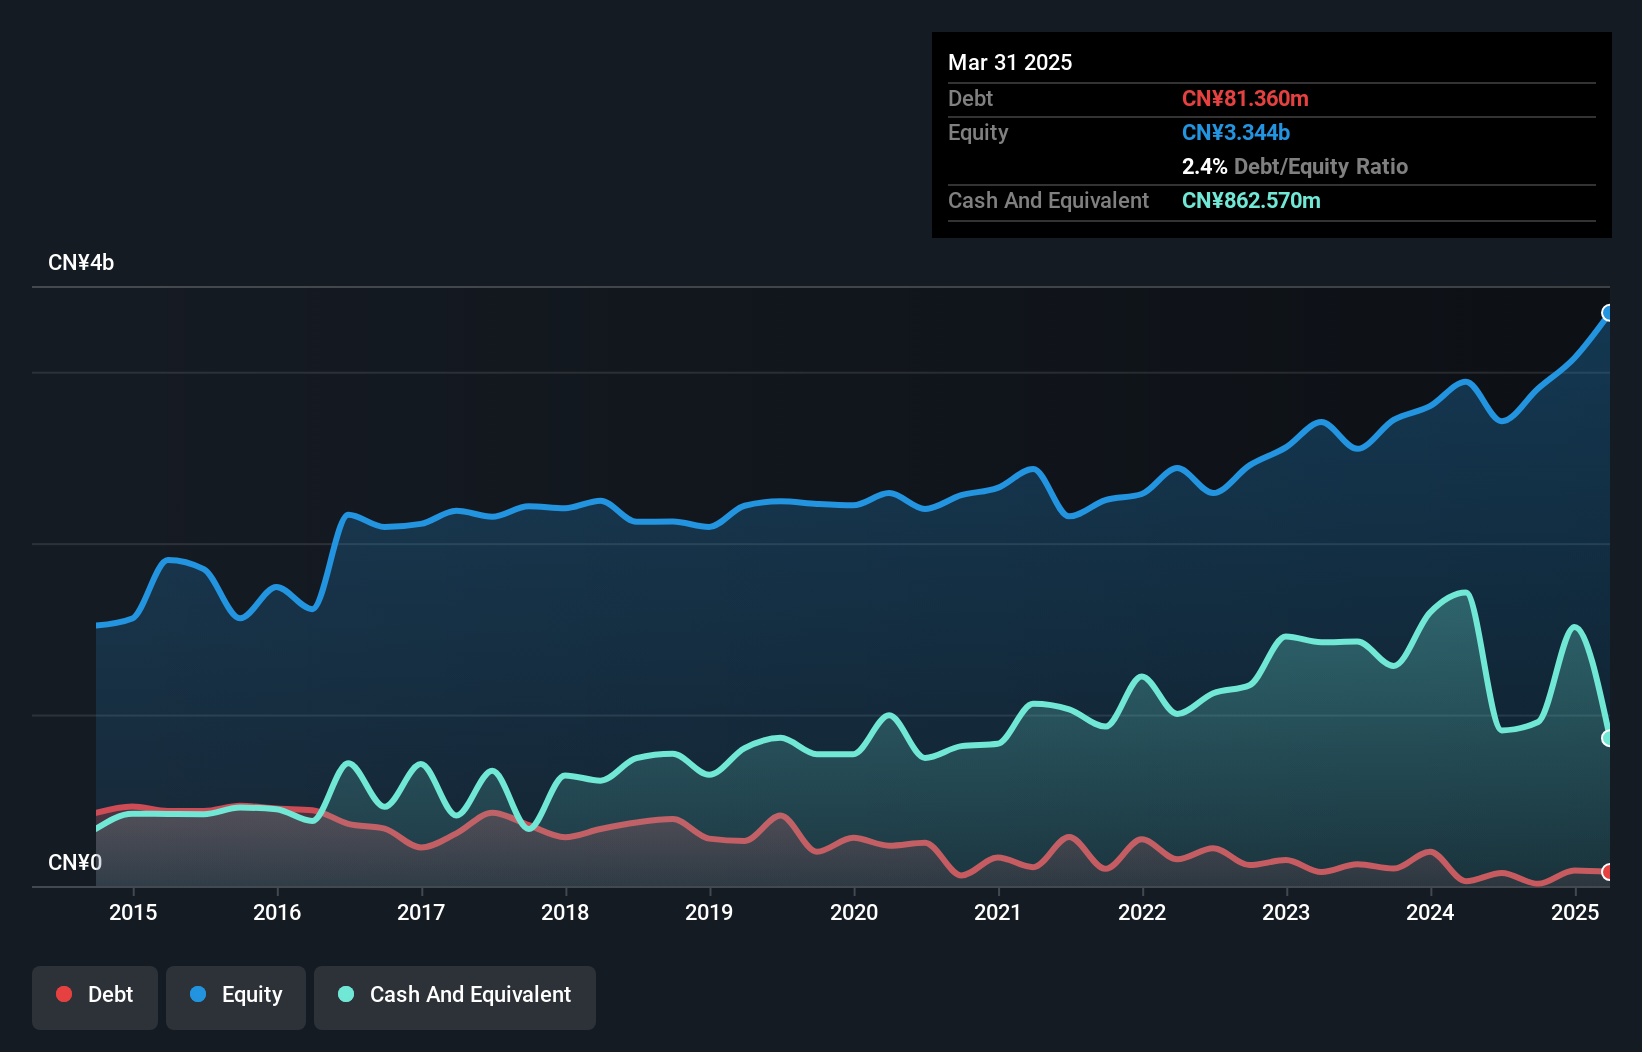
Henan Lingrui Pharmaceutical, a smaller player in the pharmaceutical sector, has shown promising financial performance. Over the past year, earnings grew by 3.5%, outpacing the industry average of -0.6%. The company's debt to equity ratio increased from 4.4% to 9.1% over five years, but it holds more cash than its total debt, suggesting sound financial health. Recent reports indicate sales for nine months ended September 2026 reached CNY 3.14 billion with net income at CNY 718.8 million, up from CNY 650.93 million in the previous year, reflecting robust operational efficiency and potential for continued growth in earnings per share at CNY 1.27 compared to last year's CNY 1.15.
Aisan Industry (TSE:7283)
Simply Wall St Value Rating: ★★★★★☆
Overview: Aisan Industry Co., Ltd. manufactures and sells automotive parts both in Japan and internationally, with a market capitalization of ¥117.13 billion.
Operations: Aisan Industry generates revenue primarily from the sale of automotive parts in Japan and international markets. The company's financial performance is influenced by its ability to manage production costs and optimize its profit margins.
Aisan Industry, a relatively small player in the auto components sector, has shown steady growth with earnings increasing 11.9% annually over the past five years. Despite not matching the industry's recent 23.8% surge, Aisan's net debt to equity ratio of 0.8% is deemed satisfactory and suggests prudent financial management. Trading at a significant discount of 46.5% below its estimated fair value, it appears undervalued compared to peers. Recent updates indicate an optimistic outlook with revised guidance projecting ¥335 billion in sales and operating profit of ¥19.5 billion for fiscal year ending March 2027, alongside increased dividends per share expectations for shareholders.
- Get an in-depth perspective on Aisan Industry's performance by reading our health report here.
Examine Aisan Industry's past performance report to understand how it has performed in the past.

Turning Ideas Into Actions
- Unlock more gems! Our Global Undiscovered Gems With Strong Fundamentals screener has unearthed 181 more companies for you to explore.Click here to unveil our expertly curated list of 184 Global Undiscovered Gems With Strong Fundamentals.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com