


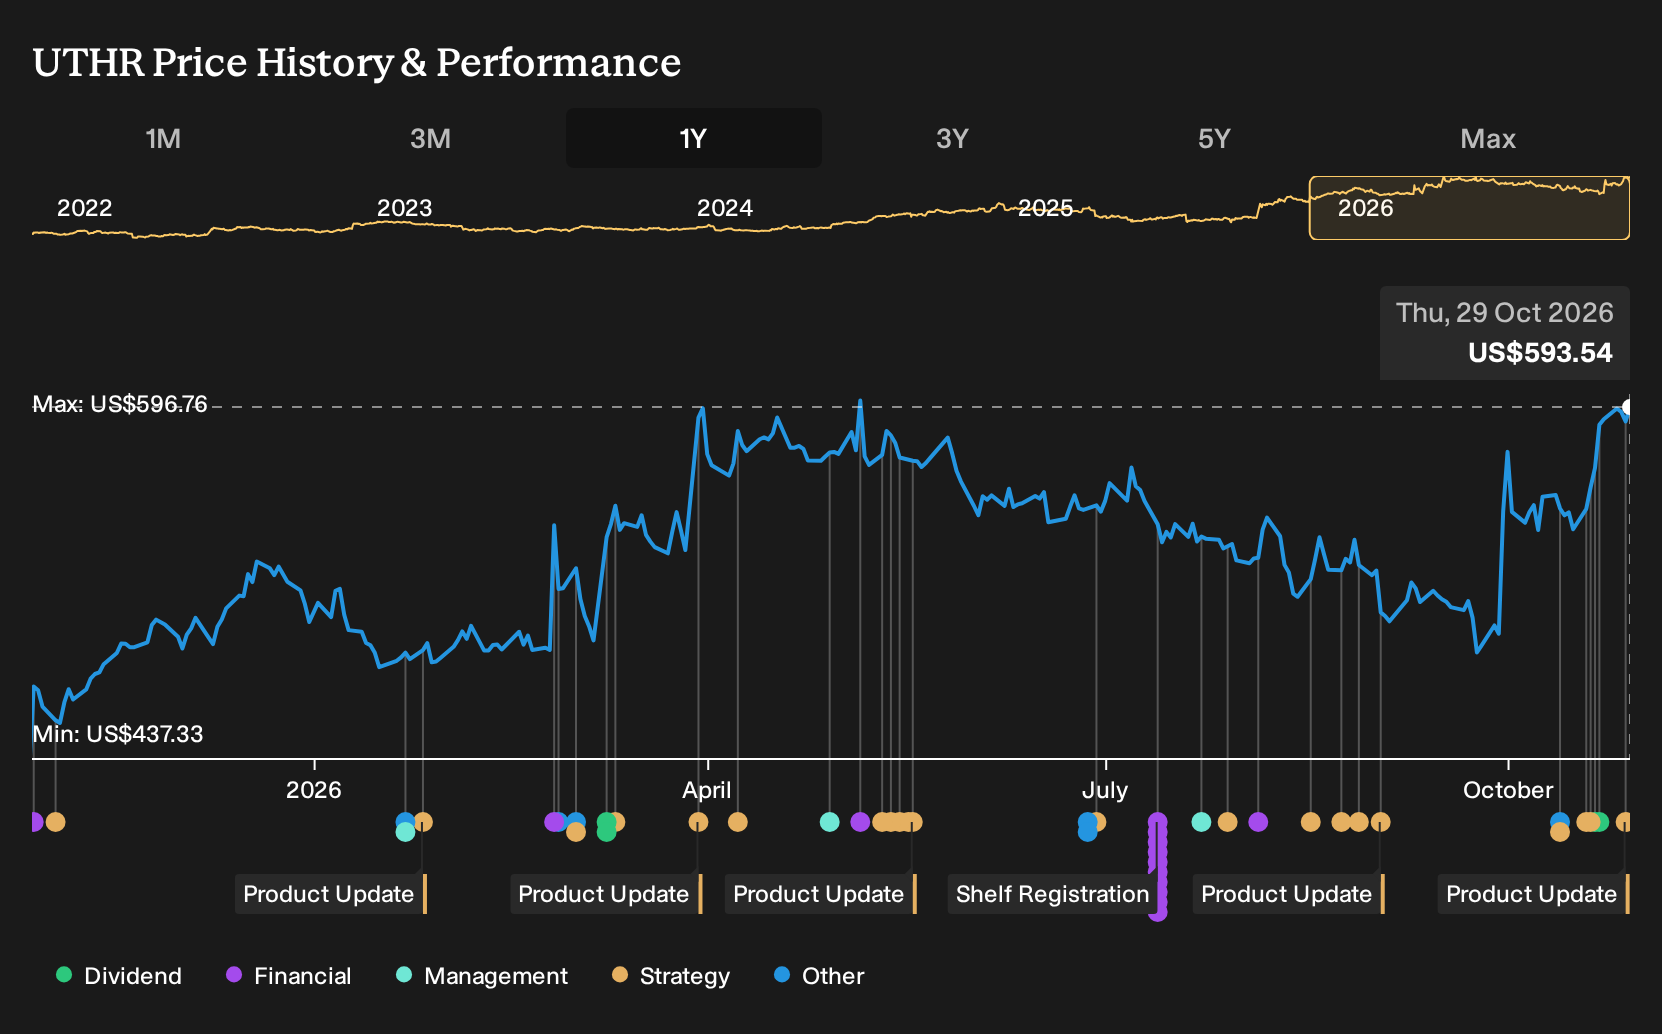
If United Therapeutics sat on your watchlist instead of in your account, the move over the last 12 months may feel expensive. Investors who held United Therapeutics over the past year are up 30.9%, including dividends. The obvious question is what, if anything, could have pointed you to that outcome when the clock started in late October 2025, particularly the bullish assumption that pulmonary therapies and organ manufacturing would support stronger, more durable profitability than many expected.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
United Therapeutics is not the only name tied to this theme. Zero in on 36 healthcare AI stocks and compare how each one is priced.
The Two United Therapeutics Stories Investors Had To Weigh
The shares cost US$455 at the start of the period, and anyone looking at United Therapeutics then had to choose between two very different stories about what that price implied.
On the bullish side, a Fair Value of US$510, which sat 12% above the start price, rested on assumptions that revenue could grow 14% a year to reach US$4.6b by 2028. This view was helped by expectations of stronger Tyvaso DPI adoption and successful IPF indications.
The cautious view put Fair Value at US$295, or 35% below the start price. It leaned on concerns that reliance on Tyvaso and Remodulin, combined with patent expiries and faster generic entry, could shrink profit margins to 29% by 2028.
What The Results And Pipeline Said About United Therapeutics
United Therapeutics cleared FDA review to start UHeart and advanced Tyvaso and ralinepag in pulmonary disease, which leaned toward the bullish thesis that specialty therapies and organ work could support stronger economics. In the same period, revenue declined from US$798.6m to US$783.3m, while net income and net margin increased. That mix had both positive and negative implications.
The useful takeaway for other stocks is straightforward. When a thesis rests on premium treatment pricing and pipeline depth, it can be helpful to track reported net margin and concrete regulatory milestones rather than focusing primarily on headlines about analyst targets.
What United Therapeutics' 1 Year Run Already Prices In
United Therapeutics now trades at US$594, after a 30.9% gain over the past year. The selected Narrative places its Fair Value below that price and frames today’s quote as rich for a business still tied closely to pulmonary hypertension therapies.
That Narrative argues buyers now must assume smooth execution on pulmonary fibrosis launches and organ platforms despite flat recent revenue and higher spending needs.
"Although United Therapeutics now has highly statistically significant Phase 3 data in idiopathic pulmonary fibrosis and a supplemental application under FDA review, the recent revenue decline of 1.9% year over year and withdrawal of 2026 growth guidance signal that execution risk in converting pulmonary fibrosis trial success into durable revenue growth is higher than the current long-term revenue targets imply."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 44% below our estimate - converts a sizable contracted project backlog into cash while limiting dispute risk.
- Company 2 - 23% below our estimate - embeds AI assistants into productivity, coding and security workflows within one ecosystem.
- Company 3 - 40% below our estimate - expands from solar trackers into storage and inverters to deepen project hardware integration.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com