


ID Logistics Group has delivered a solid multi‑year share price gain, even though the stock is down so far this year. That naturally raises the question of whether that trajectory is still backed by the earnings power of the business. With fresh growth headlines on the table, the key issue for investors is how much of that story is already reflected in today’s valuation.
- Over the past 3 years the share price has advanced 39.4%, which puts real weight on the question of whether the current earnings base can justify that climb.
- Recent double digit revenue growth, supported by new contracts and North American expansion, may support expectations for stronger profits and cash generation that feed into what investors are willing to pay for ID Logistics Group’s earnings.
- The analysts covering ID Logistics Group have run their own numbers. See what analysts think ID Logistics Group's shares could be worth.
For investors, the debate is whether the current share price around €362.5 is reasonably aligned with what ID Logistics Group is earning today and is expected to earn in the future.
If you want to stress test this same earnings focused question beyond ID Logistics Group, it is worth scanning a wider field of our screener containing 607 high quality undiscovered gems
Has ID Logistics Group Run Too Far on Earnings?
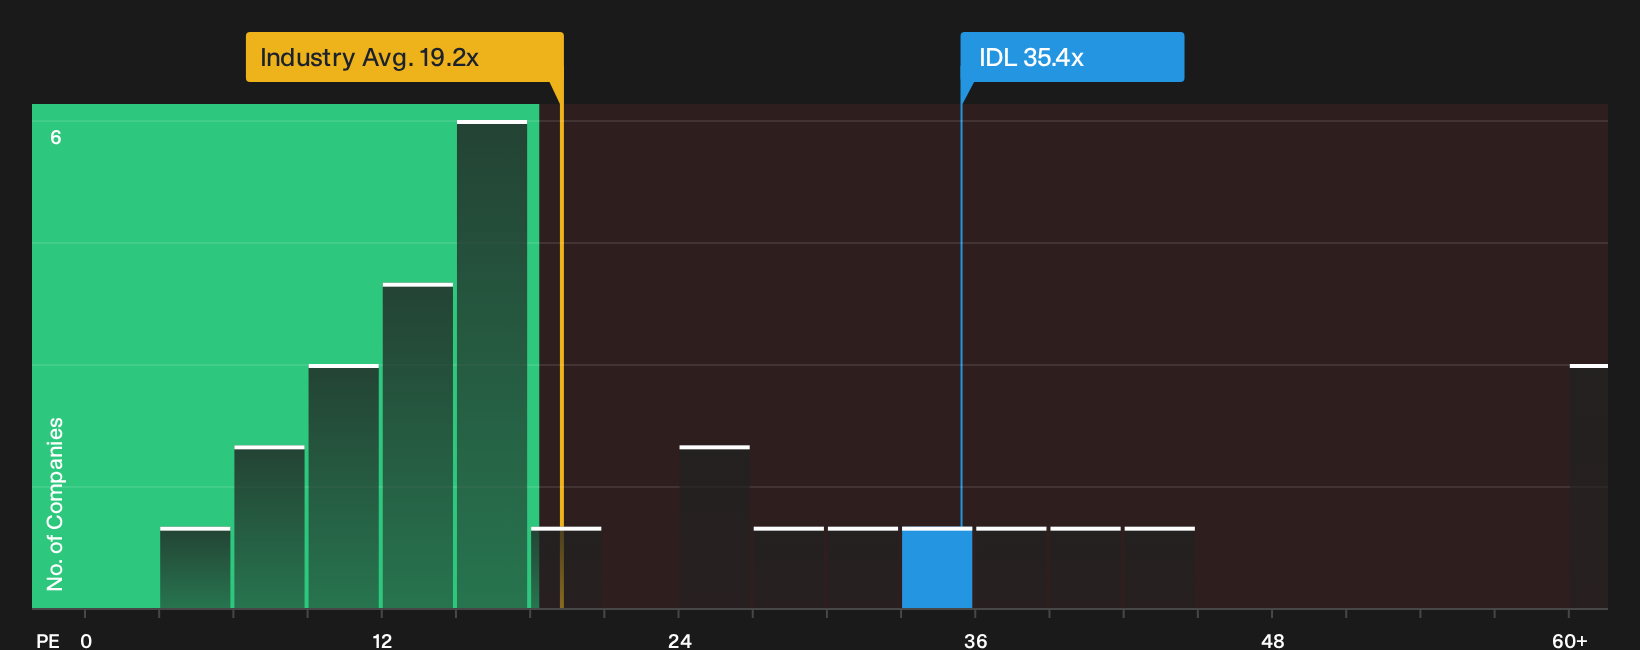
P/E fits ID Logistics Group because earnings are the main lens investors use for an established logistics operator with meaningful profit already in place. On this measure, the stock trades on about 35.4x earnings, compared with roughly 14.8x for the wider logistics industry and a peer group near 15.4x. That is a steep premium, which means you are paying much more for each euro of profit than for typical sector alternatives.
The internal fair multiple model, which blends factors like margins, scale, growth profile and risk, points to a lower P/E than the one the market is currently assigning. On this framework the shares screen as overvalued. Despite the recent 25.6% Q3 2026 revenue jump and North American contract wins lifting sentiment, the valuation already bakes in a lot of optimism about how ID Logistics Group will convert that top line into durable earnings. Explore the numbers behind ID Logistics Group's P/E valuation.
The ID Logistics Group Narrative: What Would Justify Today's Price?
Narratives pick up where ID Logistics Group's valuation puzzle leaves off by spelling out which combinations of growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on Simply Wall St’s Community page. Each scenario ties a fair value estimate to a clear set of potential catalysts and risks for ID Logistics Group, so you can track over time which version of the story is gradually matching reality.
A clear, number driven Narrative on ID Logistics Group gives you a single, testable view on whether the recent 25.6% revenue growth and North American expansion eventually translate into earnings that match the current P/E premium. It turns vague optimism or concern into concrete assumptions that can be checked as new contracts mature and reported results arrive.
Share your own Narrative for ID Logistics Group and set out the assumptions behind your valuation.
One more ID Logistics Group check that belongs next to the earnings story
Price, contracts and profit power only tell part of the ID Logistics Group story. The people steering the operation and how they are rewarded can heavily influence what happens next. See who runs ID Logistics Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com