


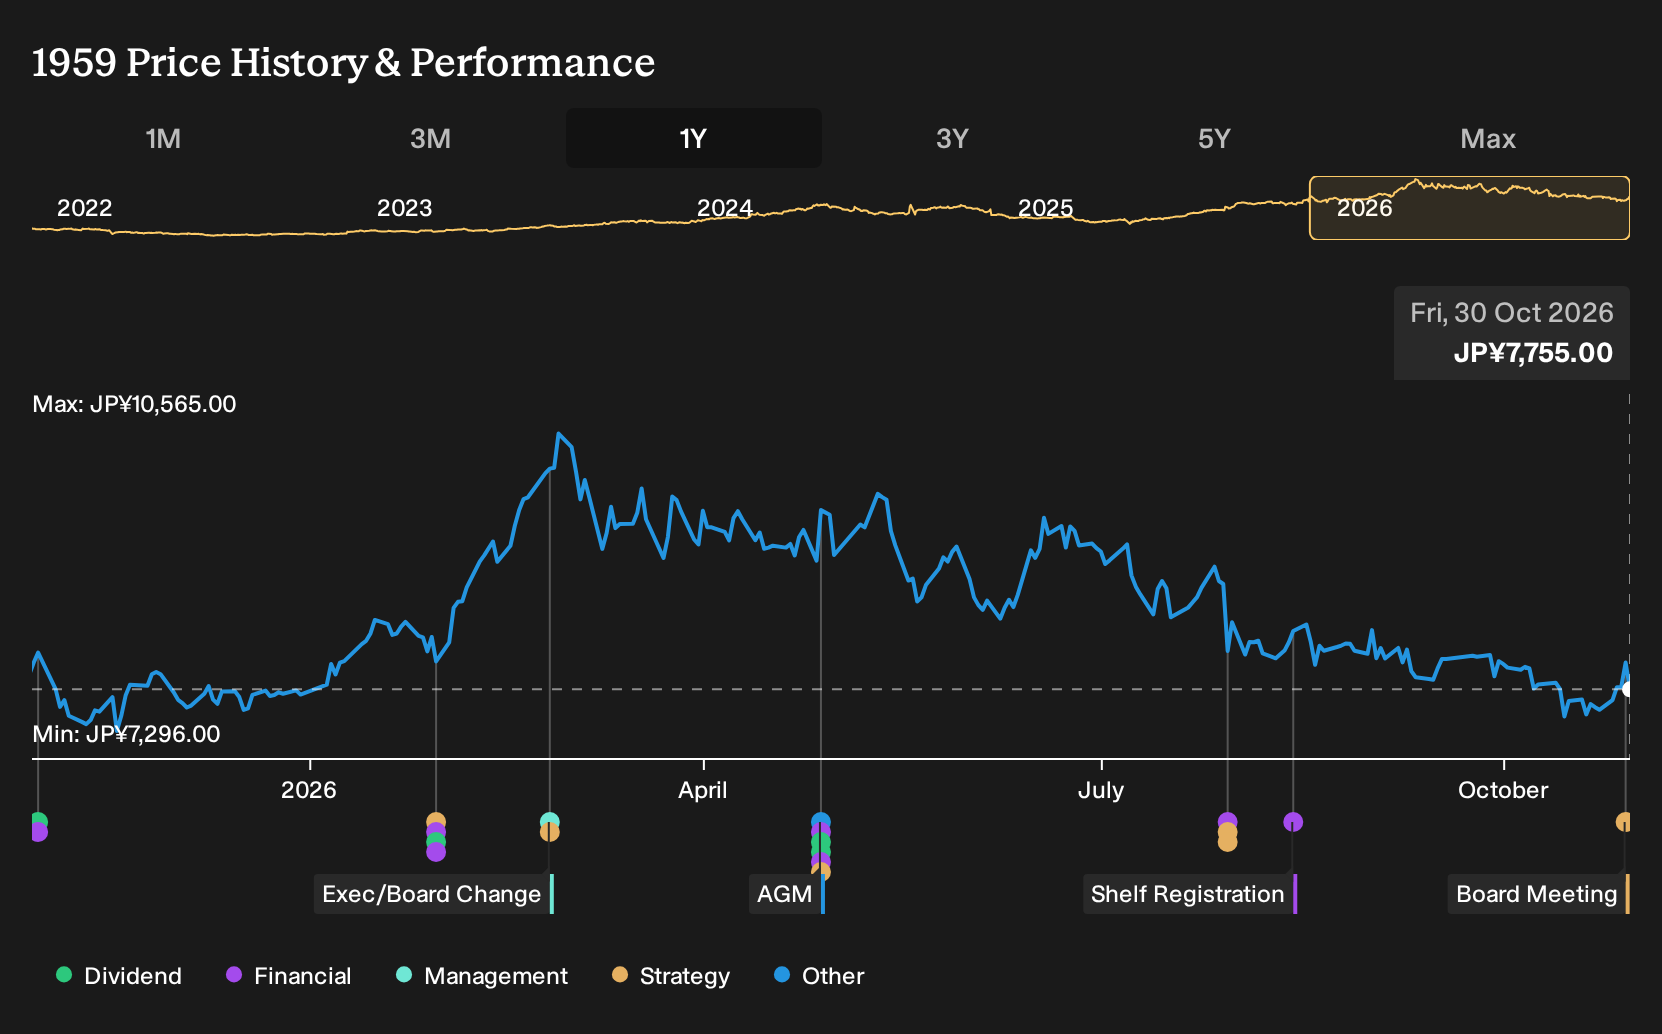
- Kraftia Corporation held a board meeting on October 29, 2026, to review an interim dividend from surplus and a possible increase in its year end dividend forecast.
- The focus on both an immediate payout and a higher full year dividend plan highlights how Kraftia is weighing cash returns against internal funding needs.
- This review of the year end dividend outlook also helps shape Kraftia's broader investment narrative and how the company approaches capital allocation.
Compare Kraftia's dividend reset with other companies returning cash to investors by scanning our hand picked list of 28 dividend fortresses today.
What Is Kraftia's Investment Narrative?
Kraftia is essentially a high execution construction and infrastructure contractor, so the big picture belief is simple. You need to think this business can keep winning work in power networks, building systems, and telecom projects in Japan while converting that order book into solid earnings without stretching its balance sheet. The recent board meeting on an interim dividend and a higher year end payout ties directly into that story. Management is signaling confidence in current profitability and cash generation, even after a period where the share price has fallen 3.9% over 30 days and 8.7% over 90 days.
In the short term, the key swing factors for Kraftia are project execution, pricing discipline in construction contracts, and the capital intensity of new infrastructure and renewable projects. Earnings have grown faster than the broader construction industry and are forecast to rise further. This underpins the willingness to review a bigger dividend. The catch is that existing payouts are not well covered by free cash flow, so any reset higher increases the pressure on working cash and on how aggressively the company can pursue new jobs, especially with the board already going through a period of higher turnover.
Even so, there is one dividend related weak spot that sits uncomfortably next to this more generous payout story...
There's only one way to know the right time to buy, sell or hold Kraftia. Head to Simply Wall St's company report for the latest analysis of Kraftia's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kraftia research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kraftia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kraftia's overall financial health at a glance.
Looking For More Kraftia Style Income Ideas?
If Kraftia's dividend reset has you thinking about how cash returns fit into your wider portfolio, it can help to scan other companies with similar or complementary traits. The Simply Wall St Screener lets you move quickly from this single stock to a broader watchlist that matches the kind of risk, income, or quality profile you want.
- If you care most about resilient balance sheets and room to fund future projects, start with a list of solid balance sheet and fundamentals (22 results) to see which businesses keep their finances tight while still investing for growth.
- If income is your priority and you want payouts that aim to be meaningful, review our 28 dividend fortresses that may align with a yield focused approach.
- If you prefer targeting under the radar quality, widen your search with a 71 high quality undiscovered gems that filters for strong fundamentals which the broader market may not fully be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com